7.03 Auditor's report drafting slips: a climate page reference that lands on the wrong pages and a mislabelled performance materiality basis
UK Company C · an AIM-quoted scientific instruments group · Drafting slip
In brief
The auditor's report refers to the Group's climate [wording masked] [n] to [n]', which hold the Chief Executive's, new Chief Executive's and Chief Financial Officer's reports and the business model, while the sustainability report and the non-financial and sustainability information statement are on pages 25 to 41. In the materiality table, the basis of Group performance materiality for 2025 reads '75% of parent company materiality', where the 2024 Group column reads '65% of Group materiality'.
The evidence, as filed
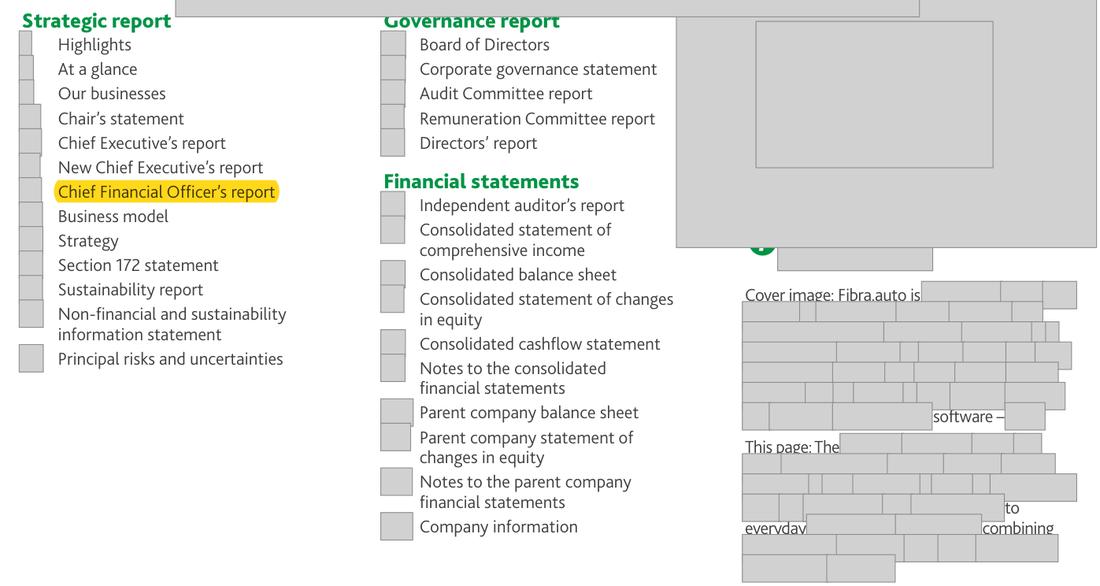
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 60; Annual Report 2025, page 62. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 'pages 14 to 22' for the climate commitment; Group 2025 performance materiality basis 'of parent company materiality' | What the rule requires The climate pages ([n] to [n]); 'of Group materiality' |
Why it matters
Minor loss of clarity for readers of the auditor's report.
Exposure
Drafting only; no sanction.
Our workings
The auditor's page reference does not land on the climate commitment: the only 'climate' hits on pages 14 to 22 are about the business climate. The Group column of the materiality table should describe Group performance materiality as a share of Group materiality, as the 2024 column does: the [amount] shown is 75% of the [amount] Group materiality, not of the [amount] parent company materiality.
Management’s best defence, and our reply
The Company could say these are slips in the auditor's own text that mislead no one: the figures in the table are right and the climate pages are listed in the contents. That is right as to impact, so they are drafting slips only, for the Audit Committee to raise with the auditor.
The fix
- Ask the auditor to correct the page reference to the climate disclosures and the Group performance materiality basis to 'of Group materiality'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Auditor's page reference for the climate commitment | Document | Annual Report 2025, page 60 |
| 2 | Contents: pages 14 to 22 hold [wording masked] Officer's reports; the sustainability report starts on page 25 | Document | Annual Report 2025, cover and opening pages |
| 3 | Basis of performance materiality: the 2025 Group column cites parent company materiality, the 2024 Group column cites Group materiality | Document | Annual Report 2025, page 62 |
| 4 | Materiality row: Group 2025 [amount], parent company 2025 [amount] | Document | Annual Report 2025, page 62 |
| 5 | Performance materiality row: Group 2025 [amount], against Group materiality [amount] | Document | Annual Report 2025, page 62 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.