6.02 The carbon-per-revenue measure, a climate target, is now divided by Organic revenue rather than Group revenue, which turns a fall into a rise, and the per-employee measure switched headcount basis without explanation
UK Company C · an AIM-quoted scientific instruments group · Compliance or disclosure gap
In brief
The company targets a falling ratio of tonnes of carbon dioxide equivalent (tCO2e) per £m of revenue and reports [n] for 2025 against [n] for 2024, a rise it attributes to one subsidiary's tariff. Both figures equal market-based Scope 1 and 2 emissions divided by Organic revenue ([n] and [n], in £ million), not by Group revenue ([n] and [n], in £ million); on Group revenue, the basis the 2024 report used, the ratio fell from [n] to [n]. The per-employee ratio also moved from the [n] full-time equivalents (FTE) in the finance review to a [n] count, and neither change is described anywhere in the 2025 report.
The evidence, as filed
Further pages withheld to protect the company’s identity (four): Annual Report 2025, page 31; Annual Report 2024, page 30; Annual Report 2025, page 20; Annual Report 2024, page 19. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows tCO2e/£m revenue [n] (2024: [n]) = [n] / [n] and [n] / [n] (Organic revenue); tCO2e/FTEs [n] (2024: [n]) = [n] / [n] and [n] / [n]; the 2024 report gave [n] and [n] for 2024 on Group revenue and [n] FTE | What the rule requires The ratio computed on Group revenue ([n], 2024: [n]) and FTE consistently with the prior year, or the change of denominator stated and the comparative re-presented, with the calculation described as the law requires |
The rule
Companies Act 2006 s.414CB(2A)(h)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
a description of the key performance indicators used to assess progress against targets used to manage climate-related risks and realise climate-related opportunities and of the calculations on which those key performance indicators are based
Companies Act 2006 s.414C(3)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The review required is a balanced and comprehensive analysis of
Why it applies here: the revenue denominator was changed to Organic revenue, which excludes the three businesses bought in 2024 whose emissions are included in the numerator (the restatement note says [name] [subsidiary]' 2024 Scope 1 and 2 emissions were added).
Why it matters
- A reader is told carbon intensity per £m of revenue rose against a target to reduce it; the numerator includes businesses the Organic denominator excludes, so the ratio overstates intensity.
A reader is told that carbon intensity per £m of revenue rose against a target to reduce it, when on the Group revenue basis used last year it fell; the numerator includes businesses that the Organic denominator excludes, so the ratio overstates intensity.
Exposure
No fine attaches. The realistic consequence is a Financial Reporting Council (FRC) Corporate Reporting Review question on the description of key performance indicator calculations and an undertaking to re-present the measure.
Our workings
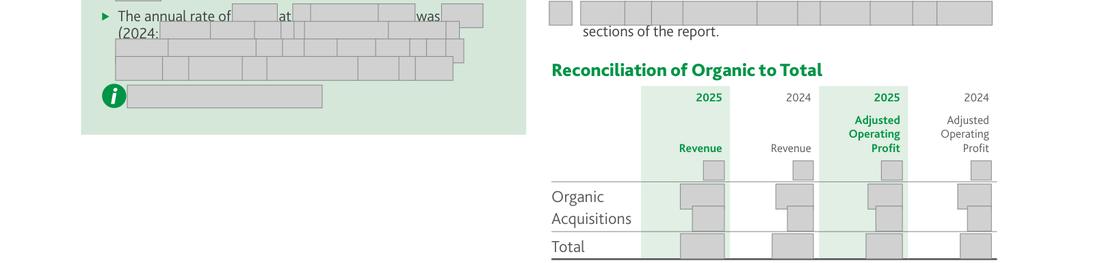
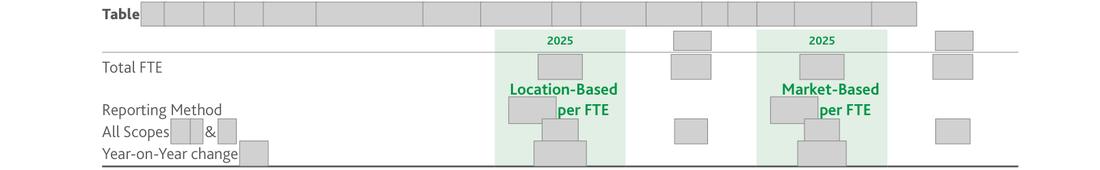
page 31 lists the climate-related targets, including [wording masked], and the table gives market-based emissions of [n] tonnes (2024: [n]), tCO2e/£m revenue of [n] (2024: [n]) and tCO2e/FTEs of [n] (2024: [n]). The narrative says the increase [wording masked]. The finance review gives Group revenue of [n] (2024: [n]) and Organic revenue of [n] (2024: [n]), in £ million, and FTE employees of [n] (2024: [n]); Table [n] uses a total FTE of [n] (2024: [n]). In the 2024 report the same table gave [n] for 2024 on [n] tonnes and [n] tonnes per FTE.
[n] / [n] = [n] and [n] / [n] = [n], so both reported ratios divide by Organic revenue; on Group revenue the ratios are [n] and [n], a fall of [n]%. The 2024 report's [n] is [n] / [n], Group revenue. The 2025 per-FTE ratio [n] is [n] / [n] and the restated [n] is [n] / [n], whereas the 2024 report's [n] is [n] / [n].
The numerator and denominator then cover different groups of businesses, and the change reverses the direction of a measure the Board uses as a target. The report describes the restatement of emissions but not the change of denominators.
| Ratio | Reported | Inputs that reproduce it | On Group revenue / prior basis |
|---|---|---|---|
| tCO2e/£m revenue 2025 | [n] | [n] / [n] = [n] (Organic revenue) | [n] / [n] = [n] |
| tCO2e/£m revenue 2024 (restated) | [n] | [n] / [n] = [n] (Organic revenue) | [n] / [n] = [n] |
| tCO2e/£m revenue 2024 as first published | [n] | [n] / [n] = [n] (Group revenue) | basis of the 2024 report |
| Change in the ratio on Group revenue | +[n]% ([n] / [n] - 1) | [n] / [n] - 1 = -[n]% | direction reverses |
| tCO2e/FTEs 2025 | [n] | [n] / [n] = [n] | [n] / [n] = [n] |
| tCO2e/FTEs 2024 | [n] (2024 report: [n]) | [n] / [n] = [n] | [n] / [n] = [n] |
Management’s best defence, and our reply
The company could say Organic revenue strips out acquisitions and so gives a like-for-like intensity trend, and that the FTE count in Table [n] is the emissions consultant's figure for the entities in the carbon boundary. Both measures are voluntary normalisations and the absolute emissions are disclosed in full. However, the numerator is not Organic: it includes the 2024 acquisitions, including [name] [subsidiary]' emissions added by restatement, so the ratio mixes two boundaries; the 2024 report used Group revenue; and the ratio is itself one of the company's climate targets, whose calculation the law requires to be described. Nothing on the page says a different revenue or FTE figure is used.
The fix
- Compute tCO2e per £m on Group revenue (2025: [n]; 2024: [n]) and per FTE on one stated headcount, or state the change of denominator and re-present the comparative; describe both calculations next to the table.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The ratio is one of the company's climate-related targets | Document | Annual Report 2025, page 31 |
| 2 | Numerator: market-based Scope 1 and 2 tonnes | Document | Annual Report 2025, page 31 |
| 3 | Reported ratio per £m revenue | Document | Annual Report 2025, page 31 |
| 4 | Reported ratio per FTE | Document | Annual Report 2025, page 31 |
| 5 | The narrative presents the ratio as having worsened | Document | Annual Report 2025, page 31 |
| 6 | Organic revenue: [n] (2024: [n]) | Document | Annual Report 2025, page 18 |
| 7 | Group revenue: [n] (2024: [n]) | Document | Annual Report 2025, page 18 |
| 8 | FTE in the finance review | Document | Annual Report 2025, page 20 |
| 9 | Different FTE count used for emissions intensity | Document | Annual Report 2025, page 41 |
| 10 | 2024 report: 2024 ratio [n] | Document | Annual Report 2024, page 30 |
| 11 | 2024 report numerator: [n] tonnes | Document | Annual Report 2024, page 30 |
| 12 | 2024 report per-FTE ratio [n] | Document | Annual Report 2024, page 30 |
| 13 | 2024 Group revenue [n], the 2024 report's denominator | Document | Annual Report 2024, page 1 |
| 14 | 2024 FTE [n], the 2024 report's denominator | Document | Annual Report 2024, page 19 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [wording masked]
- What is missing
- a description of how tCO2e per £m revenue and tCO2e per FTE are calculated (which revenue figure and which employee count), and of the change from the Group revenue and finance-review FTE basis used in the 2024 report
- Pages looked at
- p.31 (Environment), p.32-39 (climate-related financial disclosures incl. Metrics and Targets on p.39), p.40 (emissions methodology), p.41 (SECR tables and restatement footnote), p.18-20 (finance review)
- Result
- '£m revenue', '£m of revenue' and 'tCO2e/FTE' hit only p.31 (the targets list, the narrative and the table, none of which names the revenue figure used); 'Organic revenue' hits p.2, [n] (highlights, executive reviews and the alternative performance measures note), none on a sustainability page; 'intensity' hits p.41 only (Table [n] title, per-FTE location-based metrics, no denominator explained); 'Normalised' hits p.4 and [n] / [n] (a subsidiary's data service and the auditor's normalised [product] contribution) and p.31 (the table heading); 'denominator' has no hits. The p.41 restatement footnote explains the restated 2024 emissions only.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.