4.03 The 2024 Chief Financial Officer's report gives statutory operating profit and net finance costs that differ from the income statement
UK Company C · an AIM-quoted scientific instruments group · Presentation point
In brief
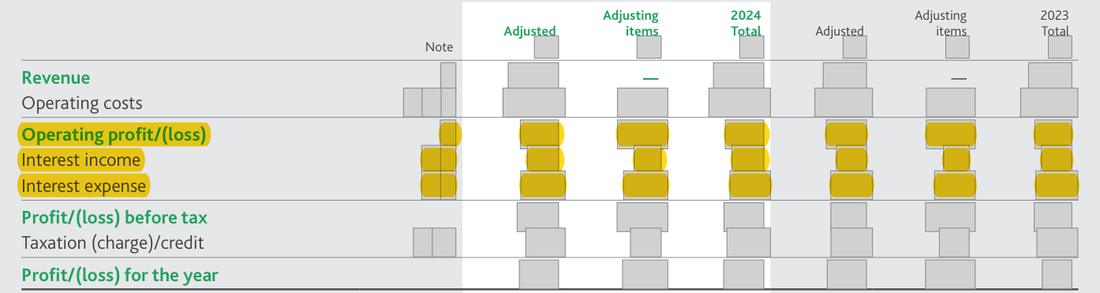
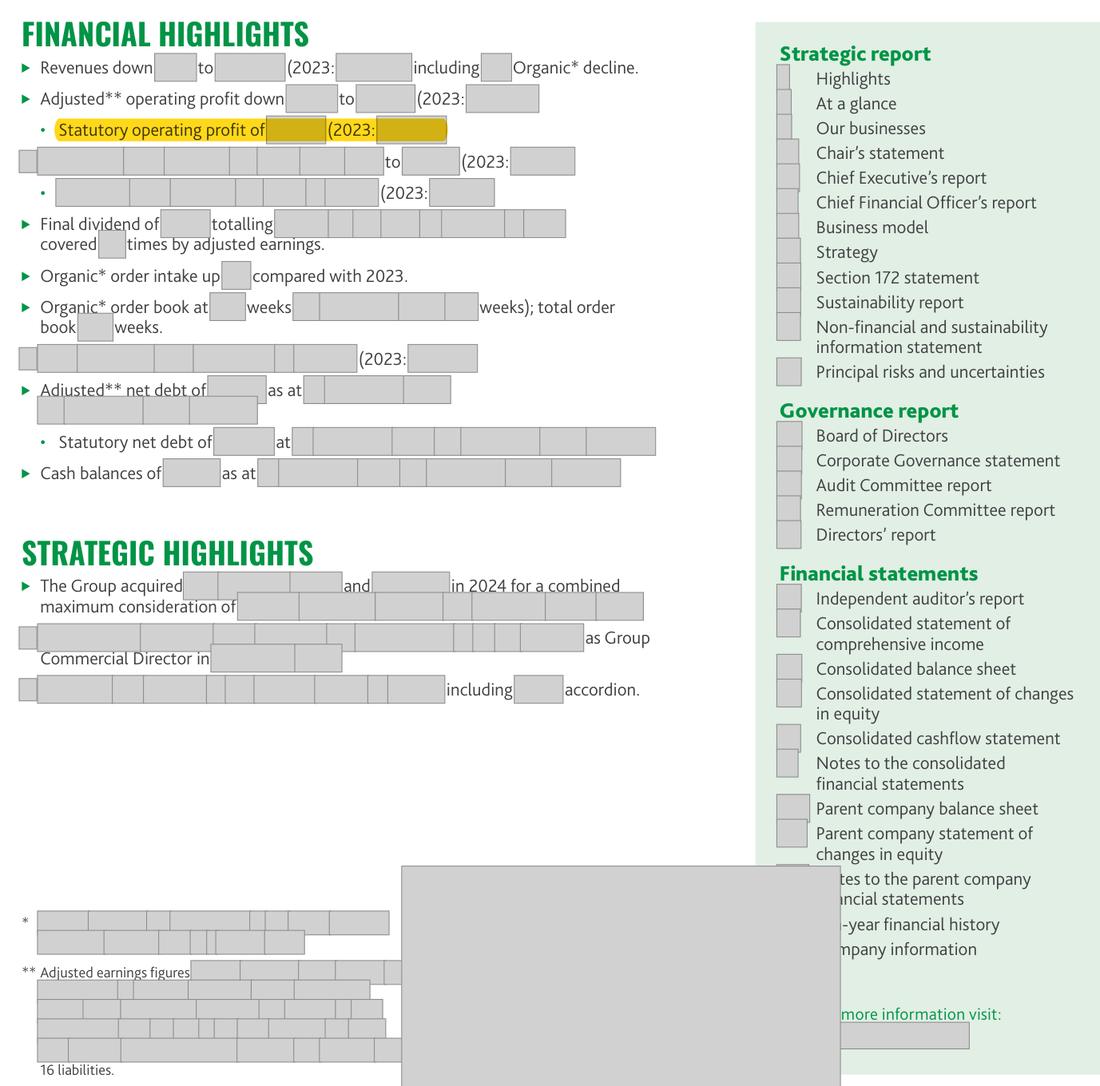
The Chief Financial Officer's report says statutory operating profit was [amount] and statutory net finance costs were [amount]. The audited income statement shows operating profit of [amount] and net finance costs of [amount] (interest expense [amount] less interest income [amount]). The two differences of [amount] offset, so profit before tax of [amount] agrees, but the highlights page and the income statement say [amount] while the review says [amount].
The evidence, as filed
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 18; Annual Report 2025, page 19. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows CFO report p.18: statutory operating profit [amount]; statutory net finance costs [amount]. Income statement p.67 and highlights p.1: operating profit [amount]; net interest [n] - [n] = [n]. | What the rule requires CFO report p.18: statutory operating profit [amount] and statutory net finance costs [amount], the amounts in the audited consolidated statement of comprehensive income. |
What we checked: CFO report p.18 against the consolidated statement of comprehensive income p.67, the highlights p.1 and the 2024 comparatives in the 2025 report p.19.
The rule
Companies Act 2006 s.414C(12)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The report must, where appropriate, include references to, and additional explanations of, amounts included in the company’s annual accounts.
Companies Act 2006 s.414C(3)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The review required is a balanced and comprehensive analysis of— (a) the development and performance of the company’s business during the financial year
Why it applies here: the CFO narrative appears to have been drafted on a split of adjusting items between operating costs and finance costs that differs from the audited statement (the statement puts [amount] of adjusting items in operating profit); the narrative is the only place in the report where [amount] appears.
Why it matters
A reader who ties the CFO report to the audited statement finds two statutory operating profit figures for 2024 in the same annual report; the slip does not change profit before tax, earnings per share or any audited amount.
Exposure
No penalty; a narrative inconsistency of this size would at most draw a comment in a Corporate Reporting Review.
Our workings
the CFO report states 'Statutory operating profit reduced to [amount]' and 'Statutory net finance costs were [amount]'. The consolidated statement of comprehensive income shows total operating profit of [amount], interest income of [amount] and interest expense of [amount]; the highlights also give statutory operating profit of [amount].
statutory net finance costs are [n] - [n] = [n]; the review's figures differ from the statement by [n] - [n] = [n] and [n] - [n] = [n], and the two differences offset, so both sets give profit before tax of [amount].
The 2025 report gives the 2024 comparatives as [amounts], so the audited figures were never in doubt; the point is the internal consistency of the 2024 strategic report, which s.414C(12) expects to refer to and explain amounts in the accounts.
| Line | CFO report | Income statement | Difference |
|---|---|---|---|
| Statutory operating profit | [n] | [n] | [n] - [n] = [n]; [n] / [n] = [n]% |
| Statutory net finance costs | [n] | [n] - [n] = [n] | [n] - [n] = [n] |
| Profit before tax | [n] - [n] = [n] | [n] - [n] = [n] | [n] / [n] = [n]% |
Management’s best defence, and our reply
The finance team could argue that the CFO report was drafted before the final allocation of adjusting items between operating costs and finance costs, that profit before tax of [amount] in the same sentence is right, and that the audited statement governs, so no reader is misled about the result. The auditor's report does not cover the strategic report figures beyond a consistency read. However, s.414C(12) asks the review to refer to amounts in the accounts, and the same report prints [amount] on p.1 and p.67 and [amount] on p.18 with an offsetting [amount] in finance costs, so the narrative bridge cannot be tied; the 2025 report's own 2024 comparatives ([amounts]) confirm which figures are right.
The fix
- Read 'Statutory operating profit reduced to [amount]' and 'Statutory net finance costs were [amount]' on p.18, and tie every statutory figure in the CFO report to the audited statement before approval.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The CFO report gives statutory operating profit of [amount] | Document | Annual Report 2024, page 18 |
| 2 | The CFO report gives statutory net finance costs of [amount] | Document | Annual Report 2024, page 18 |
| 3 | The audited income statement shows total operating profit of [amount] | Document | Annual Report 2024, page 67 |
| 4 | Total interest income [amount] | Document | Annual Report 2024, page 67 |
| 5 | Total interest expense [amount], so statutory net finance costs are [amount] | Document | Annual Report 2024, page 67 |
| 6 | The highlights page of the same report gives [amount] | Document | Annual Report 2024, page 1 |
| 7 | The 2025 report gives the 2024 comparative as [amount] | Document | Annual Report 2025, page 19 |
| 8 | The 2025 report gives the 2024 statutory net finance costs as [amount] | Document | Annual Report 2025, page 19 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.