4.02 The alternative performance measures note defines Adjusted earnings by four kinds of adjusting item, but note 4 also removes pension costs (2024) and a goodwill impairment and prior-year foreign taxes (2025)
UK Company C · an AIM-quoted scientific instruments group · Presentation point
In brief
Both reports' alternative performance measures note (note [n]) says Adjusted earnings, the basis of the headline adjusted earnings per share (EPS), [wording masked] year end. The adjusting-items note (note 4) removes more: in 2024 retirement benefit obligation costs of [amount] and pension net interest income of [amount], and in 2025 a goodwill impairment ([subsidiary], [amount], inside the [amount] 'amortisation and impairment' line) and [amount] of prior-year foreign taxes. The Chief Financial Officer's report defines the measure by reference to note 4, so the amounts are traceable, but the note [n] definition is narrower than the measure reported.
The evidence, as filed
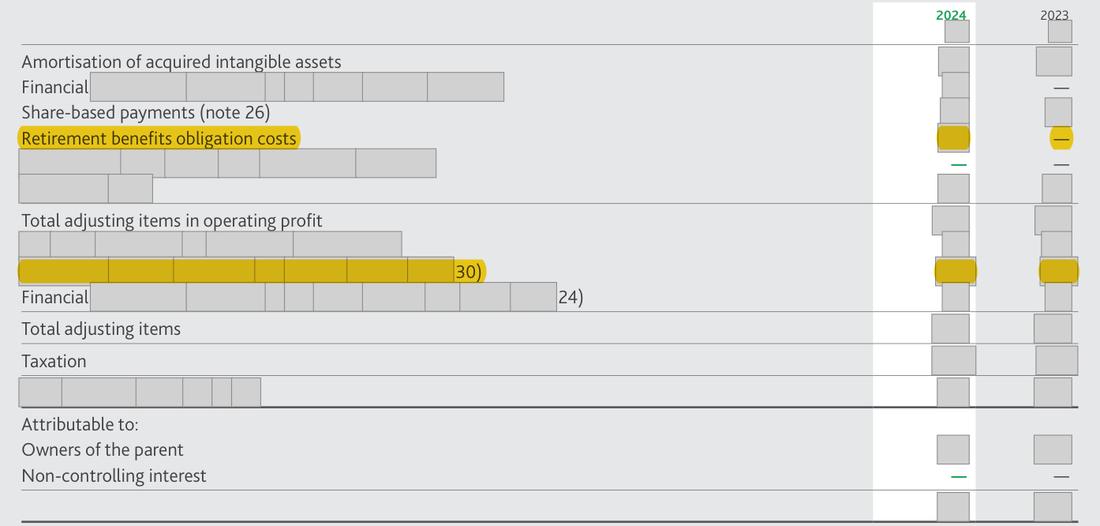
Further pages withheld to protect the company’s identity (five): Annual Report 2024, page 99; Annual Report 2025, page 99; Annual Report 2025, page 77; Annual Report 2025, page 20; Annual Report 2025, page 18. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Definition (both years): Adjusted earnings exclude '[wording masked] year'. Note 4 also adjusts retirement benefit obligation costs [amount] and net interest income [amount] in 2024, and goodwill impairment [amount] and prior-year foreign taxes [amount] in 2025. | What the rule requires A definition that names every category the adjusting-items note removes (impairment of goodwill and acquired intangibles, pension costs and interest, one-off prior-year taxes, changes in acquisition payables), or that states Note 4 is the complete list. |
What we checked: Definition in Note 34 of both reports (2024 report p.99; 2025 report p.99) against Note 4 adjusting items of both reports (2024 report p.77; 2025 report p.77) and the 2025 goodwill impairment (2025 report p.20)
The rule
ESMA Guidelines on Alternative Performance Measures, para 20 (good practice for an AIM company)
Version relied on: ESMA Guidelines on Alternative Performance Measures, ESMA/2015/1415, published October 2015, applying from July 2016; the FCA expects UK issuers to continue to apply them after EU exit
Issuers or persons responsible for the prospectus should define the APMs used and their components as well as the basis of calculation adopted
Why it applies here: impairment, pension costs and interest, and a prior-year tax payment are not amortisation, acquisition costs, share-based payments or hedging, so in both years the note [n] definition describes a narrower measure than the one reported, while the strategic report's definition by reference to note 4 describes it fully; the report therefore carries two definitions that do not agree. [wording masked] may fairly be read as acquisition-related and is not counted.
Why it matters
A reader who relies on the definition understates what is removed from statutory profit to reach adjusted EPS; in 2025 a goodwill impairment and a one-off tax payment are excluded under a definition that does not mention either.
Exposure
A Financial Reporting Council (FRC) Corporate Reporting Review question on APM definitions, a theme of its reviews, answered by a corrected definition in the next report; no fine applies.
Our workings
note [n] of both reports says Adjusted earnings '[wording masked] year', and refers to note 4 for a summary. Note 4 of the 2024 report adjusts retirement benefit obligation costs of [amount] and retirement benefit net interest income of [amount]; note 4 of the 2025 report adjusts '[wording masked] goodwill' of [amount], which includes the [amount] [subsidiary] goodwill impairment, a '[wording masked]' of [amount] and a '[wording masked]' of [amount]. The Chief Financial Officer's report (2025 report p.18) describes Adjusted earnings as excluding '[wording masked] 4)', and the accounting policy treats as adjusting the items that by [wording masked].
items outside the four named kinds are [n] + ([n]) = [n] net in 2024 and [n] + [n] = [n] in 2025.
The European Securities and Markets Authority (ESMA) guidelines ask for each APM to be defined with its components; they are addressed to regulated-market issuers, so for an AIM company they are the benchmark of good practice rather than a rule, but the inaccuracy of a definition the company chose to publish in its audited notes stands on its own.
| Year | Adjusting items outside the four named kinds (£m) |
|---|---|
| 2024 | retirement benefit costs [n] + pension net interest ([n]) = [n] |
| 2025 | [subsidiary] goodwill impairment [n] + prior-year foreign taxes [n] = [n] |
Management’s best defence, and our reply
The company may say the four kinds in note [n] are the principal categories, that the same note sends the reader to note 4 for the full list and to note [n] for the bridge to statutory EPS, that the Chief Financial Officer's report defines Adjusted earnings as excluding the adjusting items disclosed in note 4, and that the accounting policy admits any item the Directors consider separate by size or nature, so no reader is misled about the amounts; it may add that the ESMA guidelines do not bind an AIM company. The answer: this explains why the amounts are traceable, and is why the point is kept as a low-severity inconsistency rather than an error in the measure, but note [n] is the company's own definition in its audited notes and it names four kinds of item, while note 4 removes items of other kinds in both years - pension costs and interest in 2024, a goodwill impairment and a prior-year tax payment in 2025; the acquisition-related items are already left out of the count.
The fix
- Reword the definition, e.g. 'Adjusted earnings exclude the adjusting items listed in note 4: [wording masked] goodwill, acquisition-related costs and changes in acquisition payables, share-based payments, [wording masked] year end, pension scheme costs and interest, and other items the Board considers non-recurring.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2024 report: the definition names four kinds of adjusting item | Document | Annual Report 2024, page 99 |
| 2 | 2024 Note 4: retirement benefit obligation costs of [amount] adjusted | Document | Annual Report 2024, page 77 |
| 3 | 2024 Note 4: pension net interest income of [amount] adjusted | Document | Annual Report 2024, page 77 |
| 4 | 2025 report: the same four-item definition | Document | Annual Report 2025, page 99 |
| 5 | 2025 Note 4: amortisation and impairment, including goodwill impairment, of [amount] adjusted | Document | Annual Report 2025, page 77 |
| 6 | 2025 Note 4: reversal of an acquisition payable of [amount] adjusted | Document | Annual Report 2025, page 77 |
| 7 | 2025 Note 4: prior-year foreign taxes of [amount] adjusted | Document | Annual Report 2025, page 77 |
| 8 | 2025: goodwill impairment of [amount] ([subsidiary]), part of the [amount] line | Document | Annual Report 2025, page 20 |
| 9 | 2025 report: the Chief Financial Officer's report defines Adjusted earnings by reference to the full note 4 list | Document | Annual Report 2025, page 18 |
| 10 | The 2025 note keeps the four-item definition | Document | Annual Report 2025, page 99 |
| 11 | A new 2025 adjusting item the definition does not name | Document | Annual Report 2025, page 77 |
| 12 | The earn-out reversal credited in adjusting items | Document | Annual Report 2025, page 77 |
| 13 | Impairment is excluded with amortisation, though the definition names only amortisation | Document | Annual Report 2025, page 77 |
| 14 | Size of the 2025 impairment within the adjusting items | Document | Annual Report 2025, page 20 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.