6.14 Drafting slips in Notes 1.4 to 2.8: a rolled-forward tax-rate date, wrong words, a wrong note reference, stray markers and labels
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
Eight slips in the notes change no audited amount but should be corrected: the UK tax-rate date is moved on a year from the correct date given last year; 'discounting operations' is printed for discontinued operations; the [investee] loss is called a gain; the goodwill estimate row points to the wrong note; an asterisk has no footnote; a footnote marker is missing from the intangible assets impairment line; share numbers are labelled in pounds; and a prior-year loss is printed without brackets.
The evidence, as filed
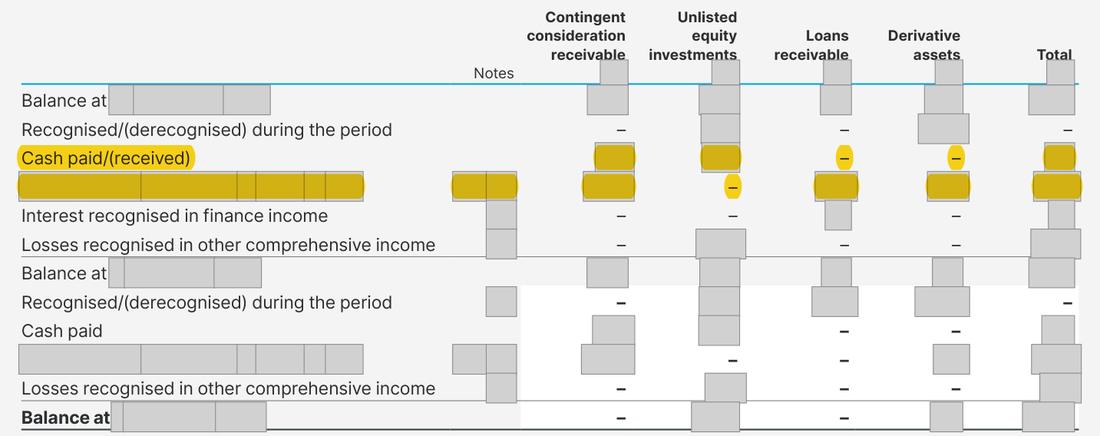
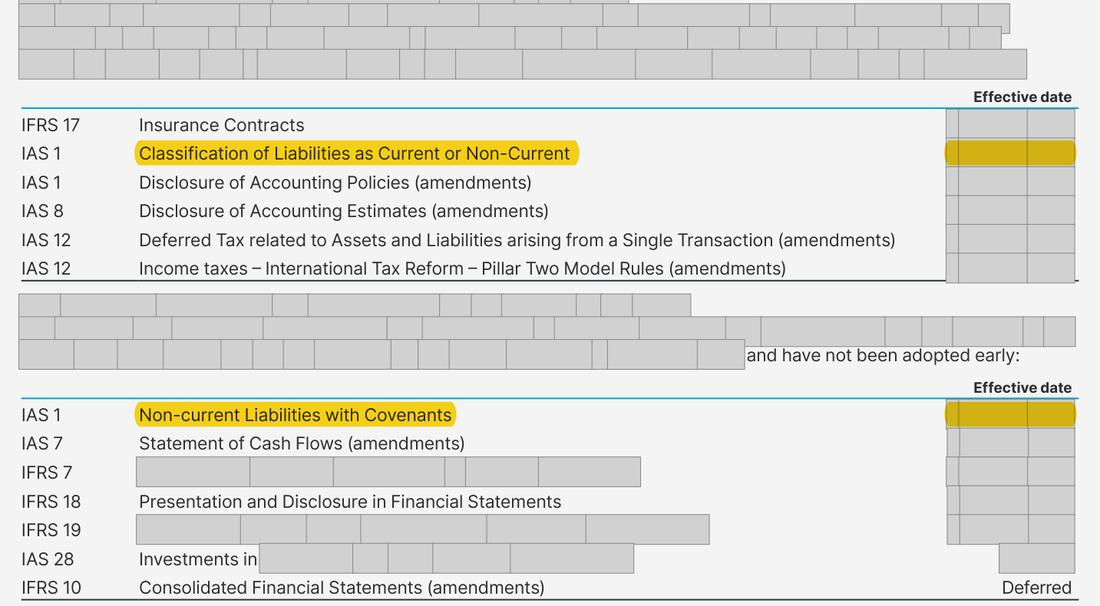
Further pages withheld to protect the company’s identity (13): Annual Report 2025, page 207; Annual Report 2024, page 186; Annual Report 2025, page 204; Annual Report 2025, page 194; Annual Report 2024, page 183; Annual Report 2025, page 200; Annual Report 2024, page 182; Annual Report 2025, page 208; Annual Report 2025, page 189; Annual Report 2024, page 200; Annual Report 2024, page 187; Annual Report 2024, page 217; Annual Report 2024, page 189. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Deferred tax note: 25% rate 'with effect from [date]'. Tax on adjusting items: 'discounting operations'; 'accounting gain on disposal of [name]'. Estimates table: goodwill row text cites Note 3.1, the Notes column of the same row cites the property, plant and equipment note. Going concern note: 'external gross debt*' with no footnote. Operating costs: footnote 1 explains the goodwill charge within the intangible assets impairment line, but its marker appears only on the property, plant and equipment line. EPS share table headed '£m'. EPS earnings table: 2024 discontinued result shown as [n] although it is a loss. | What the rule requires 'with effect from [date]' (as in the 2024 report); 'discontinued operations'; 'the loss on deconsolidation of [name]'; Notes column [n]; delete the asterisk or add the APM marker and footnote; add the marker to the impairment of intangible assets line as well; headed 'm' (millions of shares); 2024 discontinued amount shown as ([n]). |
Why it matters
No amount is affected; the slips reduce the polish of the audited notes and one (the tax-rate date) states a fact wrongly.
Exposure
No regulatory consequence.
Our workings
Each slip is shown on its page in the evidence. The UK main corporation tax rate became 25% from [date], and the 2024 report said so; this year's note moves the date to 2024. The 2024 discontinued line in the EPS earnings table is a loss (the 2024 continuing loss only follows from the total if the amount is deducted as a loss), so it needs brackets like the per-share line beneath it. None of the slips changes a reported amount.
Management’s best defence, and our reply
Management would say these are typographical points that no reader would act on, and that the figures they sit beside are all correct. They would also note that the auditor's materiality is far above any of them. That is accepted, which is why they are listed only as drafting slips; however, they sit in the audited notes and are cheap to correct.
The fix
- Correct each item as set out under 'should be' and add a final proof-read of dates rolled forward from the prior year.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Tax-rate date given as [date]; the 25% rate took effect on [date] | Document | Annual Report 2025, page 207 |
| 2 | The 2024 report gave the correct date | Document | Annual Report 2024, page 186 |
| 3 | 'discounting operations' printed for discontinued operations | Document | Annual Report 2025, page 204 |
| 4 | The [name] result is a loss on deconsolidation (item L), not a gain on disposal | Document | Annual Report 2025, page 204 |
| 5 | The text cites Note 3.1 (goodwill) while the Notes column of the same row reads [n] | Document | Annual Report 2025, page 194 |
| 6 | The asterisk has no footnote on the page | Document | Annual Report 2025, page 194 |
| 7 | Footnote 1 describes the goodwill charge but its marker appears only on the property, plant and equipment impairment line | Document | Annual Report 2025, page 200 |
| 8 | The share-number table that follows is headed '£m' | Document | Annual Report 2025, page 208 |
| 9 | The 2024 discontinued amount is a loss but is printed without brackets | Document | Annual Report 2025, page 208 |
| 10 | Listed among amendments adopted for the period beginning [date], with an effective date of [date] | Document | Annual Report 2024, page 172 |
| 11 | The companion IAS 1 amendment is listed as not yet effective, from [date] | Document | Annual Report 2024, page 172 |
| 12 | The 2025 report gives [date] and adopts the amendment in 2025 | Document | Annual Report 2025, page 189 |
| 13 | Impairments of [n] make [n]; the [n] is the line total including [n] of other costs | Document | Annual Report 2024, page 183 |
| 14 | The other two components of the 2023 [format] review line | Document | Annual Report 2024, page 183 |
| 15 | The 2023 [name] movement is read as an increase and 2023 cash as [n] | Document | Annual Report 2024, page 182 |
| 16 | The 2023 [partner] loss was [n] | Document | Annual Report 2024, page 182 |
| 17 | 2023 contingent consideration loss of [n] = [partner] [n] plus a [name] fall of [n] | Document | Annual Report 2024, page 214 |
| 18 | 2023 [name] cash received [n] | Document | Annual Report 2024, page 214 |
| 19 | Note 3.6 gives 2023 cash received as [n] | Document | Annual Report 2024, page 200 |
| 20 | 'Discontinuing' printed for discontinued operations (also in the per-share block) | Document | Annual Report 2024, page 187 |
| 21 | The table that follows is the basic (unadjusted) loss per share; the adjusted table comes later | Document | Annual Report 2024, page 187 |
| 22 | [amount] is the weighted average used in the table, not the number [wording masked] | Document | Annual Report 2024, page 187 |
| 23 | Ordinary shares in issue at [date]: [amount] | Document | Annual Report 2024, page 217 |
| 24 | Percentage printed '[n].%' ([n] of [n] is [n]%) | Document | Annual Report 2024, page 189 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.