6.15 Drafting slips in the financial instruments, share scheme and related undertakings notes
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
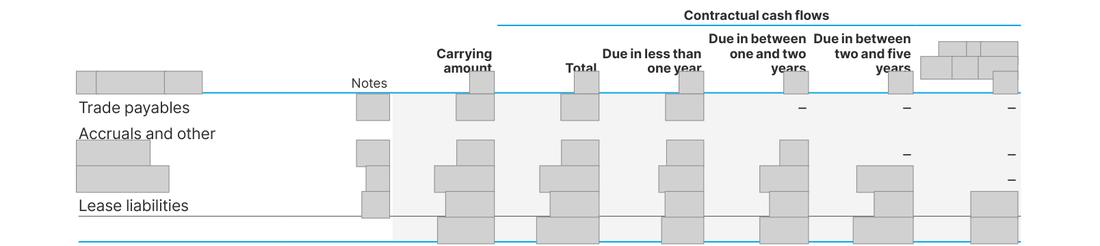
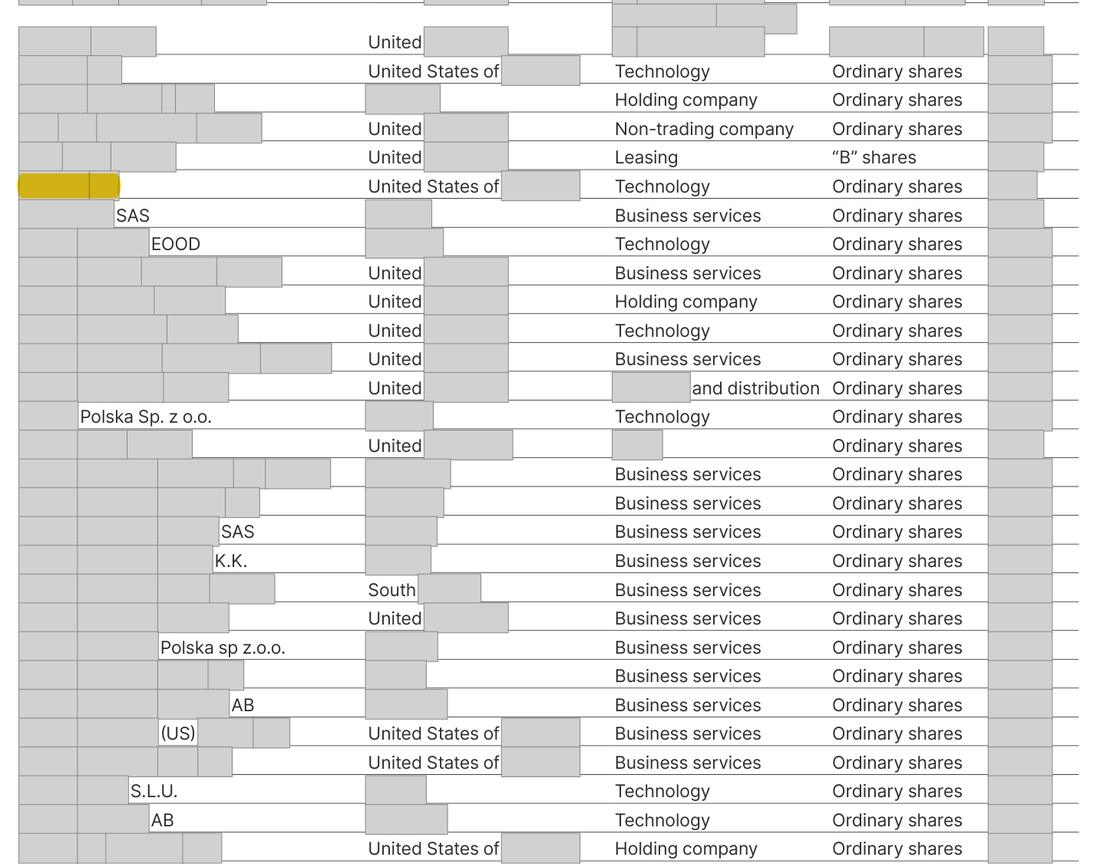
Four drafting slips: a footnote marker against Borrowings in the 2025 liquidity table that leads to no footnote; a bracket opened before a cross-reference to the Directors' Remuneration Report that is never closed; 'six month's service' where the scheme paragraph two pages earlier reads 'six months' service'; and one related undertaking whose holding is printed as 100% where every other row prints one decimal place. The 2024 notes carry slips of the same kind (both years).
The evidence, as filed
Further pages withheld to protect the company’s identity (nine): Annual Report 2024, page 218; Annual Report 2025, page 242; Annual Report 2025, page 249; Annual Report 2024, page 221; Annual Report 2025, page 250; Annual Report 2024, page 222; Annual Report 2025, page 248; Annual Report 2024, page 225; Annual Report 2024, page 216. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Liquidity table, [date]: 'Borrowings2' with only footnote 1 printed below the tables. Annual Incentive Plan paragraph: '([wording masked] pages 133 to 158.' with no closing bracket. Restricted Share Plan: 'six month's service'. Related undertakings: [subsidiary] Inc '100%'. | What the rule requires Either the footnote text for marker 2 (the 2024 report explained that amounts due within one year are mainly interest) or no marker; a closing bracket; 'six months' service'; '100%'. |
Why it matters
None for the figures; a reader following the marker finds no explanation, and the slips detract from the finish of audited notes.
Exposure
Drafting only; no requirement turns on these slips.
Our workings
each slip is printed as quoted in the evidence rows. The 2024 report carried a footnote 2 against Borrowings explaining that the amounts due within one year were mainly interest; the 2025 table keeps the marker but the footnote text is not printed under either year's table, where only footnote 1 (employee cost accruals) appears.
Management’s best defence, and our reply
Management would say these are typographical points that change no figure and that no reader would decide differently because of them. They would also say the footnote was removed deliberately because the 2025 amount due within one year includes the repayment of the 2025 convertible bonds, not only interest. That answer explains dropping the text but not keeping the marker, so the tidy-up still stands.
The fix
- Restore footnote 2 (or delete the marker), close the bracket, change to 'six months' service' and print '100%'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Marker 2 against Borrowings in the 2025 liquidity table | Document | Annual Report 2025, page 241 |
| 2 | The only footnote printed under the two liquidity tables is footnote 1 | Document | Annual Report 2025, page 242 |
| 3 | The bracket opened with '(refer to the' is not closed | Document | Annual Report 2025, page 249 |
| 4 | Restricted Share Plan paragraph: 'six month's service' | Document | Annual Report 2025, page 250 |
| 5 | Share Incentive Plan paragraph uses the correct 'six months' service' | Document | Annual Report 2025, page 248 |
| 6 | [subsidiary] Inc row: holding printed as 100% (others 100%) | Document | Annual Report 2025, page 254 |
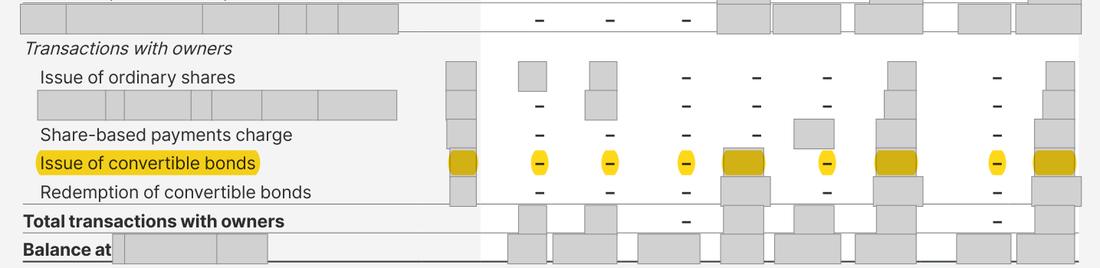
| 7 | Other reserves note: the Total column prints nil against the [amount] issue of convertible bonds | Document | Annual Report 2024, page 218 |
| 8 | Other reserves note: the Total column prints nil against the [amount] partial redemption | Document | Annual Report 2024, page 218 |
| 9 | The statement of changes in equity carries the [amount] in the other reserves column, so the note's Total column should too | Document | Annual Report 2024, page 170 |
| 10 | [name] closing weighted average exercise price printed with a comma ('4,[n]'); the 2025 report prints [n] | Document | Annual Report 2024, page 221 |
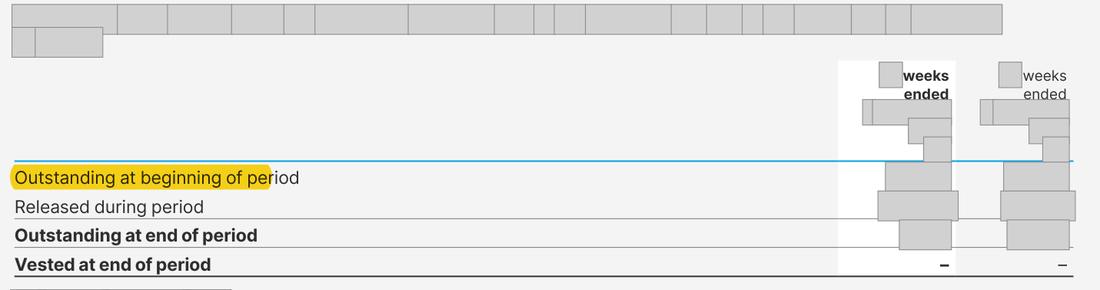
| 11 | Value Creation Plan: nil banked in 2023, then [n] banked 'during the prior period' | Document | Annual Report 2024, page 222 |
| 12 | Long-Term Operating Plan table of share numbers headed '£m' (as are the bonus plan, consultant option and deferred consideration share tables) | Document | Annual Report 2024, page 224 |
| 13 | The bonus plan for the 2024 year is called the '2023 AIP'; the 2025 report names the plan for its own year | Document | Annual Report 2024, page 224 |
| 14 | A count of options given in pounds | Document | Annual Report 2024, page 224 |
| 15 | 'six month's service' in the Restricted Share Plan paragraph, as in the 2025 report | Document | Annual Report 2024, page 225 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- The [wording masked]
- What is missing
- the footnote 2 text that the Borrowings marker refers to
- Pages looked at
- p.241-242
- Result
- none of the terms appears anywhere in the 2025 report
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.