6.08 Highlights, Business in Focus and Financial Review: typing, label and wording slips
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
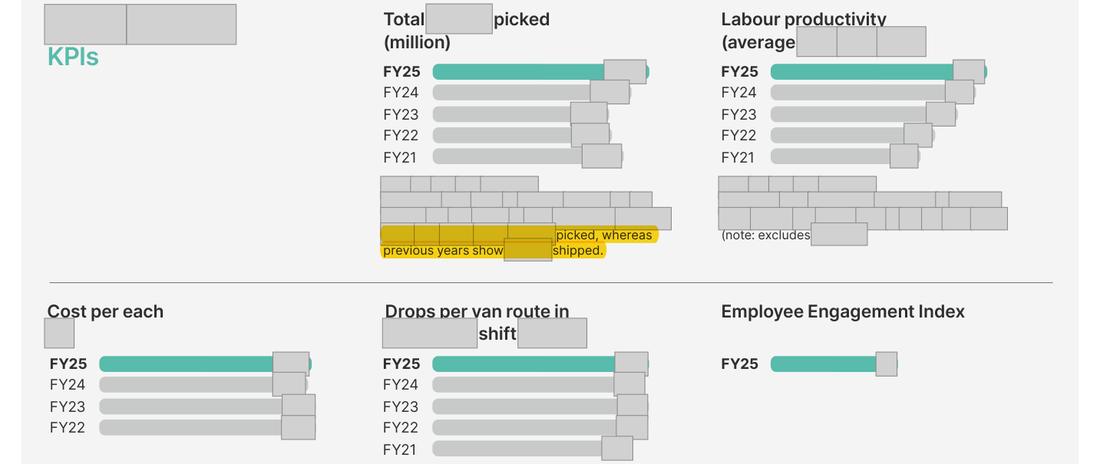
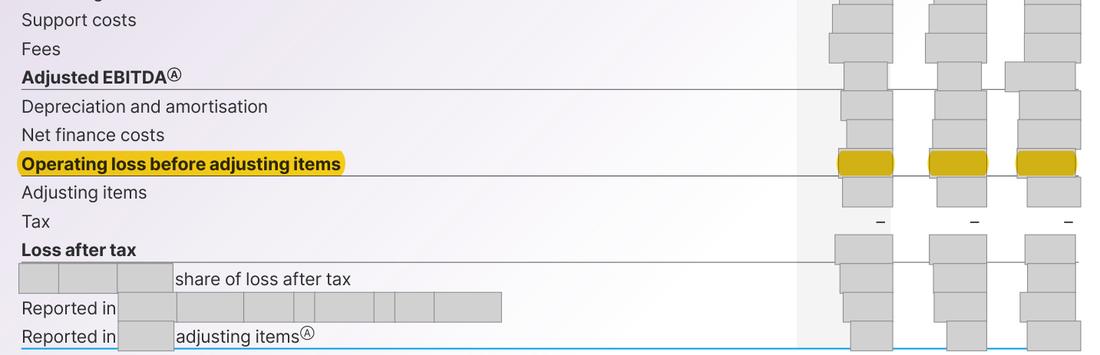
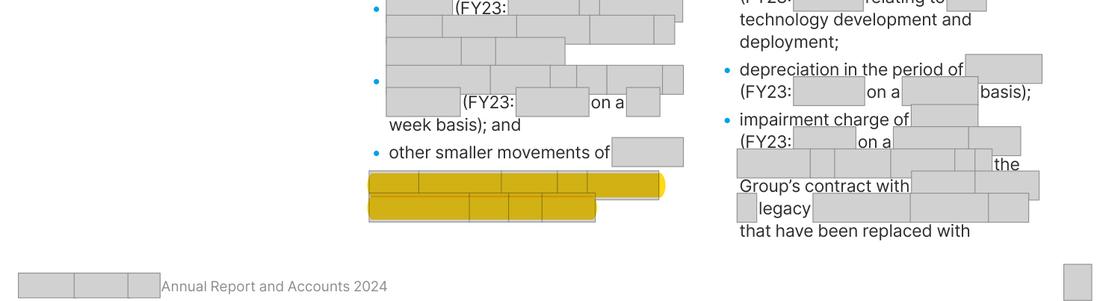
The front section and Financial Review contain a set of slips that change no audited figure: two typing errors and a repeated word, one closed [customer] site given two different names, a footnote that limits a delivery measure to [former subsidiary] while the sentence applies it to all partners, a relabelled 2024 volume figure, one percentage given two ways, a subtotal label that does not match the lines above it, and a change described with the opposite verb.
The evidence, as filed
Further pages withheld to protect the company’s identity (13): Annual Report 2025, page 1; Annual Report 2024, page 23; Annual Report 2025, page 7; Annual Report 2024, page 28; Annual Report 2025, page 16; Annual Report 2024, page 42; Annual Report 2025, page 14; Annual Report 2024, page 36; Annual Report 2025, page 15; Annual Report 2025, page 25; Annual Report 2025, page 31; Annual Report 2025, page 37; Annual Report 2025, page 45. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.1 '[name]' and 'most advance site'; p.7 'particularly particularly'; p.7 and p.16 'in FY27 by around [amount] in FY27'; p.1 footnote 4 '[city]' for the [customer] site called '[name] (MD)' on p.14; p.15 DP8 'across our partners' with a footnote saying 'for [former subsidiary] only'; p.17 2024 [units] now called 'picked' where the 2024 report called the same series 'shipped'; support cost reduction 'a decrease of [n]%' on p.25 but 'a reduction of 3%' on p.31; p.35 'Operating loss before adjusting items' struck after net finance costs; p.37 a loss that 'decreased' explained by 'drivers for the increase'; p.45 '[amount]' without 'm'. | What the rule requires '[index]'; 'most advanced site'; one 'particularly'; 'by around [amount] in FY27'; one name for the [name] ([city] area) [facility] throughout; the DP8 footnote attached only to [former subsidiary] figures (or the international DP8 defined); one label for the 2024 [units] figure with the basis stated; one percentage for the support cost reduction; 'Loss before adjusting items and tax' for the [former subsidiary] subtotal; 'drivers for the decrease'; '[amount]'. |
Why it matters
Small slips in the front section reduce confidence in the care taken over the narrative; none changes a reported amount.
Exposure
No regulatory consequence; correct in the next report.
Our workings
Each item is a typing, labelling or wording slip in voluntary narrative or KPI presentation. None changes an amount in the financial statements. They are grouped here so they can be corrected in one pass.
Management’s best defence, and our reply
Management would say these are proof-reading slips in voluntary narrative, that the intended meaning is clear from context and that the audited figures are unaffected. That is right, and it is why they are drafting points only; they still read as errors and are simple to correct.
The fix
- Correct each item as listed in the should-be column in the next Annual Report.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | '[name]' should read '[index]' | Document | Annual Report 2025, page 1 |
| 2 | 'most advance site' should read 'most advanced site' | Document | Annual Report 2025, page 1 |
| 3 | The word 'particularly' is repeated | Document | Annual Report 2025, page 7 |
| 4 | 'in FY27' appears twice in the cost-reduction sentence | Document | Annual Report 2025, page 7 |
| 5 | The same doubled 'in FY27' is repeated in Business in Focus | Document | Annual Report 2025, page 16 |
| 6 | Highlights footnote 4 names the closed [state] site '[city]' | Document | Annual Report 2025, page 1 |
| 7 | Business in Focus names the same [state] site '[name] (MD)' | Document | Annual Report 2025, page 14 |
| 8 | The DP8 figure is given for all partners | Document | Annual Report 2025, page 15 |
| 9 | The footnote attached to that figure limits DP8 to [former subsidiary] | Document | Annual Report 2025, page 15 |
| 10 | The 2024 [units] figure is now described as [units] picked | Document | Annual Report 2025, page 17 |
| 11 | The 2024 report labelled the same 2024 figure as [units] shipped | Document | Annual Report 2024, page 23 |
| 12 | The support cost reduction is given as [n]% here | Document | Annual Report 2025, page 25 |
| 13 | The same reduction is given as 3% on p.31 | Document | Annual Report 2025, page 31 |
| 14 | The [former subsidiary] subtotal is struck after net finance costs but labelled an operating loss | Document | Annual Report 2025, page 35 |
| 15 | A loss that decreased is explained by 'drivers for the increase' | Document | Annual Report 2025, page 37 |
| 16 | The 2024 amount lacks its unit | Document | Annual Report 2025, page 45 |
| 17 | [former subsidiary] is listed among the joint ventures under [wording masked] | Document | Annual Report 2024, page 28 |
| 18 | [former subsidiary] was controlled and consolidated throughout 2024, so it was not a joint venture in that year's accounts | Document | Annual Report 2024, page 42 |
| 19 | [segment] support costs rose [n]%, but the sentence calls the rise lower than revenue growth | Document | Annual Report 2024, page 36 |
| 20 | [segment] revenue grew [n]%, less than the [n]% rise in support costs | Document | Annual Report 2024, page 36 |
| 21 | Intangible assets are amortised; the same page calls their charge an amortisation charge | Document | Annual Report 2024, page 41 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.