3.08 The finance cost explanation cites [amount] 'redeemed during the period', a figure the listed redemptions do not give
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
In explaining the [amount] rise in finance costs, the Financial Review contrasts the new debt with notes and convertible bonds 'partially redeemed of [amount] in the prior period and [amount] redeemed during the period'. The same page lists redemptions of [amount] of convertible bonds and [amount] of notes in the year, and the liquidity section gives [amounts] tendered plus [amount] repaid at par. The [amount] for 2024 is the carrying amount derecognised, and on that basis 2025 would be [amount]. No basis in the report gives [amount].
The evidence, as filed
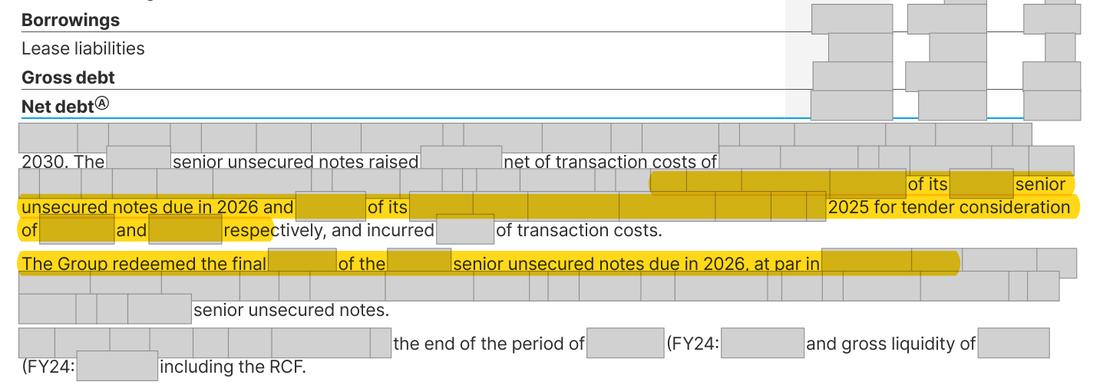
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 26; Annual Report 2024, page 29. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.26: '[amount] in the prior period and [amount] redeemed during the period'; the same page lists redemptions of [amounts]; p.43 lists [amounts] tendered and [amount] repaid at par; p.26 gives [amount] derecognised. | What the rule requires The amount redeemed in the year stated on the same basis as the 2024 figure (carrying amount derecognised, [amount]) or as the principal redeemed, with the basis named, so that it agrees with the redemptions listed on p.26 and p.43. |
The rule
Companies Act 2006, section 414C(12)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The report must, where appropriate, include references to, and additional explanations of, amounts included in the company’s annual accounts.
Why it applies here: none of these, alone or combined, gives [amount].
Why it matters
A reader cannot tie the explanation of the higher finance costs to the refinancing figures on the same page and on p.43.
Exposure
No regulatory consequence expected for a narrative figure; a correction in the next report.
Our workings
the finance cost paragraph on p.26 attributes the [amount] increase to the new notes, 'relative to' debt 'partially redeemed of [amount] in the prior period and [amount] redeemed during the period'. The next paragraph on the same page lists the year's redemptions as [amount] [wording masked] remaining [amount] of the notes, and the borrowings bridge on the same page gives [amount] derecognised. The liquidity section on p.43 gives [amounts] redeemed by tender, for consideration of [amounts], and [amount] repaid at par. The 2024 report gave [amount] as the amount 'derecognised on partial redemption'.
principal redeemed is [n] + [n] = [n] on p.26 and [n] + [n] + [n] = [n] on p.43; the tendered principal is [n] + [n] = [n]; the tender consideration is [n] + [n] = [n]; the carrying amount derecognised, the basis of the 2024 figure, is [amount].
The company's own basis for the comparative gives [amount], so the figure looks like a slip; it may instead be a weighted or part-year amount that the text does not explain.
| Basis | Computation | Result (£m) |
|---|---|---|
| Principal redeemed, p.26 | [n] + [n] = [n] | [n] |
| Principal redeemed, p.43 | [n] + [n] + [n] = [n] | [n] |
| Principal tendered, p.43 | [n] + [n] = [n] | [n] |
| Tender consideration, p.43 | [n] + [n] = [n] | [n] |
| Carrying amount derecognised (basis of the 2024 [amount]) | as stated, p.26 | [n] |
| Figure in the text | as stated, p.26 | [n] |
Management’s best defence, and our reply
The finance team may say the [amount] is the principal that stopped bearing interest at the earlier coupons during the year, measured on a time-weighted or part-period basis, and that the sentence is there to show the direction of the change rather than to restate the redemption totals given on p.43. They would add that the finance cost table on p.43 shows the interest charge by instrument, so a reader can see the effect of each redemption. However, the sentence calls the amount 'redeemed during the period', the 2024 comparative in the same sentence is the carrying amount derecognised, and on that basis the 2025 figure is [amount]; no basis is stated for a different figure. The answer turns on information only the company holds, so the point is put as a question.
The fix
- Replace '[amount] redeemed during the period' with '[amount] derecognised during the period' (the basis used for the 2024 figure), or name the basis of [amount].
Question for the company
What does the [amount] 'redeemed during the period' in the finance cost explanation on p.26 represent, and how does it reconcile with the [amount] derecognised and the [amount] of principal redeemed in the year (p.26 and p.43)?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The paragraph explains the [amount] rise in finance costs | Document | Annual Report 2025, page 26 |
| 2 | The explanation gives [amount] as the amount redeemed in the year | Document | Annual Report 2025, page 26 |
| 3 | The next paragraph lists [amounts] redeemed in the year | Document | Annual Report 2025, page 26 |
| 4 | The carrying amount derecognised in the year is [amount] | Document | Annual Report 2025, page 26 |
| 5 | The liquidity section gives the tendered principal and the consideration paid | Document | Annual Report 2025, page 43 |
| 6 | A further [amount] was repaid at par in the year | Document | Annual Report 2025, page 43 |
| 7 | The 2024 report gave [amount] as the carrying amount derecognised, the basis of the comparative | Document | Annual Report 2024, page 29 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.