1.28 Non-current assets by geography leave out goodwill, which IFRS 8 does not list among the assets that may be excluded
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
Note 2.2 gives non-current assets by geography '[wording masked]', totalling [n]. IFRS 8 allows only financial instruments, deferred tax assets, post-employment benefit assets and insurance rights to be left out. Goodwill of [n] is excluded with no statement that the information is unavailable. The 2024 report did the same.
The evidence, as filed
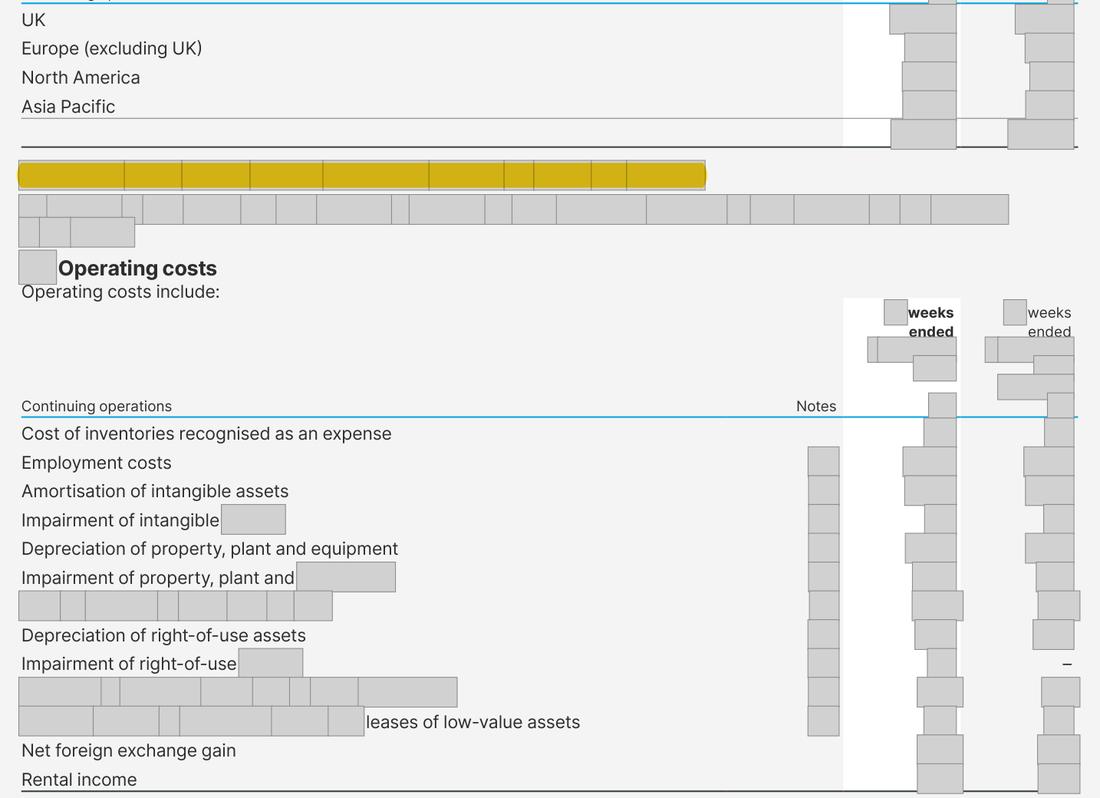
Annual Report 2024, page 179 · Prior year: The 2024 report also excluded goodwill from its non-current assets by geography.
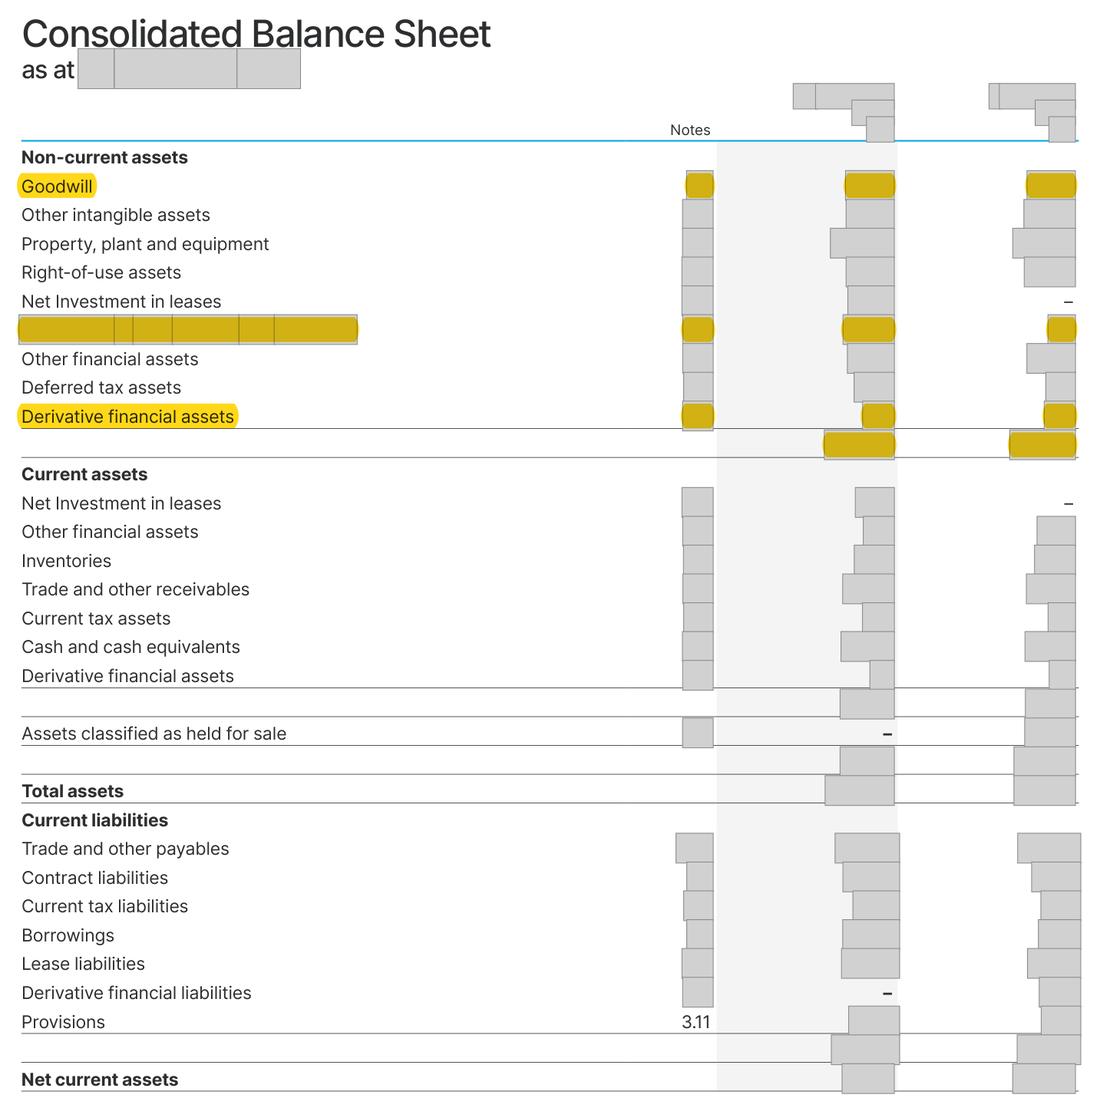
Further pages withheld to protect the company’s identity (one): Annual Report 2025, page 199. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.199: '[wording masked]', total [n]. Balance sheet goodwill [n]. | What the rule requires Goodwill included in the geographical analysis (allocated to the countries of the cash-generating units that carry it), or a statement that the information is not available and the cost to develop it would be excessive. |
The rule
IFRS 8 Operating Segments, paragraph 33(b)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Non-current assets (other than financial instruments, deferred tax, post-employment benefit and insurance assets) must be analysed between the home country and foreign countries, unless the information is unavailable and too costly to develop, in which case that is stated.
Why it applies here: goodwill is not one of the permitted exclusions and no unavailability statement is given.
Why it matters
North American non-current assets in particular ([n]) are shown without the goodwill that arose on the North American acquisitions, so the geographical spread of the Group's long-term assets is understated outside the UK.
Exposure
No regulatory consequence expected while the point is a question; an explanation or an amended heading in the next report.
Our workings
the geography table in Note 2.2 totals [n] and its heading excludes goodwill; the balance sheet carries goodwill of [n] and an [wording masked] [n].
balance sheet non-current assets of [n] less goodwill, other financial assets, deferred tax assets, derivatives, net investment in leases and the [wording masked] gives exactly [n], so both goodwill and the equity-accounted investment are outside the table. Law: IFRS 8 paragraph 33(b) requires non-current assets other than financial instruments, deferred tax assets, post-employment benefit assets and rights under insurance contracts, unless the information is not available and the cost to develop it would be excessive, in which case that fact is disclosed.
The goodwill arose on North American and other overseas acquisitions and is tested at segment level, so its location may be arguable, which is why this is put as a question. The equity-accounted investment is not raised: an investment in an associate is an equity instrument of another entity and so meets the definition of a financial instrument, which makes its exclusion defensible, but the heading should say so.
| Measure | Computation | Result |
|---|---|---|
| Balance sheet non-current assets to the geography table | [n] - [n] - [n] - [n] - [n] - [n] - [n] = [n] | agrees to the table total |
| Goodwill as a share of the table | [n] / [n] = [n]% | [n]% |
Management’s best defence, and our reply
Management would say goodwill [wording masked] the [segment] segment level, which spans several countries, so it has no meaningful geographical location. They would add that the heading states the exclusion openly, so no reader is misled about what the table contains. That position is reasonable enough that the point is put as a question; however, IFRS 8 paragraph 33(b) does not list goodwill among the permitted exclusions and, where information is unavailable, requires that fact to be stated, which the note does not do.
The fix
- Include goodwill in the table by the location of the cash-generating units that carry it, or add: 'Goodwill is not allocated to geographical areas because the information is not available and the cost to develop it would be excessive.'; extend the heading to 'and investments in joint ventures and associates'.
Question for the company
Why is goodwill excluded from the non-current assets by geography in Note 2.2, given that IFRS 8 paragraph 33(b) excludes only financial instruments, deferred tax assets, post-employment benefit assets and insurance rights? If the Group considers the location of goodwill cannot be determined at a reasonable cost, could the note say so; and could the heading also state that the investment in the associate ([n]) is excluded?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The heading excludes goodwill from the geographical analysis | Document | Annual Report 2025, page 199 |
| 2 | The geography table totals [n] (2024: [n]) | Document | Annual Report 2025, page 199 |
| 3 | Balance sheet goodwill of [n] (2024: [n]) | Document | Annual Report 2025, page 185 |
| 4 | Balance sheet [wording masked] [n], also outside the table | Document | Annual Report 2025, page 185 |
| 5 | Total non-current assets of [n] used in the reconciliation | Document | Annual Report 2025, page 185 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.