1.14 The 2024 comparative split of discontinued adjusting items does not add up to its own total
UK Company B · a UK-listed technology and logistics group · Presentation point
In brief
Note 2.9 says the 2024 adjusting items debit of [amount] in discontinued operations comprised [amount] of [former subsidiary] [wording masked] and [amount] of UK network capacity review costs. Those parts add to [amount], not [amount]. Note 2.5 and the 2024 Annual Report both give the UK network capacity review cost as [amount], which does add to [amount].
The evidence, as filed
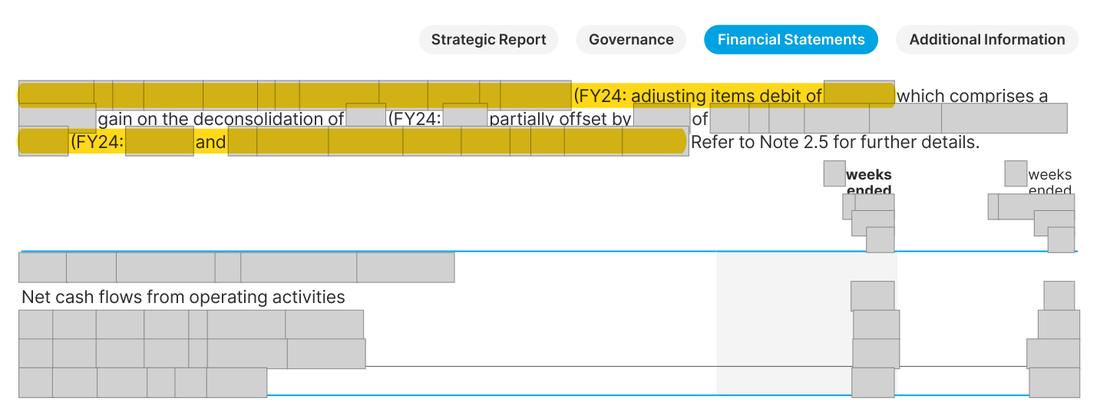
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 188; Annual Report 2025, page 202. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.211: "[wording masked]: [amount])"; [n] + [n] = [n] against a stated total of [amount] | What the rule requires "[wording masked]: [amount])", agreeing with Note 2.5 (row F) and the 2024 report; [n] + [n] = [n] |
The rule
IAS 1 Presentation of Financial Statements, paragraph 38
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Comparative narrative and descriptive information is required where it helps the reader understand the current year.
Why it applies here: the [amount] in the comparative is a transcription slip (it repeats the [amount] current-year [former subsidiary] transformation figure in the same sentence); no primary statement or table figure is affected.
Why it matters
A reader reconciling the discontinued adjusting items to Note 2.5 finds a [amount] gap in the comparative; the audited figures themselves are unaffected.
Exposure
Presentation slip within a note; no figure in the primary statements or the Note 2.5 table is wrong.
Our workings
the sentence on p.211 gives the 2024 discontinued adjusting items as a debit of [amount] made up of [amounts]. The Note 2.5 table on p.202 shows the UK network capacity review at ([n]) for 2024 and the discontinued adjusting items at ([n]). The 2024 Annual Report explained the same [amount] as [amount] plus a [amount] [place] lease impairment.
[n] + [n] = [n], a gap of [n] against the total; [n] + [n] = [n] agrees.
| Component (2024, discontinued) | AR [amount].211 sentence (£m) | Note [amount].202 / AR [amount].188 (£m) |
|---|---|---|
| [former subsidiary] IT and finance systems transformation | [n] | [n] |
| UK network capacity review | [n] | [n] |
| Sum of the components | [n] + [n] = [n] | [n] + [n] = [n] |
| Difference from the stated total of [n] | [n] - [n] = [n] | [n] - [n] = [n] |
| Correct UK network capacity review comparative | [n] - [n] = [n] | [n] |
| Misstated amount (printed less correct) | [n] - [n] = [n] | [n] / [n] = [n]% of group loss before tax |
Management’s best defence, and our reply
The finance team would say that the [amount] total, the Note 2.5 table and the primary statements are all right, and only one comparative figure in a narrative sentence is mistyped, so no reader would be misled about the results. They would add that the 2024 split was fully given in last year's report. However, the sentence sits inside the audited notes, its parts do not add to the total it explains, and it contradicts the Note 2.5 row in the same report; the slip is small but real and costs nothing to correct.
The fix
- Correct the comparative to read "[wording masked]: [amount])" in the next report's comparative note.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the 2024 discontinued adjusting items total is stated as [amount] | Document | Annual Report 2025, page 211 |
| 2 | the two 2024 components given are [amounts], which add to [amount] | Document | Annual Report 2025, page 211 |
| 3 | Note 2.5 gives the 2024 UK network capacity review cost as [amount] | Document | Annual Report 2025, page 202 |
| 4 | Note 2.5 confirms the discontinued totals of [amounts] | Document | Annual Report 2025, page 202 |
| 5 | the 2024 report split the same [amount] as [amount] plus [amount] | Document | Annual Report 2024, page 188 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.