1.11 The discontinued-operations note gives the net operating, investing and financing cash flows of [former subsidiary] for 2024 only, with no 2023 comparative
UK Company B · a UK-listed technology and logistics group · Compliance or disclosure gap
In brief
[former subsidiary] was classified as a discontinued operation at [date] and its 2023 results were re-presented. Note 2.9 gives its 2024 net cash flows (operating inflow [n] and a total net outflow of [n]) but no figures for the 53 weeks to [date], and the cash flow statement covers the whole group and refers to Note 2.9 for discontinued cash flows. IFRS 5 requires these disclosures to be re-presented for the prior period; the next year's report does give both periods.
The evidence, as filed
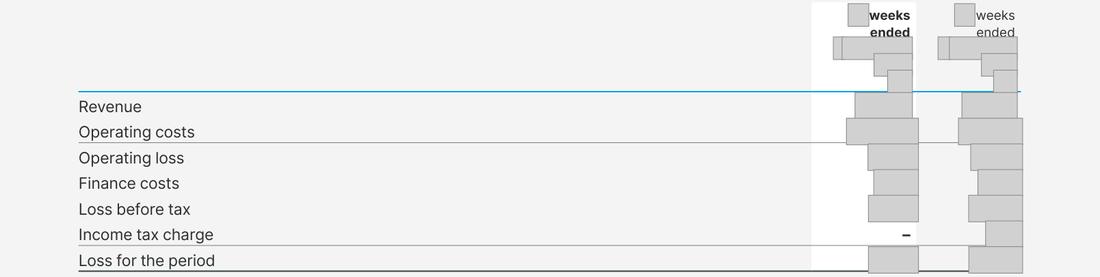
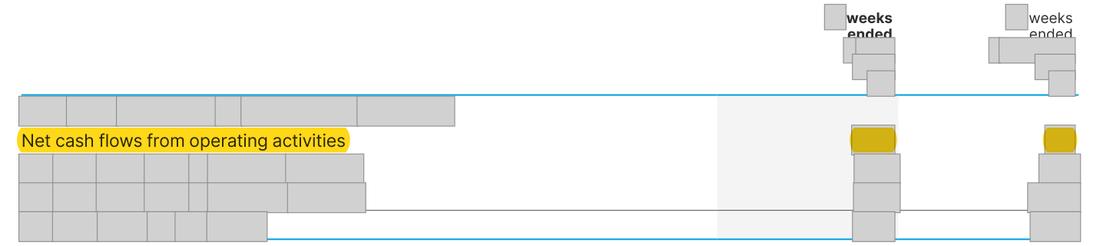
Annual Report 2025, page 211 · Prior year: The 2023 report is not held, and [former subsidiary] was not a discontinued operation in that year. The following year's report gives the discontinued cash flows for both of its periods, so the 2024 single column is not the company's later practice.
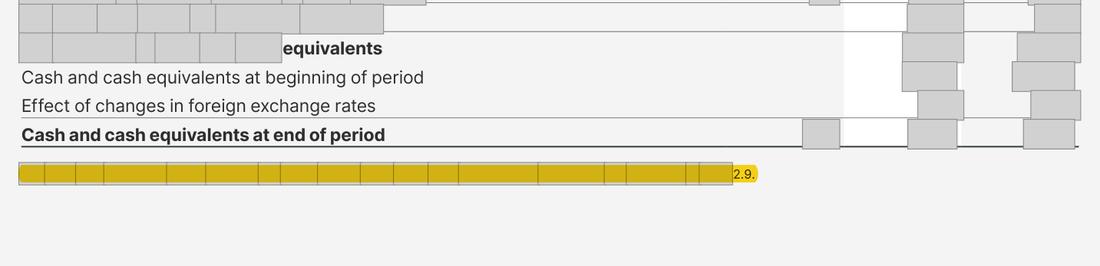
Further pages withheld to protect the company’s identity (one): Annual Report 2024, page 172. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Note 2.9: a single-column table '52 weeks ended [date]' of [wording masked]; the results table above it has both years. Cash flow statement: '[wording masked] [n].' | What the rule requires A second column giving the net cash flows from operating, investing and financing activities of [former subsidiary] (and the related eliminations) for the 53 weeks ended [date], as the 2025 report does for its comparative period. |
The rule
IFRS 5 Non-current Assets Held for Sale and Discontinued Operations, paragraph 33(c)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
The accounts must give the net operating, investing and financing cash flows of discontinued operations, in the notes or on the face of the statements.
IFRS 5 Non-current Assets Held for Sale and Discontinued Operations, paragraph 34
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
The discontinued-operations disclosures must be re-presented for prior periods so that they cover everything classified as discontinued by the latest year end.
Why it applies here: the 2023 comparative required by IFRS 5.34 is missing.
Why it matters
- A reader cannot compare the cash generated or used by [former subsidiary] in 2024 with 2023, or derive the continuing group's 2023 cash flows.
- The Annual Report 2025 gives both periods, which shows the comparative can be prepared.
A reader cannot compare the cash generated or used by [former subsidiary] in 2024 with 2023, or derive the continuing group's 2023 cash flows from the whole-group statement.
Exposure
A missing IFRS comparative is the kind of point the FRC's Corporate Reporting Review raises by letter, usually closed by an undertaking to include it in the next report; the 2025 report already presents two periods.
Our workings
Note 2.9 presents the [wording masked] both periods (revenue [n] and [n]) but its cash-flow table has only the 2024 column. The cash flow statement is for the whole group and sends the reader to Note 2.9 for discontinued cash flows, and no other page gives the 2023 figures (whole-report search under the terms listed). Law: IFRS 5.33(c) requires the net cash flows attributable to the operating, investing and financing activities of discontinued operations, and IFRS 5.34 requires the paragraph 33 disclosures to be re-presented for prior periods so that they relate to all operations discontinued by the end of the latest period.
The 2025 report's Note 2.9 shows the pattern expected, with an 18-week 2025 column and a 2024 column.
Management’s best defence, and our reply
Management could say [former subsidiary]'s 2023 cash flows were published in [former subsidiary]'s own filed accounts and in the prior year's segment commentary, and that the whole-group cash flow statement already includes them, so readers lost nothing material. They could add that the operation was classified as discontinued only at the 2024 year end and that the 2024 cash flows were the information readers needed. The answer: IFRS 5.34 makes the re-presentation of the paragraph 33 disclosures for the prior period a requirement, not an option, and the annual report must stand alone; the following year's report shows the comparative was available.
The fix
- Add a 2023 column to the Note 2.9 cash-flow table (net cash flows from operating, investing and financing activities for the 53 weeks ended [date]), or state that the comparative was impracticable to prepare and why.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The results of the discontinued operation are re-presented for both years | Document | Annual Report 2024, page 188 |
| 2 | The cash-flow table has a 2024 column only | Document | Annual Report 2024, page 188 |
| 3 | Total discontinued cash flow given for 2024 only | Document | Annual Report 2024, page 188 |
| 4 | The cash flow statement does not split discontinued cash flows and refers to Note 2.9 | Document | Annual Report 2024, page 171 |
| 5 | The comparatives were re-presented for the results | Document | Annual Report 2024, page 172 |
Absence check
- Document
- Annual Report 2024
- Where it would appear
- [wording masked]
- What is missing
- the net cash flows from operating, investing and financing activities of the discontinued operation for the 53 weeks ended [date]
- Pages looked at
- Annual Report [amount].169-171 (cash flow statement), 190-191 (Note 2.9), 205 (Note 3.10 cash and cash equivalents) page images
- Result
- The first three terms hit only p.188, the [n]-only table itself. 'cash flows from discontinued operations' hits only p.171, the sentence under the cash flow statement that refers the reader to Note 2.9. The cash flow statement's own line is 'Net cash flow from operating activities' for the whole group, not the discontinued operation.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.