1.10 The geographical revenue table does not say how revenue is attributed to countries, in either year
UK Company B · a UK-listed technology and logistics group · Compliance or disclosure gap
In brief
Note 2.1 splits revenue into the UK, Europe (excluding UK), North America and Asia Pacific, but neither the 2025 nor the 2024 report says on what basis revenue is attributed to a country, for example the location of the partner or of the site served. IFRS 8 requires that basis to be stated. North America, which brings together more than one country, is [n]% of 2025 revenue.
The evidence, as filed
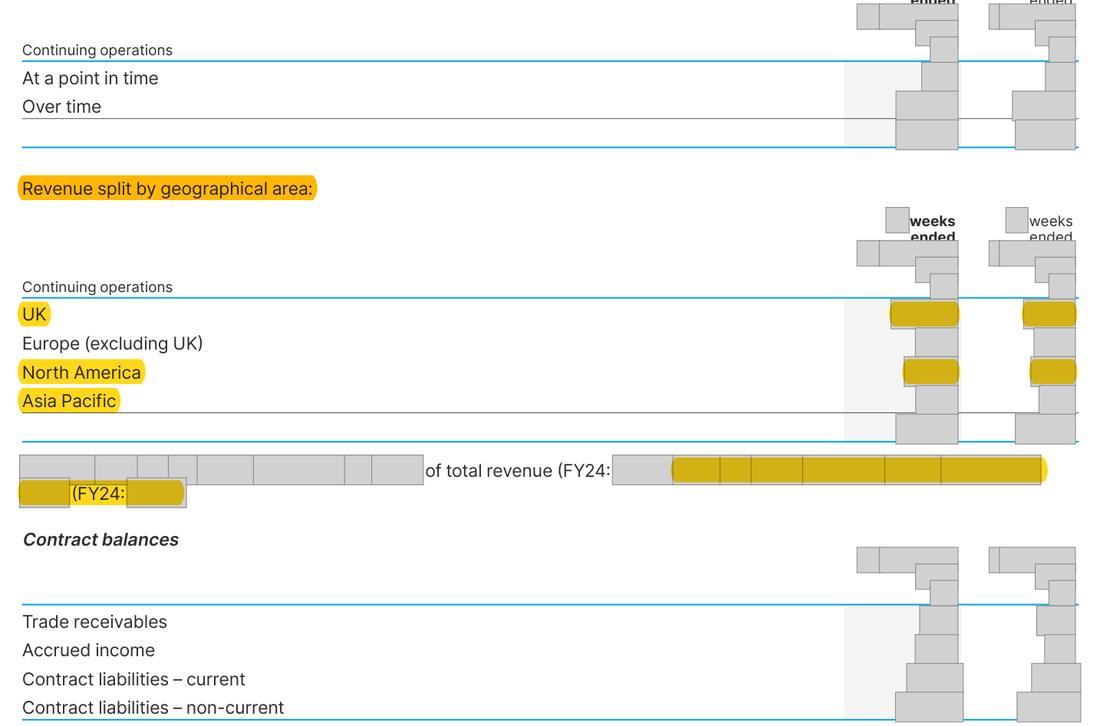
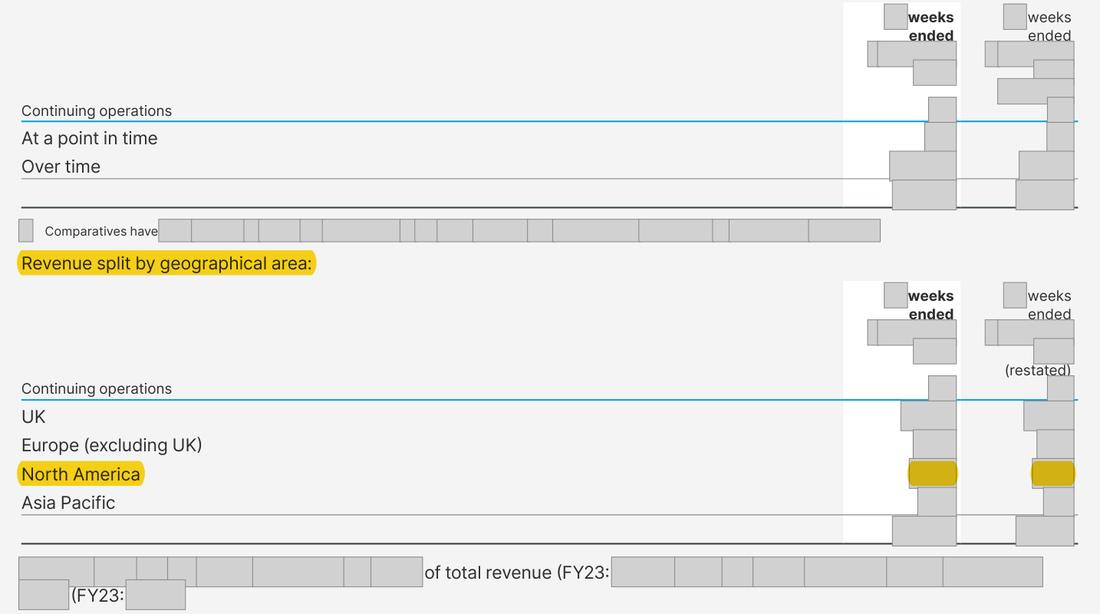
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.197: 'Revenue split by geographical area' with UK [n], North America [n] and total [n], and the statement that North America contributed [n]%; no sentence on how revenue is attributed to countries. The 2024 report has the same table with no basis stated. | What the rule requires A sentence in Note 2.1 stating the basis for attributing revenue from external customers to individual countries; and, if revenue from any single foreign country is material, that country's revenue shown separately rather than only within a regional subtotal. |
The rule
IFRS 8 Operating Segments, paragraph 33(a)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Revenue from external customers in any individual foreign country must be shown separately if material, together with the basis used to attribute revenue to countries.
Why it applies here: the basis-of-attribution sentence is an unconditional requirement that is missing in both years.
Why it matters
- A reader cannot tell whether revenue is placed by the partner's location or by the site served.
- Nor can a reader see whether revenue from any single foreign market inside the regional totals is material.
A reader cannot tell whether revenue is placed by the partner's location or by the site served, and cannot see whether revenue from any single foreign market inside the regional totals is material.
Exposure
No fine. Possible Financial Reporting Council Corporate Reporting Review enquiry and an undertaking to add the sentence in the next Annual Report.
Our workings
Note 2.1 gives revenue from continuing operations by region: UK [n], Europe (excluding UK), North America [n] and Asia Pacific, total [n], and says North America contributed [n]% (2024: [n]%). No sentence in the note, the segment note or the accounting policies states how revenue is attributed to a country; the 2024 report is the same.
revenue attributed to foreign countries in total is [n] - [n] = [n], of which North America is [n] / [n] = [n]% of the total. Law: IFRS 8 paragraph 33(a) requires revenue attributed to the country of domicile and to all foreign countries in total, separate disclosure of any material individual foreign country, and the basis for attributing revenue to individual countries. Paragraph [n] allows regional subtotals only in addition to that information.
Whether any single country inside North America is material on its own cannot be confirmed from the report; the regional grouping prevents the reader from seeing it, so that limb is put only as what the company should check.
| Measure | Computation | Result (£m or %) |
|---|---|---|
| Revenue attributed to foreign countries in total | [n] - [n] | [n] |
| North America share of revenue | [n] / [n] | [n]% |
Management’s best defence, and our reply
The company could say that the basis is obvious, since each partner contract is with a business operating in one country, and that IFRS 8 paragraph 33 itself permits subtotals for groups of countries, so the regional table is a recognised format. It could add that the amounts outside the UK are modest. The answer: paragraph 33 allows regional subtotals only in addition to the required information, and the sentence stating the basis of attribution is unconditional; a basis that seems obvious to management is still a required disclosure, and it costs one sentence to give.
The fix
- Add to Note 2.1: 'Revenue is attributed to countries on the basis of [the location of the partner / the location of the site served]', and show separately the revenue of any individual foreign country that is material, keeping the regional subtotals if wished.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The geographical table has no statement of how revenue is attributed to countries | Document | Annual Report 2025, page 197 |
| 2 | Revenue grouped by region; no individual foreign country shown | Document | Annual Report 2025, page 197 |
| 3 | Revenue attributed to the country of domicile | Document | Annual Report 2025, page 197 |
| 4 | Total revenue from continuing operations | Document | Annual Report 2025, page 197 |
| 5 | The report's own share for the North America region | Document | Annual Report 2025, page 197 |
| 6 | 2024 report: the same regional table, also with no basis of attribution | Document | Annual Report 2024, page 177 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- Revenue split by geographical area:
- What is missing
- the basis for attributing revenue from external customers to individual countries
- Pages looked at
- p.192-199 (Notes 1 and 2.1-2.2, including the revenue policy) and the whole report text; Annual Report [amount].175-179
- Result
- 'geographical area' hits only the two table headings (p.197 revenue, p.199 non-current assets); 'attributed to' hits p.176 (auditor's work on [former subsidiary]) and [n] (goodwill policy), neither about revenue by country; 'location of the customer', 'by country' and 'based on the location' have no hits. The 2024 report has the same table (Annual Report [amount].177) and no basis sentence.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.