1.03 The 2025 net book value of each class of intangible assets does not follow from the cost and amortisation in the same note
UK Company B · a UK-listed technology and logistics group · Compliance or disclosure gap
In brief
In the Note 3.2 table (£ million), internally generated intangible assets at [date] have cost of [n] and accumulated amortisation of [n], which leaves [n] - [n] = [n], but the net book value row prints [n]. Other intangible assets leave [n] - [n] = [n] but print [n]. The total of [n] is right, so [n] sits in the wrong class in one of the rows; the 2024 column casts correctly.
The evidence, as filed
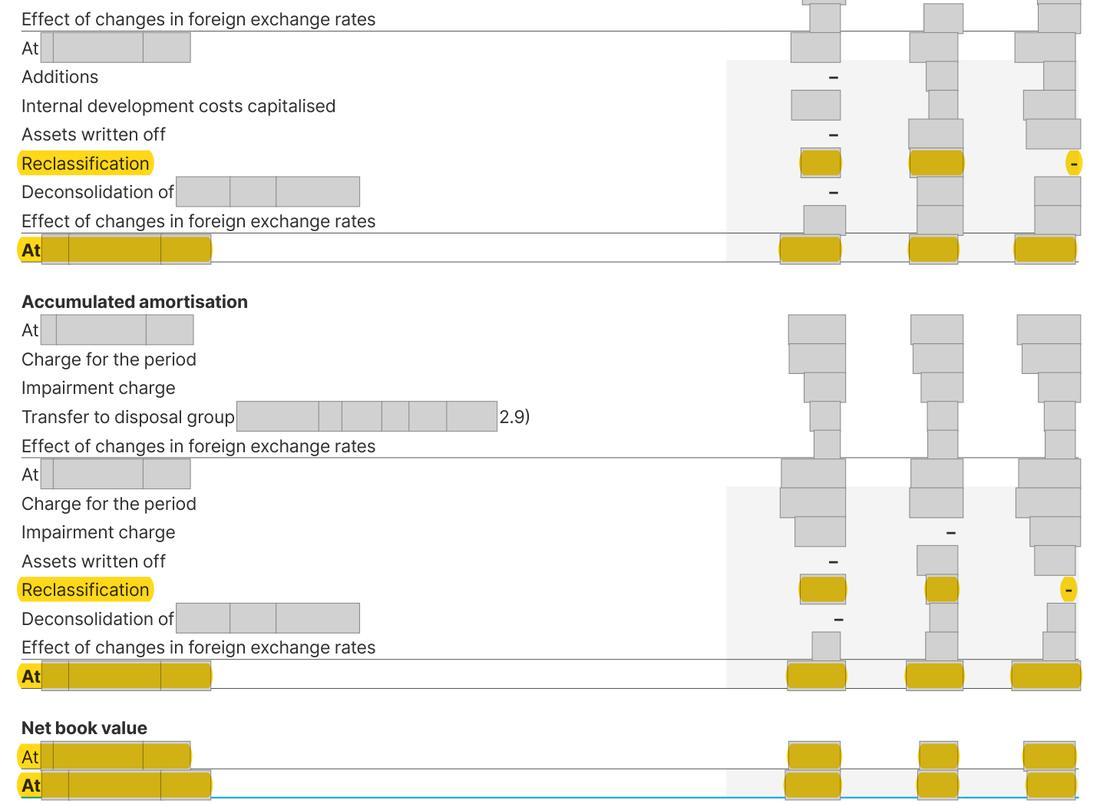
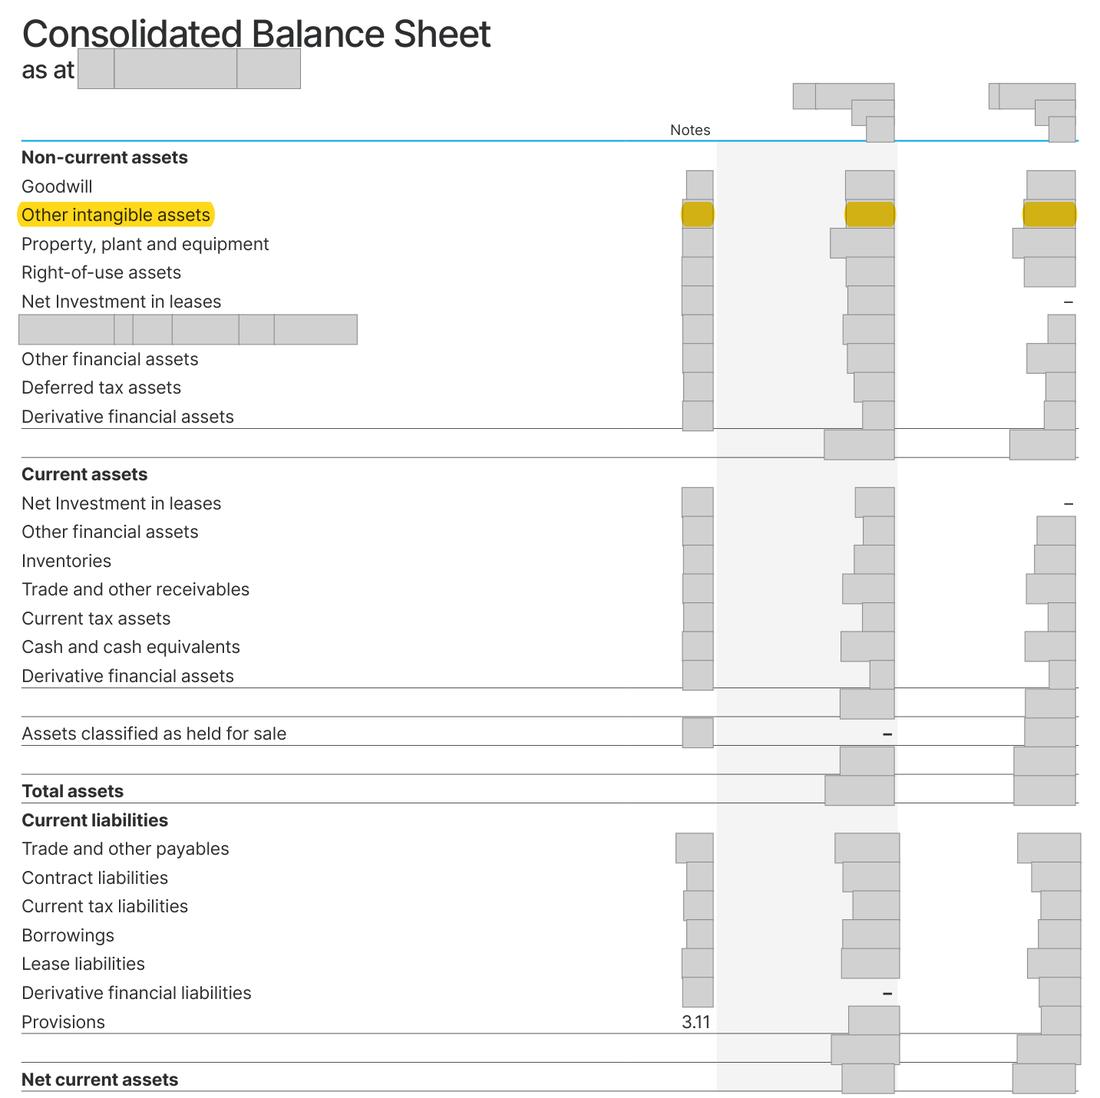
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.215 net book value at [date]: internally generated [n], other [n], total [n] | What the rule requires On the table's own cost and amortisation: internally generated [n] - [n] = [n] and other [n] - [n] = [n] (total [n]), or the cost and amortisation rows corrected so that each column casts |
The rule
IAS 38 Intangible Assets, paragraph 118(c) and (e)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
For each class of intangible asset, the accounts must give the gross carrying amount and accumulated amortisation at the start and end of the year, and a reconciliation of the movements.
Why it applies here: [amount] of carrying amount is allocated to the wrong class in either the net book value row or the cost and amortisation rows (the 2025 reclassification row moves [n] of cost and [n] of amortisation between the classes, a likely source); the note alone cannot show which.
Why it matters
- The split by class is an audited IAS 38 disclosure, and as printed it does not follow from the figures above it.
- The total is right, so the correction is a re-cast of one column with a footnote.
The audited split of the carrying amount between internally generated and other intangible assets is wrong by [amount] in one direction or the other, so a reader cannot rely on the class figures that IAS 38 requires; the total is unaffected.
Exposure
A Financial Reporting Council Corporate Reporting Review enquiry could ask for the class split to be corrected; the realistic outcome is a corrected comparative in the 2026 report, not a revision of the accounts.
Our workings
the Note 3.2 table on p.215 prints, for [date], cost of [n] / [n] / [n], accumulated amortisation of ([n]) / ([n]) / ([n]) and net book value of [n] / [n] / [n] for internally generated, other and total.
[n] - [n] = [n] against [n] ([n] lower); [n] - [n] = [n] against [n] ([n] higher); [n] - [n] = [n] agrees with the total and the balance sheet. The 2024 column casts ([n] - [n] = [n]; [n] - [n] = [n]).
The Companies House copy prints the same figures.
| Class at [date] (£m) | Cost less accumulated amortisation | Printed net book value | Difference |
|---|---|---|---|
| Internally generated intangible assets | [n] - [n] = [n] | [n] | [n] - [n] = -[n] |
| Other intangible assets | [n] - [n] = [n] | [n] | [n] - [n] = [n] |
| Total | [n] - [n] = [n] | [n] | [n] - [n] = [n] |
| Prior-year column ([date]) | [n] - [n] = [n]; [n] - [n] = [n] | [n]; [n] | nil |
| Materiality | [n] / [n] = 3% of group loss before tax | [n] / [n] = [n]% of the line |
Management’s best defence, and our reply
The finance team would say that the total carrying amount of [amount], the balance sheet, the amortisation charge and the impairment are all right, and that the 2025 reclassification of [amount] of cost between the two classes explains the difference, so this is an allocation slip within one note. They could add that the two classes are both software and patents, so the split carries little decision weight. However, IAS 38 requires the gross amount and accumulated amortisation for each class at the end of the period and a reconciliation of each class's carrying amount, and as printed one of those required class figures is wrong by [amount]; the slip changes no total but it is an error in an audited figure, not a matter of judgement.
The fix
- Re-cast the 2025 column and correct the class split (in the net book value row, or in the cost and amortisation rows if the reclassification was allocated wrongly) in the comparative column of the 2026 report, with a footnote.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | cost at [date]: internally generated [n], other [n], total [n] | Document | Annual Report 2025, page 215 |
| 2 | accumulated amortisation at [date]: ([n]), ([n]), ([n]) | Document | Annual Report 2025, page 215 |
| 3 | printed net book value [n] and [n], which differ by [n] from cost less amortisation in each column; total [n] agrees | Document | Annual Report 2025, page 215 |
| 4 | the 2025 reclassification moves [n] of cost between the classes | Document | Annual Report 2025, page 215 |
| 5 | the 2025 reclassification moves [n] of accumulated amortisation between the classes | Document | Annual Report 2025, page 215 |
| 6 | the 2024 net book value by class casts ([n] - [n] = [n]; [n] - [n] = [n]) | Document | Annual Report 2025, page 215 |
| 7 | the balance sheet carries the total of [n], which is unaffected | Document | Annual Report 2025, page 185 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.