7.21 Notes 19-21: wrong final dividend dates, a financing column called 'bank loans' that includes private placement notes, and a 2022 acquisition still called provisional
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
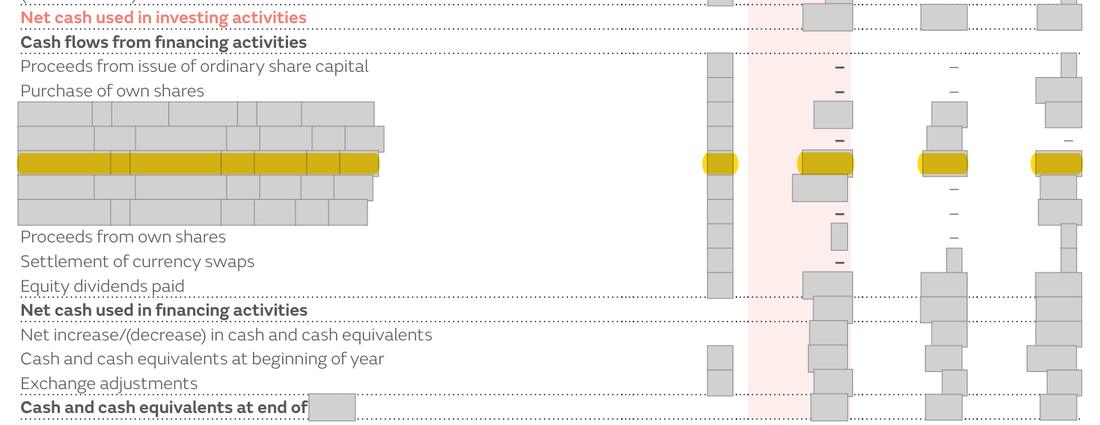
Three drafting slips in the later notes. Note 19.3 says the 2024 final dividend will be paid on [date] to shareholders on the register on [date], while the shareholder information gives a record date of [date] and a payment date of [date], the financial calendar gives [date], and the 2025 report confirms it was paid on [date]. Note 20's financing table calls the [amount] repaid in 2024 'Repayment of bank loans', although the Financial review says the Group settled [amount] of private placement debt and repaid [amount] of RCF. Note 21 still calls the 2022 [company] consideration 'provisional' in the 2024 report.
The evidence, as filed
Further pages withheld to protect the company’s identity (seven): Annual Report 2024, page 242; Annual Report 2025, page 261; Annual Report 2024, page 273; Annual Report 2024, page 289; Annual Report 2024, page 244; Annual Report 2024, page 26; Annual Report 2024, page 245. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Dividends note: 'will be paid ... on [date] [wording masked] [date]'. Financing table: 'Repayment of bank loans' [n]. Acquisitions note: '[wording masked] [amount]'. | What the rule requires Dividends note: payment [date], record date [date]. Financing table: 'Repayment of borrowings' (or separate private placement and bank loan columns). Acquisitions note: 'the fair value of the consideration was [amount]'. |
Why it matters
A shareholder reading the audited note would expect payment a month early and a different record date; the financing table understates the private placement repayment by labelling it as bank loans.
Exposure
Dates and labels only; no amount is affected.
Our workings
the dividend dates in the audited note differ from the dates in the shareholder information and the financial calendar of the same report, and the 2025 report records payment on [date]; the note's [date] date is the date of the AGM.
the cash flow statement shows [wording masked] of [amount] and the Financial review attributes it to private placement debt and the RCF; the financing table's footnote mentions only the RCF.
the Engage acquisition completed on [date], so its measurement period ended in [date].
Management’s best defence, and our reply
The company would say the correct dividend dates were announced by regulatory announcement and appear twice elsewhere in the report, the financing table reconciles exactly to the cash flow statement, and the Engage wording is historical. Nothing material is misstated. That is right as to amounts, which is why these are drafting slips; however, the audited note gives dates that did not happen and a label that does not describe [amount] of the repayment.
The fix
- Align the dividend dates in Note 19.3 with the shareholder information; relabel the financing column 'Repayment of borrowings'; remove 'provisional' from the 2022 acquisition text.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the audited note's payment and record dates | Document | Annual Report 2024, page 242 |
| 2 | shareholder information gives different dates | Document | Annual Report 2024, page 273 |
| 3 | financial calendar agrees with [date] | Document | Annual Report 2024, page 289 |
| 4 | the 2025 report records payment on [date] | Document | Annual Report 2025, page 261 |
| 5 | [n] sits in the column headed 'Repayment of bank loans' | Document | Annual Report 2024, page 244 |
| 6 | the column footnote mentions only the RCF | Document | Annual Report 2024, page 244 |
| 7 | the repayment included private placement notes | Document | Annual Report 2024, page 26 |
| 8 | the cash flow statement line the table reconciles | Document | Annual Report 2024, page 194 |
| 9 | a 2022 acquisition still described as provisional | Document | Annual Report 2024, page 245 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.