7.20 The 2023 comparative fair value table places trade and other receivables in the hedging instruments column
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
In the [date] comparative table of Note 16.6, trade and other receivables of [amount] are printed under 'Fair value – hedging instruments' instead of 'Amortised cost'. The 2024 table on the facing page puts the same line, [amount], under amortised cost. Only the column is wrong; the row total and the table total are right.
The evidence, as filed
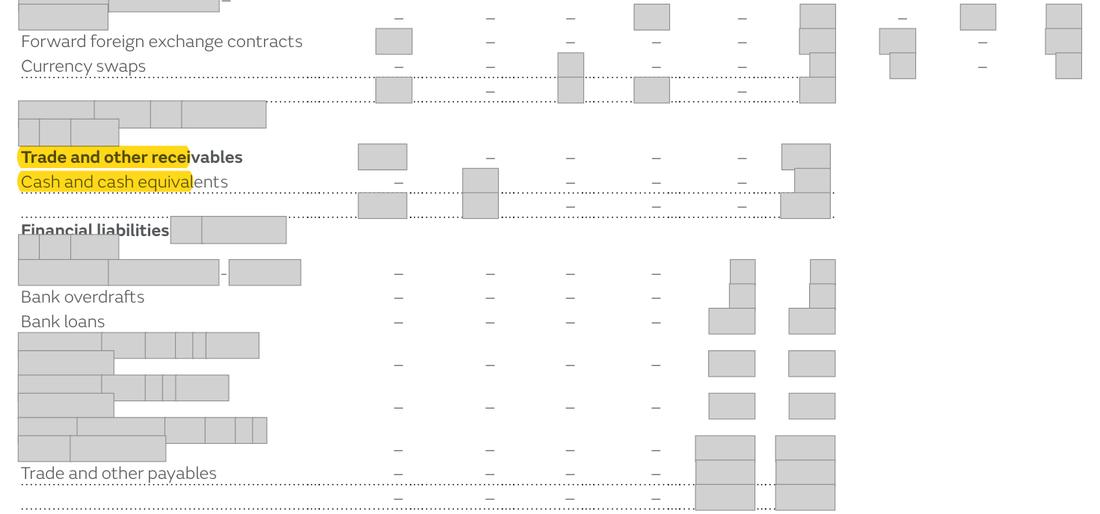
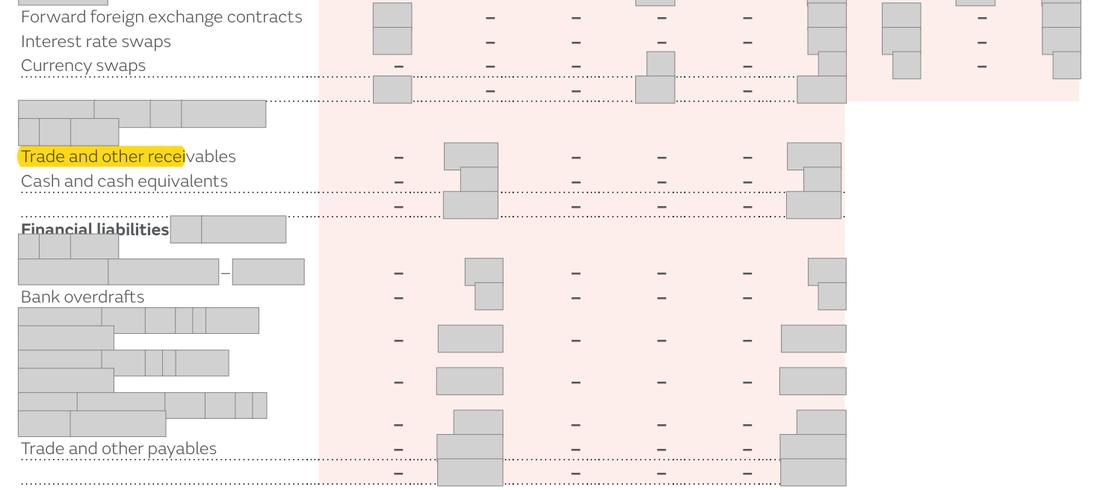
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2023 table: Trade and other receivables [n] in the 'Fair value – hedging instruments' column; sub-total row [n] | 302 | [n]. | What the rule requires Trade and other receivables [n] in the 'Amortised cost' column, so that the amortised cost sub-total for [wording masked] reads [n]. |
The rule
IFRS 7 Financial Instruments: Disclosures, paragraph 8
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
The carrying amount of each category of financial asset and financial liability must be disclosed, on the face of the balance sheet or in the notes.
Why it applies here: a column-alignment slip in the comparative table; the categories it shows for 2023 do not match the categories the Group applies to receivables.
Why it matters
A reader of the comparative table sees [amount] of hedging instruments and an understated amortised-cost category for 2023.
Exposure
Presentation slip in a comparative; no figure in the primary statements is affected.
Our workings
the comparative table on p.229 puts receivables of [amount] in the hedging-instruments column, and its sub-total row carries the same split.
the current-year table on p.228 shows receivables of [amount] under amortised cost, and the 2025 report repeats that placement for the 2024 comparative.
Management’s best defence, and our reply
The finance team would say the slip is typographical: the row total, the table total and the balance sheet are right, and the receivables policy elsewhere makes clear they are held at amortised cost. The 2024 table, which is the current-year disclosure, is right. That is fair as to size, which is why this is only a drafting slip; but the comparative as printed still shows the wrong category for [amount].
The fix
- Move the 2023 receivables figure to the 'Amortised cost' column whenever the 2023 table is reproduced, and proof-read column placement in the category tables.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2023 receivables printed in the first column, headed 'Fair value – hedging instruments' | Document | Annual Report 2024, page 229 |
| 2 | the sub-total row repeats the split: [n] under hedging instruments, 302 under amortised cost | Document | Annual Report 2024, page 229 |
| 3 | the 2024 table places the same line under amortised cost | Document | Annual Report 2024, page 228 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.