7.16 Pension notes: an unlabelled total, a narrow 'net interest' label and out-of-date wording on the US Plan and on UK inflation risk
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
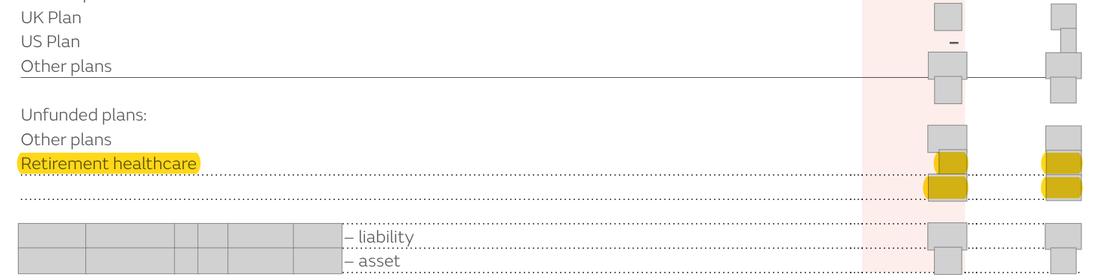
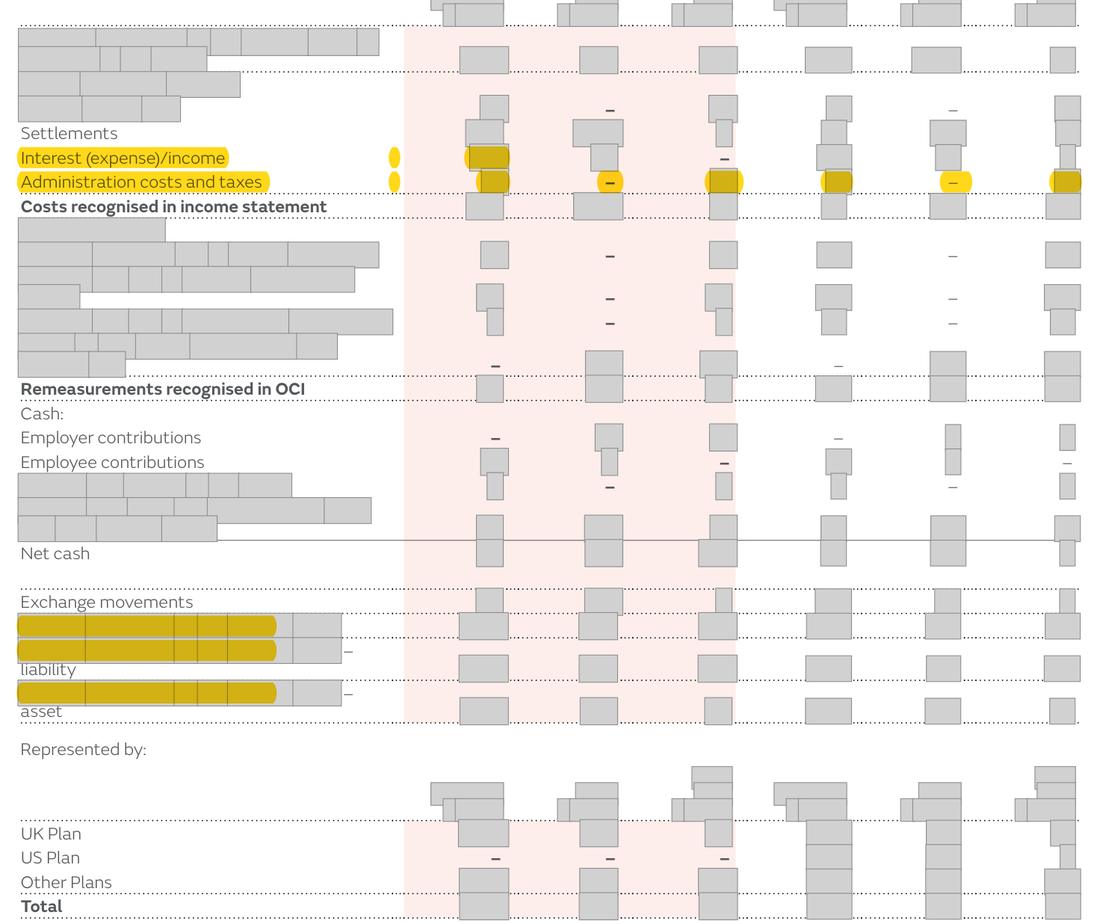
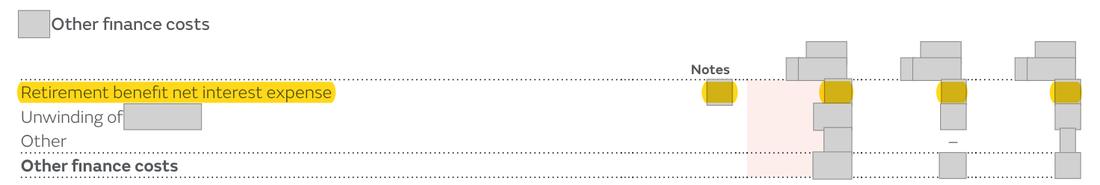
Four presentation slips in the pension disclosures. In Note 18.1 the line under 'Retirement healthcare' has no label: it is the net amount recognised for all plans, not a sub-total of the unfunded plans above it. Note 4.2 calls the pension charge in other finance costs 'net interest expense', although Note 18.2 shows net interest of nil for 2024 and Note 18.4 says administration costs and taxes are also reported there. Note 18.7 still describes the US Plan's de-risking policy in the present tense although the plan was bought out on [date]. In the 2025 Group (consolidated) notes, Note 18.7 also still says UK inflation [wording masked], although the UK Plan's assets are now mainly a [amount] insurance contract. The first and third slips are repeated in the 2025 report.
The evidence, as filed
Further pages withheld to protect the company’s identity (five): Annual Report 2025, page 253; Annual Report 2025, page 258; Annual Report 2024, page 237; Annual Report 2024, page 239; Annual Report 2024, page 234. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Assets and obligations table: an unlabelled line ([n]) (2023: ([n])) beneath 'Retirement healthcare'. Other finance costs: 'Retirement benefit net interest expense' (4) (2023: (1)). Risk section: '[wording masked] ...'. 2025 risk section: '[wording masked].' | What the rule requires Note 18.1: label the line 'Net retirement benefit assets/(obligations)' and show the unfunded sub-total separately. Note 4.2: 'Retirement benefit net interest, administration costs and taxes'. Note 18.7: describe the US Plan in the past tense, or delete the sentences, and describe UK inflation risk as now covered by the buy-in insurance contract. |
Why it matters
A reader may take the unlabelled line for an unfunded-plans total and the Note 4.2 line for pure interest; the risk note describes a US policy that no longer operates and a UK inflation hedge that the buy-in has replaced.
Exposure
Labels and narrative only; no figure is affected.
Our workings
Note 18.2 shows the [wording masked] as ([n]) for 2024 and ([n]) for 2023, the same figures printed without a label in Note 18.1 under the unfunded plans.
Note 18.2 shows interest (expense)/income nil for 2024 and income for 2023, and administration costs and taxes as a separate charge; Note 18.4 says both are reported in other finance costs, so the Note 4.2 line combines them under an interest-only label.
Notes 18.1 and 18.8 say the US Plan premium was paid on [date] and no liability remains, while Note 18.7 keeps a present-tense description of its asset glide path.
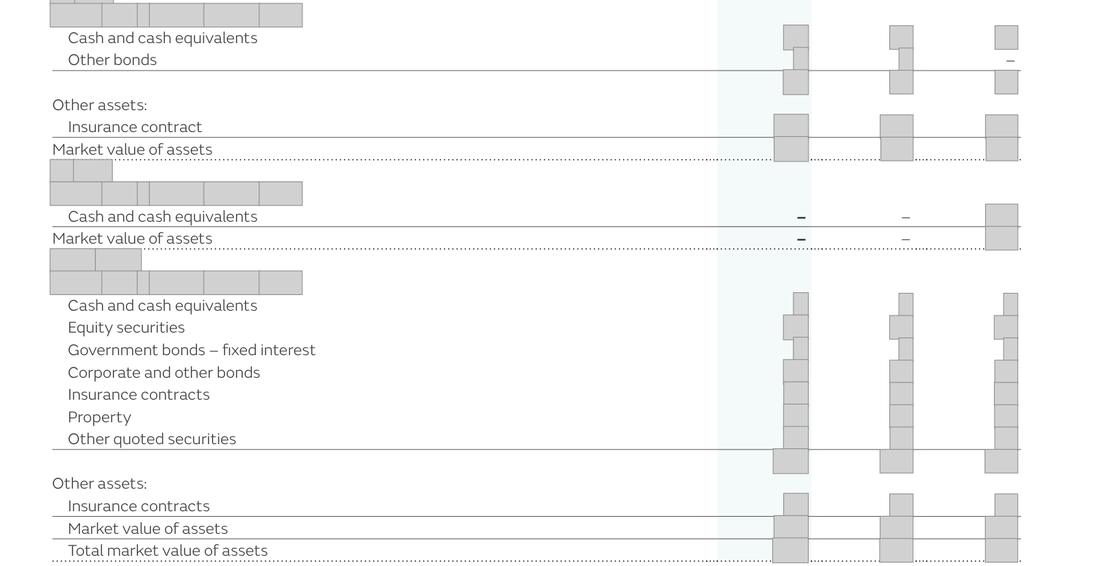
in the 2025 report, Note 18.7 says UK inflation [wording masked]', and that the gilt portfolio [wording masked]; Note 18.3 shows the UK Plan's assets as an insurance contract of [amount] plus cash and other bonds, with no gilt or liability driven investment line, and the same risk paragraph ends by saying residual inflation risk passed to the insurers after the 2023 buy-in.
Management’s best defence, and our reply
The finance team would say the figures are all correct and reconcile: the Note 18.1 line is visibly the total of the two sub-totals, Note 18.4 explains that administration costs sit in other finance costs, and the risk note goes on to say the US buy-out and the UK buy-in removed the risks. On that view nothing a reader needs is missing. That is why these are drafting slips only; however, the labels as printed describe the figures less precisely than the notes behind them, and the same wording has been carried into the next year's report.
The fix
- Label the Note 18.1 net line and add the unfunded sub-total; widen the Note 4.2 caption to include administration costs and taxes; update the US Plan and UK inflation-risk wording in Note 18.7.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the line after retirement healthcare carries no label | Document | Annual Report 2024, page 233 |
| 2 | the same ([n]) / ([n]) is the net amount recognised for all plans | Document | Annual Report 2024, page 235 |
| 3 | the line in other finance costs is labelled net interest only | Document | Annual Report 2024, page 205 |
| 4 | net interest is nil in 2024 and income in 2023 | Document | Annual Report 2024, page 235 |
| 5 | administration costs and taxes are the 2024 charge | Document | Annual Report 2024, page 235 |
| 6 | both items are reported in other finance costs | Document | Annual Report 2024, page 237 |
| 7 | present-tense description of a plan already bought out | Document | Annual Report 2024, page 239 |
| 8 | US buy-out completed on [date] | Document | Annual Report 2024, page 234 |
| 9 | the 2025 report repeats the unlabelled line | Document | Annual Report 2025, page 253 |
| 10 | the 2025 report repeats the US Plan sentence | Document | Annual Report 2025, page 258 |
| 11 | the 2025 risk section still says UK inflation risk is managed with inflation-linked bonds and liability-driven investments | Document | Annual Report 2025, page 258 |
| 12 | after the 2023 full buy-in the UK Plan's assets are the insurance policy plus cash and other bonds; no gilts or liability-driven investments | Document | Annual Report 2025, page 256 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.