7.15 Auditor's report: cross-references that land on the wrong pages or notes, a wrong committee name and typos (both years)
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
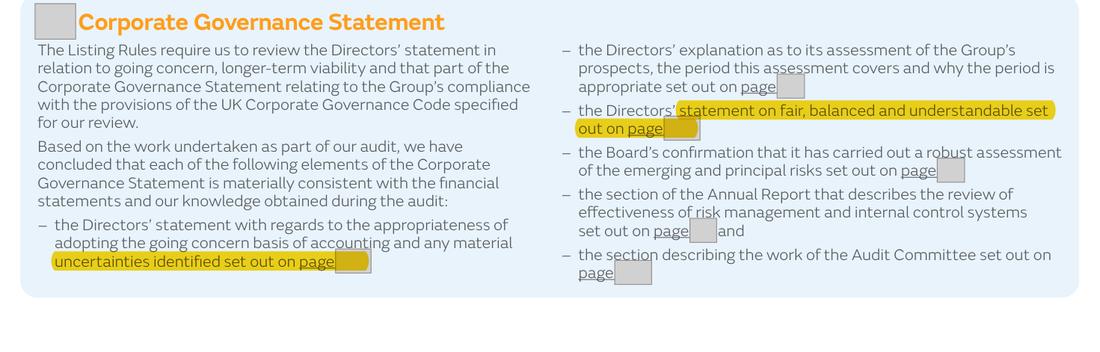
Both years. In the 2024 auditor's report, section 13 points to the directors' going concern statement 'on page 179' and to the fair, balanced and understandable statement 'on page 131'. Page [n] carries the fair, balanced and understandable statement and only the going concern responsibility; the going concern statement is on page 135. Page [n] is the Audit Committee's list of focus areas and does not mention fair, balanced and understandable. The 2024 report also reads 'enquries', 'subsidaries' and 'convenance compliance calculations'. In the 2025 report the key audit matter on the excess and obsolescence provision says the [wording masked] 1, but note 1 states that there are [wording masked]; the description is in note [n]; the 2025 report also refers once to an 'Audit & Risk Committee' (the company has an Audit Committee, as the same report says elsewhere) and reads '[wording masked]'.
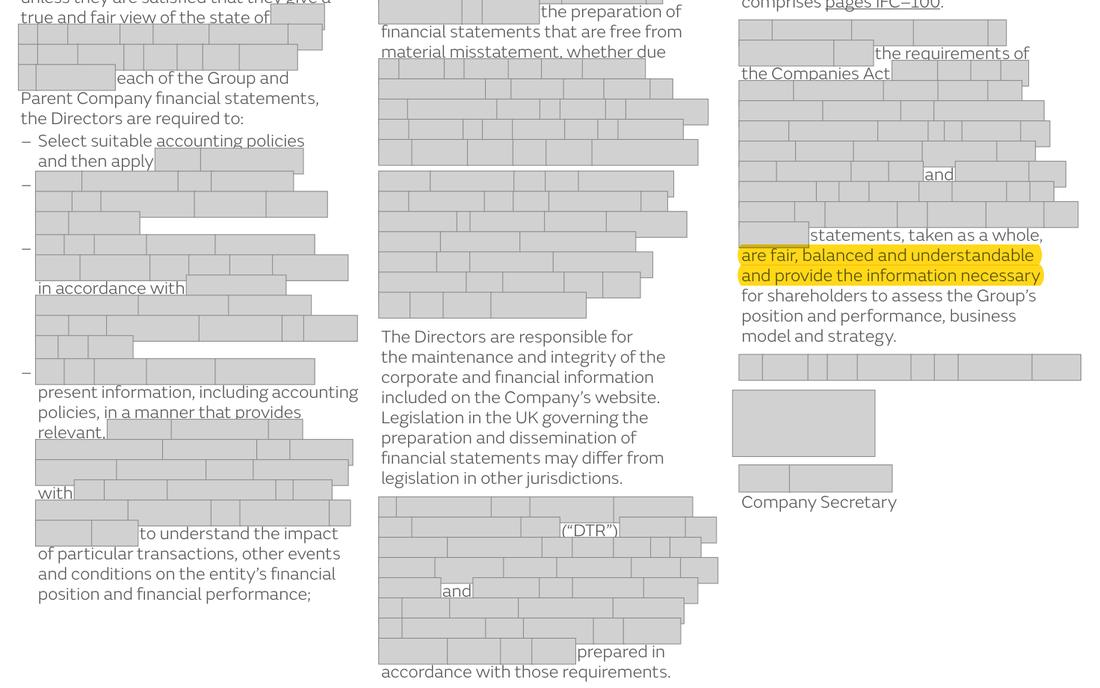
The evidence, as filed
Further pages withheld to protect the company’s identity (seven): Annual Report 2025, page 206; Annual Report 2024, page 135; Annual Report 2025, page 201; Annual Report 2024, page 131; Annual Report 2025, page 216; Annual Report 2024, page 184; Annual Report 2024, page 182. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2024: going concern statement referenced to page 179, which holds only the going concern responsibility; fair, balanced and understandable statement referenced to page 131 (it is on page 179); 'Performed enquries' in the inventory provision key audit matter; 'its subsidaries'; 'convenance compliance calculations'. 2025: key audit matter says the [wording masked] 1'; note 1 says there are [wording masked]; 'the Audit & Risk Committee'; '[wording masked]'. | What the rule requires 2024: going concern statement 'set out on page 135'; fair, balanced and understandable statement 'set out on page 179'; 'enquiries'; 'subsidiaries'; 'covenant compliance calculations'. 2025: the key audit matter refers to note [n], where the provision estimate is described; 'the Audit Committee'; 'jurisdictions in which the Group operates'. |
Why it matters
A reader following the auditor's references reaches the wrong pages.
Exposure
Cross-references and spelling only.
Our workings
the corporate governance statement section of the 2024 auditor's report lists the parts it reviewed with page references. The going concern statement appears under 'Going concern' in the Audit Committee report on page 135; page 179 is the statement of directors' responsibilities, which lists the duty to assess going concern and carries the fair, balanced and understandable confirmation. Page [n] holds the Audit Committee's meetings and focus areas. In the 2025 report the key audit matter on the US [business unit] excess and obsolescence provision says the group's [wording masked] 1 with further disclosures in note [n]; note 1 states that the group has [wording masked], and the estimate is described only in note [n]. The 2024 report also misspells 'subsidiaries' (page 180) and writes 'convenance' for 'covenant' (page 182); the 2025 report names an 'Audit & Risk Committee' once (page 206) though it calls the committee the Audit Committee elsewhere, and reads 'in with' for 'in which'.
Management’s best defence, and our reply
The company would say page 179 does deal with going concern, since it sets out the directors' going concern responsibilities, and that the auditor's report is the auditor's text. However, the reference is to the directors' statement on the appropriateness of the going concern basis, which is on page 135, and page 131 contains nothing on fair, balanced and understandable. For 2025 the auditor would say note 1 is where accounting estimates are generally discussed; but note 1 expressly says there are [wording masked], so the reference sends the reader to a note that does not describe the provision.
The fix
- Correct the [n]-style references to 'page 135' (going concern) and the fair, balanced and understandable page, spell 'enquiries', 'subsidiaries' and 'covenant', name the Audit Committee correctly, read 'in which', and in the [n]-style key audit matter refer to note [n] (or add the estimate to note 1).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Going concern statement referenced to page 179 | Document | Annual Report 2024, page 190 |
| 2 | Fair, balanced and understandable statement referenced to page 131 | Document | Annual Report 2024, page 190 |
| 3 | The directors' going concern statement is on page 135 | Document | Annual Report 2024, page 135 |
| 4 | The fair, balanced and understandable statement is on page 179 | Document | Annual Report 2024, page 179 |
| 5 | Page [n] is the Audit Committee's meetings and focus areas page | Document | Annual Report 2024, page 131 |
| 6 | Spelling slip in key audit matter [n] | Document | Annual Report 2024, page 184 |
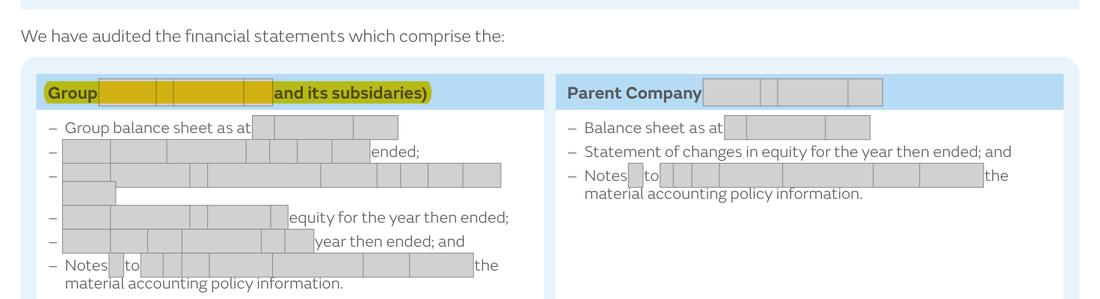
| 7 | Auditor's report spells 'subsidiaries' as 'subsidaries' | Document | Annual Report 2024, page 180 |
| 8 | Auditor's report going-concern section writes 'convenance' for 'covenant' | Document | Annual Report 2024, page 182 |
| 9 | The 2025 auditor's report names an 'Audit & Risk Committee'; the company's committee is the Audit Committee, as the same report says elsewhere | Document | Annual Report 2025, page 206 |
| 10 | The same report uses the correct committee name | Document | Annual Report 2025, page 210 |
| 11 | Typo: 'in with' for 'in which' | Document | Annual Report 2025, page 206 |
| 12 | The key audit matter sends the reader to note 1 for the estimate | Document | Annual Report 2025, page 201 |
| 13 | Note 1 says there are [wording masked]; the inventory estimate is described only in note [n] | Document | Annual Report 2025, page 216 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.