7.04 Related undertakings list: [company] percentage contradicts its footnote, and a [place] address is left without a company
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
Two slips in the list of related undertakings. [company] is shown at [n]%, the [company] voting percentage, while its own footnote says the holding represents a [n]% economic interest; the 2024 list showed [n]%. The registered office key still gives a [place] address, but no [place] company appears in the 2025 list; the Company [place] S.R.L., a dormant company, was listed in 2024.
The evidence, as filed
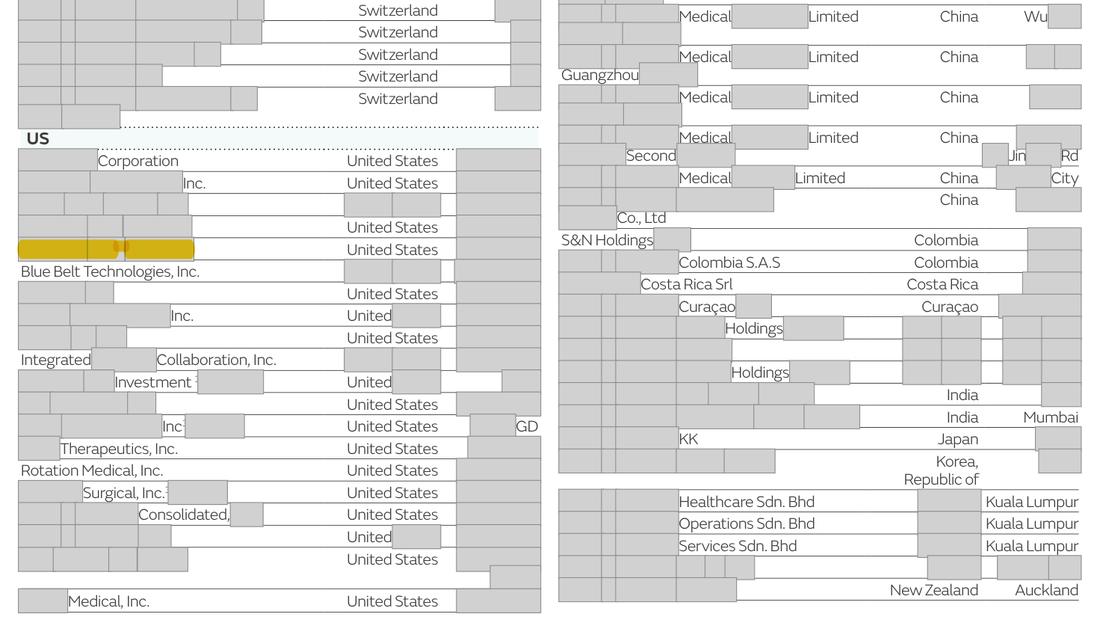
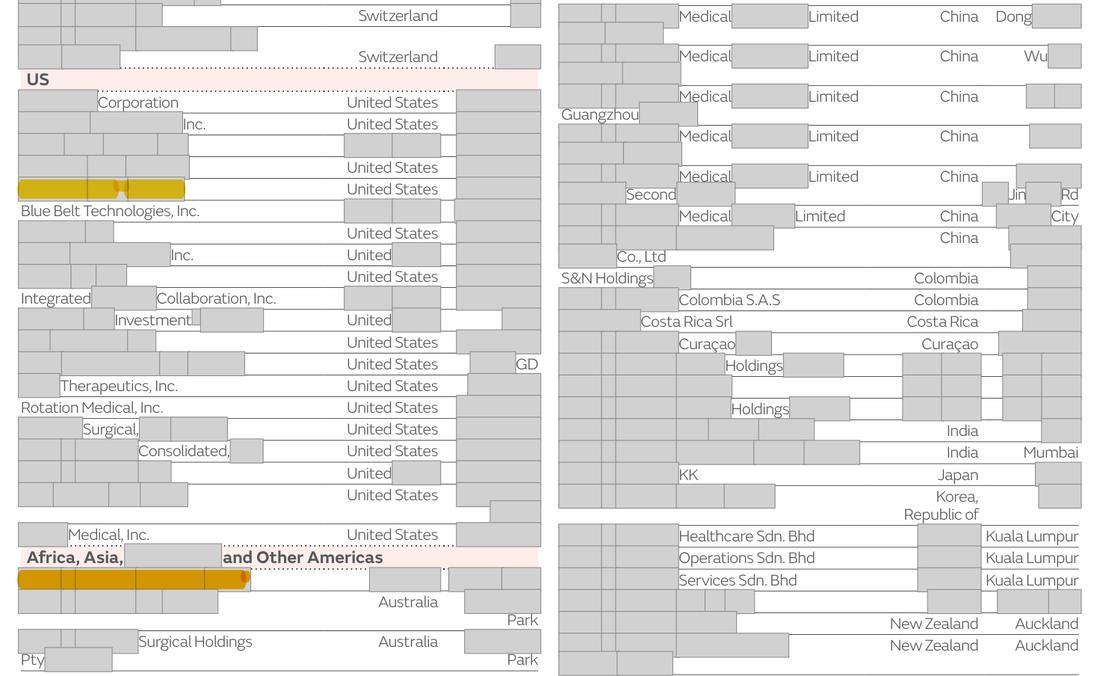
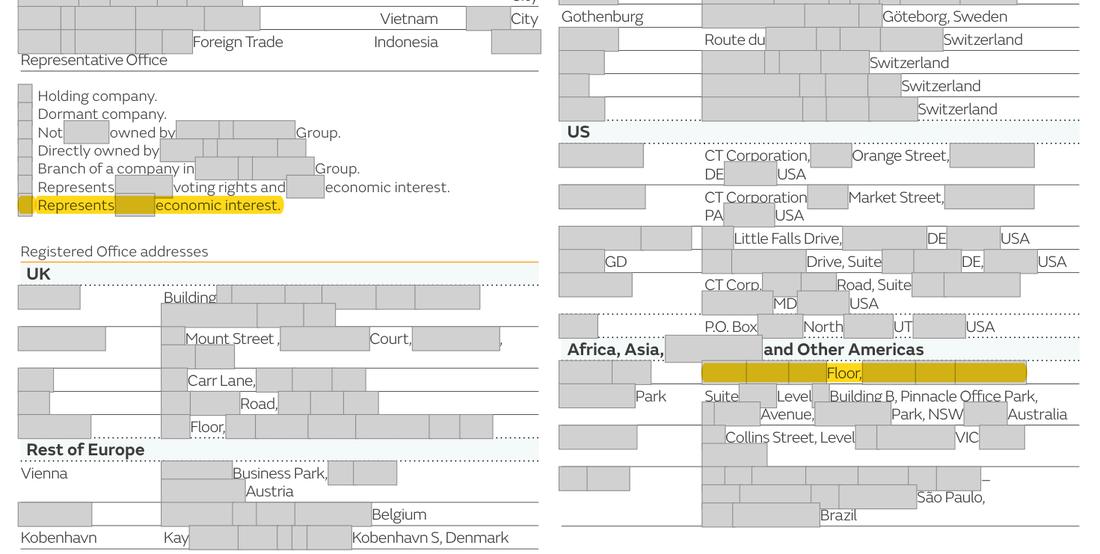
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.271: '[company] ([n]%)'; p.272 footnote 7: 'Represents [n]% economic interest'; p.272 key: [place] address with no company keyed to it. | What the rule requires [company] shown at [n]%; the [place] key entry deleted, or the Company [place] S.R.L. listed if it still existed at [date]. |
Why it matters
Readers are given a holding percentage for [company] that contradicts its own footnote, and an address key that points to a company the list no longer names.
Exposure
Drafting accuracy of the list; no recognised amount is affected.
Our workings
The 2024 list showed [company] at [n]% with footnote 7 giving the same [n]% economic interest. The 2025 list shows [n]%, the figure for [company] in the line above, while footnote 7 now says [n]%. The 2024 list included the Company [place] S.R.L. (dormant), keyed to [place]; the 2025 list has no [place] company but keeps the [place] address in the key, so either the company was dissolved in 2025 and the key was not updated, or it was left out.
Management’s best defence, and our reply
The company may say [n]% is the voting interest that gives significant influence over the [name] group, and that the [place] company was dissolved during 2025 so its absence is correct. Neither changes any recognised amount. However, the footnote to the same row states a [n]% economic interest and last year's list used the economic figure, and a dissolved company leaves no reason to keep its address in the key.
The fix
- Show '[company] ([n]%)'; delete the [place] key entry, or reinstate the Company [place] S.R.L. if it existed at [date].
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2025 list shows [company] at [n]% | Document | Annual Report 2025, page 271 |
| 2 | footnote 7 to the same row gives a [n]% economic interest | Document | Annual Report 2025, page 272 |
| 3 | 2024 list showed [company] at its economic interest, [n]% | Document | Annual Report 2024, page 253 |
| 4 | the 2025 address key still gives a [place] registered office | Document | Annual Report 2025, page 272 |
| 5 | the 2024 list included a dormant [place] subsidiary keyed to [place] | Document | Annual Report 2024, page 253 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- Africa, Asia, [name] and Other Americas
- What is missing
- an [place] company keyed to the [place] address
- Pages looked at
- p.270-273 (whole list and address key)
- Result
- '[place]' and '[place]' hit only the address key on p.272 (the [place] entry itself); 'the Company [place]' has no hit; 'S.R.L.' hits no [place] company.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.