7.03 Four drafting slips in the group notes on tax, property, receivables and net debt
UK Company A · a UK-listed medical technology group · Drafting slip
In brief
Four slips in the notes change no figure but read wrongly: a sentence on the Pillar Two exception drops words, a sentence on the [place] site is garbled, the expected credit loss rates are printed as negative percentages, and the net debt definition leaves out two items that the net debt table includes.
The evidence, as filed
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 225; Annual Report 2024, page 207. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
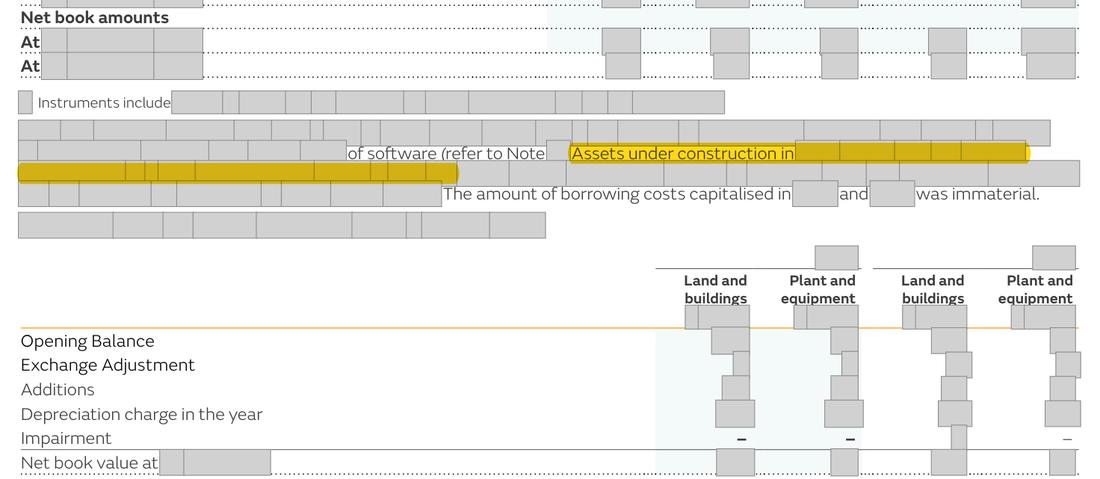
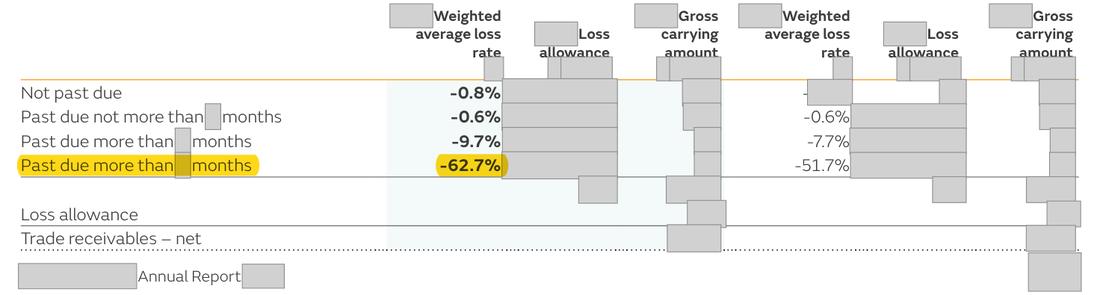
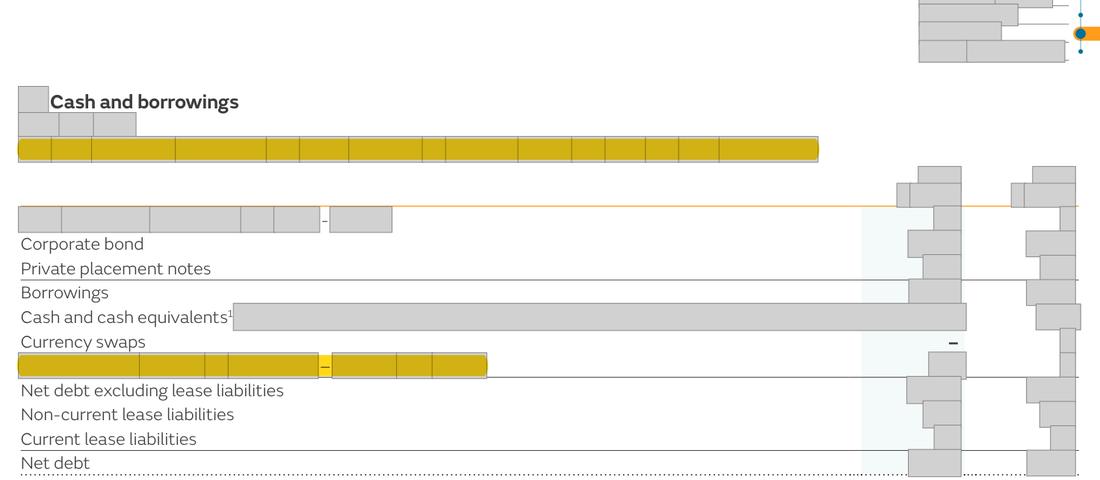
| What the annual report shows Note 5: '[wording masked]'. Note 7: 'Assets under construction in 2025 [wording masked] [place], UK.' Note 13: loss rates printed with a minus sign (for example -[n]% for receivables more than 6 months past due). Note 15, [wording masked]', while the table also deducts interest rate swap balances and adds lease liabilities. | What the rule requires Note 5: '[wording masked]' (the 2024 wording). Note 7: 'Assets under construction in 2025 reflect [wording masked] [place], UK.' Note 13: loss rates shown as positive percentages. Note 15.1: a definition that names interest rate swap balances and lease liabilities, or a separate definition of 'net debt excluding lease liabilities'. |
Why it matters
No figure changes; the slips weaken the reading of audited notes.
Exposure
None.
Our workings
Each slip is a wording, sign or definition label. The Pillar Two sentence in the 2024 report read '[wording masked] 2025 sentence lost those words. The loss rates are allowance divided by gross amount, a positive ratio; the minus sign is presentation only and was also used in the 2024 report. The net debt definition is unchanged from 2024, but the table it introduces includes an interest rate swap asset and lease liabilities that the definition does not mention.
Management’s best defence, and our reply
Management would say none of the slips changes a figure and that the meaning of each is clear from the context and the tables. That is right, which is why they are listed as drafting slips only. However, each appears in audited notes and is easily corrected.
The fix
- Correct the four sentences and the sign in the next report as set out in the should-be column.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Slip 1: words missing after 'arising' | Document | Annual Report 2025, page 225 |
| 2 | The 2024 sentence as it should read | Document | Annual Report 2024, page 207 |
| 3 | Slip 2: garbled sentence on assets under construction | Document | Annual Report 2025, page 229 |
| 4 | Slip 3: loss rates printed as negative percentages (image shows -[n]%) | Document | Annual Report 2025, page 237 |
| 5 | Slip 4: definition omits interest rate swaps and lease liabilities | Document | Annual Report 2025, page 239 |
| 6 | The table includes interest rate swap balances not named in the definition | Document | Annual Report 2025, page 239 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.