4.03 The Financial review calls restructuring charges 'cash outflows' and so reports a fall in restructuring cash that did not happen
UK Company A · a UK-listed medical technology group · Presentation point
In brief
The cash flow section of the Financial review says that in 2024 cash generated from operations was struck after paying out [amount] of restructuring and rationalisation expenses. The next paragraph says that in 2024 [wording masked] [amount], a significant reduction from [amount] in 2023. The [amounts] are the income-statement charges, not cash; the cash paid was [amount] in 2024 and [amount] in 2023, so restructuring cash outflows rose rather than fell.
The evidence, as filed
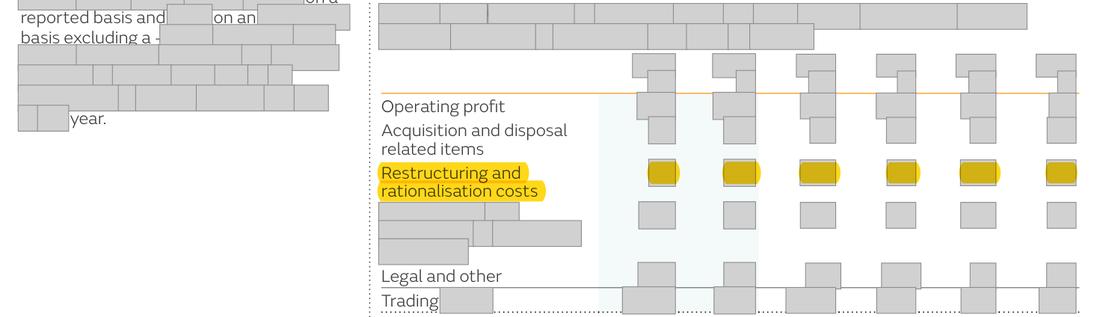
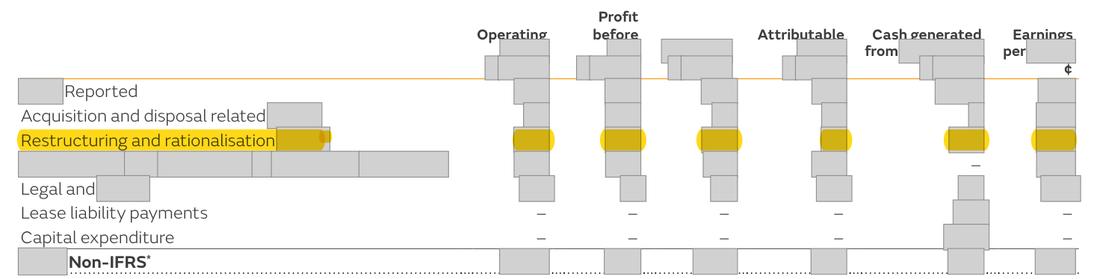
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 23; Annual Report 2024, page 25. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 'In 2024, [wording masked] [amount] ... a significant reduction from 2023 [wording masked] [amount]', beside '[amount] after paying out [amount] of restructuring and rationalisation expenses' | What the rule requires Either 'restructuring costs (charge) of [amount] (2023: [amount])', as the 2024 Annual Report worded it, or cash outflows of [amount] (2023: [amount]), an increase of [amount] |
The rule
Companies Act 2006, section 414C(3)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
The review required is a balanced and comprehensive analysis of— (a)the development and performance of the company’s business during the financial year, and (b)the position of the company’s business at the end of that year
Why it applies here: an editing slip that turns a correct statement about charges into an incorrect statement about cash, in the paragraph that explains [wording masked].
Why it matters
A reader using the Financial review to understand the cash cost of the [n]-Point Plan restructuring is told cash outflows fell sharply in 2024 when they rose, in the paragraph that explains the free cash flow step-up.
Exposure
Narrative inconsistency in prior-year commentary; no figure in the accounts is affected.
Our workings
on the same page, the 2024 restructuring and rationalisation cash paid is given as [amount], and the 2024 Annual Report gave the 2023 cash paid as [amount]. The trading profit reconciliation in the Financial review gives restructuring and rationalisation costs of [amount] for 2024 and [amount] for 2023, and the adjusted-measures reconciliation gives the 2024 charge as [amount] against cash of [amount]. The 2024 Annual Report's own version of this paragraph said 'restructuring costs totalled [amount]' and '2023 ... restructuring costs were [amount]'; the 2025 report changed 'costs' to 'cash outflows' without changing the figures.
the sentence understates 2024 cash outflows by [n] - [n] = [n] and overstates 2023 cash outflows by [n] - [n] = [n]; on a cash basis the outflow rose by [n] - [n] = [n] rather than falling by [n].
| Measure | 2023 [currency]m | 2024 [currency]m | Movement |
|---|---|---|---|
| Charge (trading profit reconciliation), called 'cash outflows' | [n] | [n] | [n] - [n] = -97 (shown as a significant reduction) |
| Cash paid (cash flow commentary and adjusted-measures table) | [n] | [n] | [n] - [n] = +[n] (an increase) |
| Difference, wording vs cash | [n] - [n] = [n] | [n] - [n] = -28 |
Management’s best defence, and our reply
Management could say the paragraph is intended to describe the restructuring programme's cost, that the cash paid is stated correctly one paragraph earlier on the same page, and that the adjusted-measures reconciliation gives both the charge and the cash, so a careful reader can work out the position. They could add that the [n]-to-2024 comparison is prior-year commentary. The answer: the sentence expressly says 'cash outflows' twice and draws a 'significant reduction' from them, which is the opposite of what the cash figures show, and the 2024 Annual Report's own wording ('costs') was correct, so the 2025 edit introduced the error.
The fix
- In the Annual Report 2026, describe the [amounts] as restructuring and rationalisation costs (the charge) and, where cash is discussed, use the cash paid ([amount] for 2024, [amount] for 2023).
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The same page gives 2024 restructuring and rationalisation cash paid as [amount] | Document | Annual Report 2025, page 23 |
| 2 | The next paragraph calls the [amount] charge a cash outflow | Document | Annual Report 2025, page 23 |
| 3 | The 2023 charge of [amount] is also called a cash outflow, giving a 'significant reduction' | Document | Annual Report 2025, page 23 |
| 4 | Trading profit reconciliation: the [amount] (2024) and [amount] (2023) are the income-statement charges | Document | Annual Report 2025, page 20 |
| 5 | Adjusted-measures table for 2024: charge [amount] against [amount] in the cash generated from operations column | Document | Annual Report 2025, page 289 |
| 6 | The 2024 Annual Report gives 2023 restructuring cash paid as [amount] | Document | Annual Report 2024, page 25 |
| 7 | The 2024 Annual Report's version of the same sentence spoke of costs, not cash outflows | Document | Annual Report 2024, page 25 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.