2.01 The 'relative importance of spend on pay' chart excludes the [amount] 2025 share buyback and says there were none
UK Company A · a UK-listed medical technology group · Compliance or disclosure gap
In brief
The remuneration report must compare spend on employee pay with distributions to shareholders by dividend and share buyback. The 2025 chart shows returns to shareholders of [amount], dividends only, with a footnote that there were [wording masked]. The company bought back shares for [amount] in 2025, so returns to shareholders were [amount].
The evidence, as filed
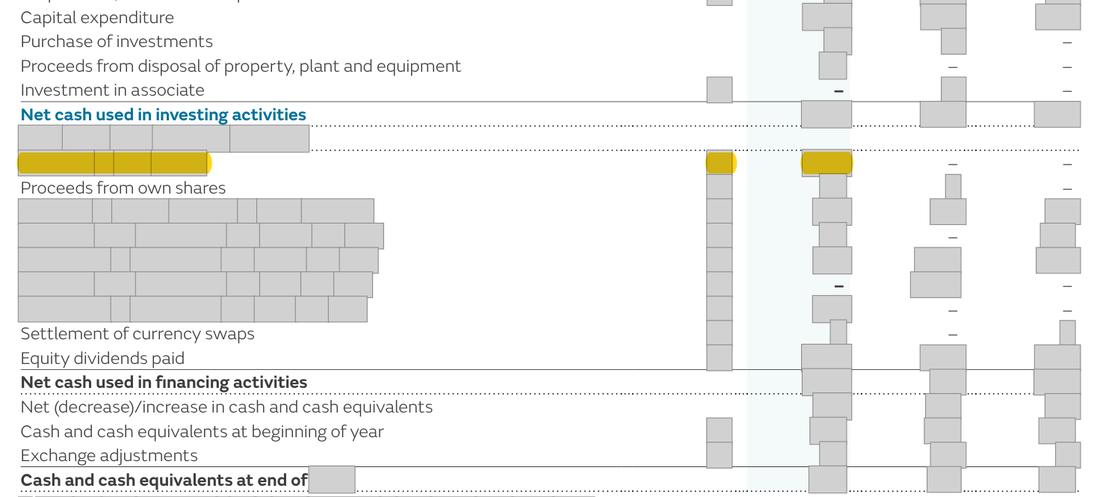
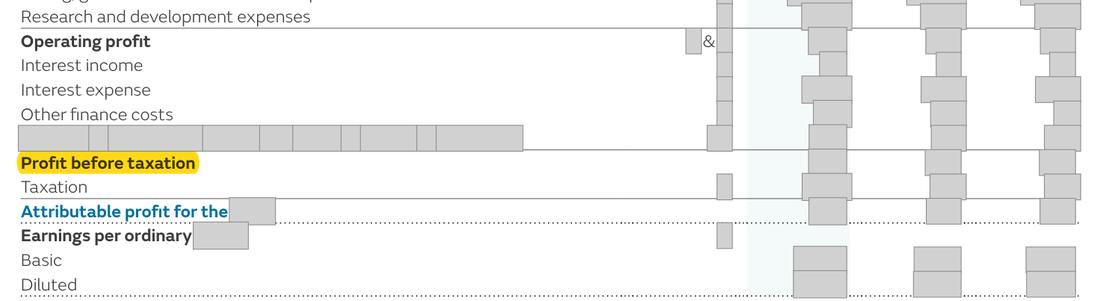
Further pages withheld to protect the company’s identity (three): Annual Report 2025, page 190; Annual Report 2024, page 168; Annual Report 2025, page 196. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Return to shareholders 2025: [amount] (2024: [amount]), footnoted '[wording masked]'. | What the rule requires Distributions by way of dividend and share buyback for 2025: [amount] dividends plus [amount] buyback = [amount], against [amount] in 2024, with the footnote removed. |
What we checked: Spend-on-pay chart and footnote; cash flow statement, statement of changes in equity and Directors' Report for the buyback; 2024 report's chart for the prior-year basis.
The rule
SI 2008/410 Schedule 8 para 20(1)(b)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
The directors' remuneration report must set out in a graphical or tabular form that shows in respect of the relevant financial year and the immediately preceding financial year the actual expenditure of the company, and the difference in spend between those years, on ... distributions to shareholders by way of dividend and share buyback
Why it applies here: the footnote, correct in the 2024 report (no buyback in 2023 or 2024), was carried forward unchanged, and the chart now misstates the item the Schedule requires; the year-on-year change in shareholder distributions it implies (+[amount]) should be +[amount].
Why it matters
- Shareholders voting on the 2025 remuneration report see pay compared with [amount] of distributions instead of [amount], and are told no buyback took place in a year when [amount] was spent on one.
- The footnote was right in 2024, when no shares were bought back, and was carried forward unchanged. The text above the chart also speaks of trading profit while the chart shows attributable profit.
Shareholders voting on the 2025 remuneration report see pay compared with [amount] of distributions instead of [amount], and are told no buyback took place in a year when [amount] was spent on one.
Exposure
A misstatement in a required Schedule 8 item is typically raised by the FRC by letter and corrected in the next report; it does not of itself require revision.
Our workings
the chart on page 190 shows returns to shareholders of [amount] (2024) and [amount] (2025) and footnotes that these are dividends [wording masked]'. The Group cash flow statement shows purchase of own shares of [amount] in 2025, the statement of changes in equity deducts [amount], and the Directors' Report describes a buyback for [amount] that concluded on [date].
distributions by dividend and buyback for 2025 were [n] + [n] = [n]; the chart understates them by [n] - [n] = [n], which is [n] / [n] = 64% of profit before tax.
The text above the chart also says it compares pay with 'trading profit', while the third panel is labelled attributable profit ([amounts]).
| Item | Computation | [currency]m |
|---|---|---|
| 2025 dividends (chart) | as printed | [n] |
| 2025 share buyback (cash flow statement) | as printed | [n] |
| Distributions by dividend and buyback 2025 | [n] + [n] = [n] | [n] |
| Difference (reported - correct) | [n] - [n] = -502 | -502 |
| Reported / correct / difference | reported [n]; correct [n]; difference -502 | -502 |
| As % of profit before tax | [n] / [n] = 64% | 64% |
| As % of the correct line | [n] / [n] = 60% | 60% |
| Change in distributions 2024 to 2025 | [n] - [n] = [n] | [n] |
Management’s best defence, and our reply
The Committee might say the chart is illustrative, that the buyback is fully reported in the Directors' Report, cash flow statement and note [n], and that a one-off capital return is not a recurring use of profit comparable with pay. It might add that the figures shown are themselves accurate dividend amounts. However, Schedule 8 names 'distributions to shareholders by way of dividend and share buyback' expressly, the chart's own footnote asserts there were no buybacks, and that assertion is contradicted by the company's own cash flow statement; disclosure elsewhere does not correct a wrong statement in the remuneration report.
The fix
- Show 2025 returns to shareholders as [amount] (dividends [amount], share buyback [amount]), delete the 'no share buybacks' footnote, and align the text with the profit measure shown.
Where: Directors' remuneration report, page 190: footnote to the relative importance of spend on pay chart
Proposed wording
Returns to shareholders comprise dividends to ordinary shareholders of [amount] and the share buyback of [amount] (2024: dividends of [amount]; no share buyback).
show the 2025 bar as [amount]
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The chart footnote states there were no buybacks | Document | Annual Report 2025, page 190 |
| 2 | Return to shareholders panel: [amount] (2024) and [amount] (2025) | Document | Annual Report 2025, page 190 |
| 3 | The text names trading profit; the third panel is attributable profit | Document | Annual Report 2025, page 190 |
| 4 | Third panel: attributable profit [amounts] | Document | Annual Report 2025, page 190 |
| 5 | Group cash flow statement: [amount] spent on the buyback in 2025 | Document | Annual Report 2025, page 213 |
| 6 | Directors' Report describes the 2025 buyback | Document | Annual Report 2025, page 196 |
| 7 | Group income statement line used for materiality | Document | Annual Report 2025, page 211 |
| 8 | Dividends of [amount] paid in 2025 | Document | Annual Report 2025, page 214 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.