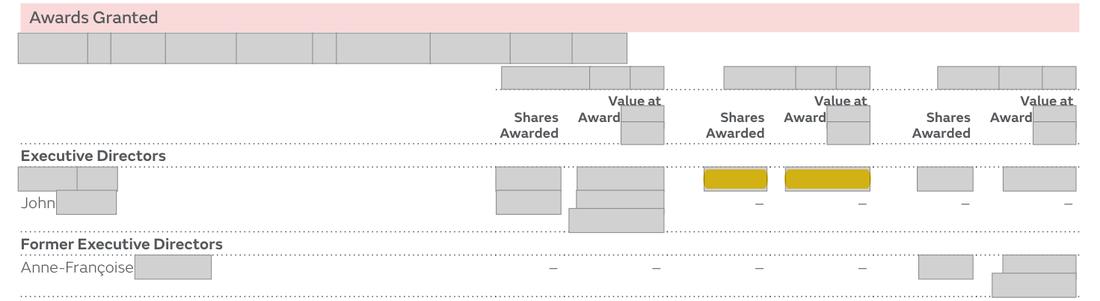
2.02 The table of awards granted in 2025 shows the Chief Executive's Restricted Share award at [n] shares ([amount]); the 2025 award was [n] shares
UK Company A · a UK-listed medical technology group · Compliance or disclosure gap
In brief
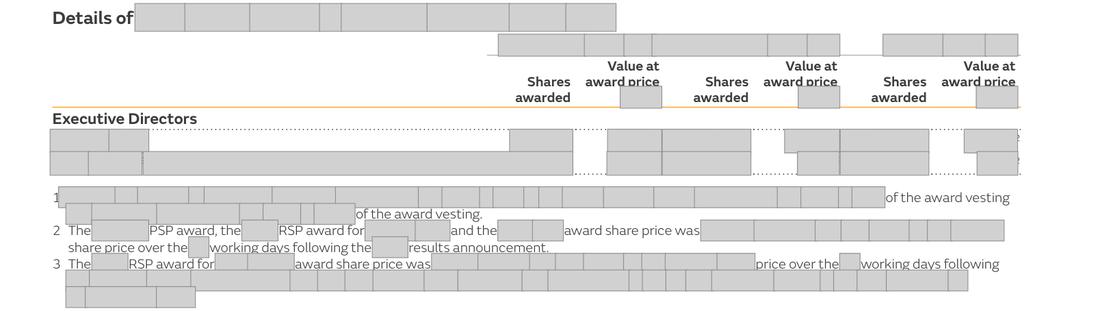
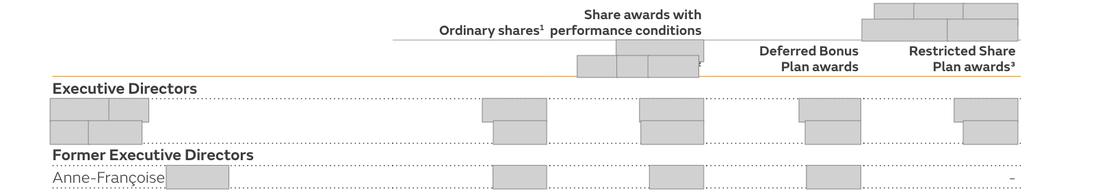
The remuneration report must give the face value of each scheme interest awarded in the year. It shows the Chief Executive's 2025 Restricted Share Plan award as [n] shares worth [amount]. The outstanding-awards table shows the 2025 award as three tranches of [n] shares ([n] shares, about [amount], in line with the policy's [n]% of salary). The printed [n] equals the 2025 award plus the [n]-share award made in [date].
The evidence, as filed
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 183; Annual Report 2025, page 176. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Awards granted during 2025, [name], Restricted Share Plan: [n] shares, value at award price [amount]. | What the rule requires [n] shares with a face value of about [amount] ([n] x [amount], consistent with the outstanding-awards table, the interests table and the [n]% of salary policy level. |
What we checked: Awards-granted table; outstanding share awards table; Executive Directors' interests table; award share price note; 2024 report's awards table; policy level for RSP awards.
The rule
SI 2008/410 Schedule 8 para 14(1)-(2)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
The directors' remuneration report must for each person who has served as a director of the company at any time during the relevant financial year contain a table setting out— (a)details of the scheme interests awarded to the person during the relevant financial year
SI 2008/410 Schedule 8 para 14(2)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
"face value" means the maximum number of shares that would vest if all performance measures and targets are met multiplied by either— (a)the share price at date of grant or (b)the average share price used to determine the number of shares awarded.
Why it applies here: the awards-granted table has added the [date] RSP award (already reported as a 2024 award) to the 2025 grant, so the required face value of the scheme interest awarded in 2025 is about twice its true amount.
Why it matters
- Shareholders voting on the remuneration report are told the Chief Executive received a 2025 restricted share award worth about twice what the outstanding-awards table and the policy show.
- The outstanding-awards table on the next page and the interests table agree with the smaller figure, so the error sits in one required table.
Shareholders voting on the remuneration report are told the Chief Executive received a 2025 restricted share award worth about twice what the outstanding-awards table and the policy show, a figure in a table the Schedule requires.
Exposure
A misstated Schedule 8 figure is normally corrected in the next report after an FRC or auditor query; it does not of itself require revision.
Our workings
the table of share awards granted during 2025 shows for the Chief Executive [n] Restricted Share Plan shares valued at [amount] at an award price of [amount]. The outstanding-awards table on the next page lists the 2025 award as three tranches of [n] shares dated [date], and the 2024 award as tranches of [n] shares dated [date]; the RSP total of [n] there agrees with the interests table. The 2024 report shows the 2024 award as [n] shares. Policy note: US executive directors [wording masked] [n]% of base salary; the Chief Executive's salary from [date] is [amount].
2025 award [n] x 3 = [n] shares; face value [n] x [n] = [n], about 123% of salary; the printed [n] = [n] + [n], i.e. the 2025 award plus the whole 2024 award; the printed face value overstates the 2025 award by [n] - [n] = [n] ([amount]s).
| Step | Computation | Result |
|---|---|---|
| 2025 RSP award (outstanding table) | [n] + [n] + [n] = [n] | [n] shares |
| 2024 RSP award (2024 report) | [n] x 3 = [n] | [n] shares |
| Printed figure reproduced | [n] + [n] = [n] | [n] shares |
| Correct face value ($) | [n] x [n] = [n] | [n] ([amount]s) |
| Printed face value ($) | [n] x [n] = [n] | [n] ([amount]s) |
| Reported / correct / difference ([amount]s) | [n] - [n] = [n] | [n] |
| Correct award as % of salary | [n] / [n] = 123% | policy [n]% |
| Interests table check | [n] + [n] + [n] = [n] | agrees |
| Difference in $ million | [n] / [n] = [n] | [n] |
| Reported in $ million | [n] / [n] = [n] | [n] |
| Correct in $ million | [n] / [n] = [n] | [n] |
| Difference (reported - correct), $ million | [n] - [n] = [n] | [n] |
Management’s best defence, and our reply
The company might say the column was intended to show all RSP shares granted under the new plan to date, or that the two awards relate to the first policy cycle and were presented together for transparency. It could add that every individual award appears correctly in the outstanding-awards table on the next page, so no reader is misled about the shares held. However, the table is headed '[wording masked] 2025', Schedule 8 asks for the scheme interests awarded during the year and their face value, and the 2024 award was granted on [date] and reported in last year's table; including it doubles the 2025 figure.
The fix
- Correct the 2025 awards table to [n] RSP shares with a face value of [amount], and show the 2024 award only in the 2024 comparative where relevant.
Where: Directors' remuneration report, page 182: [wording masked] 2025, Restricted Share Plan
Proposed wording
[name]: [n] shares; value at award price [amount]
the [date] award of [n] shares belongs in the 2024 table only
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Awards granted during 2025: RSP shown as [n] shares, [amount] | Document | Annual Report 2025, page 182 |
| 2 | Award price used for the face value | Document | Annual Report 2025, page 182 |
| 3 | Outstanding awards: the 2025 RSP award is three tranches of [n] shares | Document | Annual Report 2025, page 183 |
| 4 | The 2024 RSP award tranches of [n] shares | Document | Annual Report 2025, page 183 |
| 5 | Policy level for the RSP award | Document | Annual Report 2025, page 183 |
| 6 | Interests table: total RSP awards [n], consistent with a [n]-share 2025 award | Document | Annual Report 2025, page 184 |
| 7 | Chief Executive's salary from [date] ([amount]s) | Document | Annual Report 2025, page 176 |
| 8 | 2024 report: the 2024 RSP award of [n] shares | Document | Annual Report 2024, page 162 |
| 9 | Group income statement line used for materiality | Document | Annual Report 2025, page 211 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.