7.07 Note 5: registered office of the dormant [place] subsidiary not given (both years)
UK Company C · an AIM-quoted scientific instruments group · Drafting slip
In brief
Note 5 lists the Company ([place]) Limited ([place]), dormant and 100% held, but the address paragraphs give no registered office for it, as for every other subsidiary; the 2024 list had the same gap.
The evidence, as filed
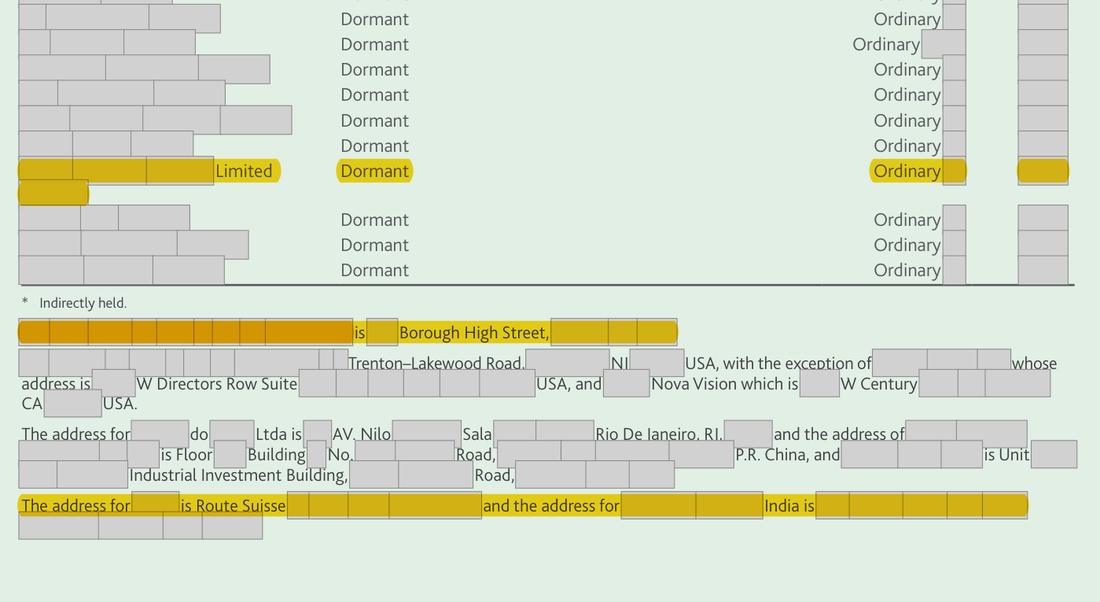
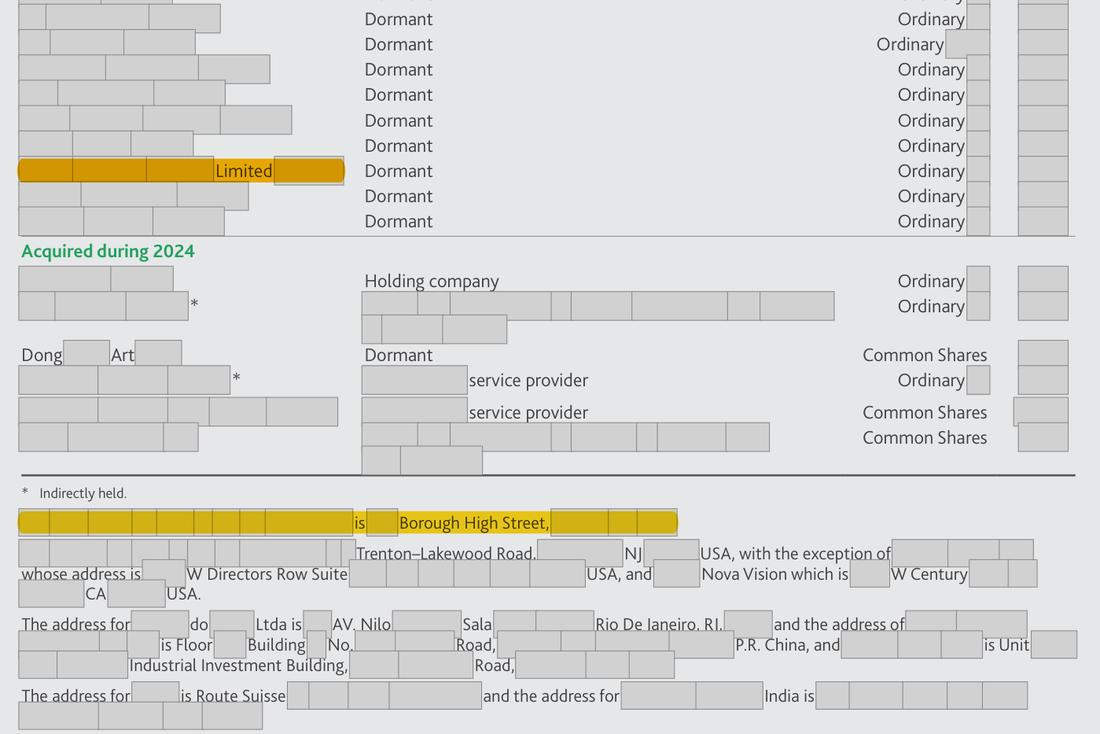
Annual Report 2024, page 105 · Prior year: The 2024 list also named the [place] subsidiary without giving its address.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows The Company ([place]) Limited ([place]) listed with no address. | What the rule requires The registered office address of the Company ([place]) Limited added to note 5. |
The rule
Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), Schedule 4, paragraph 1(3)(a); Companies Act 2006 s.409
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
There must be stated with respect to each subsidiary undertaking- (a) the address of the undertaking's registered office (whether in or outside the United Kingdom)
Why it matters
The list of subsidiaries is incomplete by one address.
Exposure
A drafting correction for the next accounts; no sanction.
Our workings
One missing particular for one dormant subsidiary in the related-undertakings list; the list is otherwise complete, so it is a drafting slip to correct in the next accounts.
Management’s best defence, and our reply
The company would say the [place] subsidiary is dormant, carries no assets of consequence and its details are on the [place] companies register, so the omission tells a reader nothing they need; the list otherwise follows the Schedule. However, the Schedule requires the registered office of each subsidiary undertaking with no materiality threshold, the only relief (where disclosure would be seriously prejudicial) has not been claimed, and the note gives addresses for every other overseas subsidiary, so the gap is an omission in both years rather than a choice.
The fix
- Add to note 5: 'The registered office of the Company ([place]) Limited is [address], [place].'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The [place] subsidiary is listed, 100% held | Document | Annual Report 2025, page 105 |
| 2 | Address paragraphs begin: UK subsidiaries | Document | Annual Report 2025, page 105 |
| 3 | The last address paragraph ends with India; no [place] address | Document | Annual Report 2025, page 105 |
| 4 | 2024 list: the [place] subsidiary again has no registered office address | Document | Annual Report 2024, page 105 |
| 5 | 2024 list: addresses are given for UK, US, [place], China, [place], [place] and India only | Document | Annual Report 2024, page 105 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [wording masked]
- What is missing
- the registered office address of the Company ([place]) Limited
- Pages looked at
- p.104-105 (note 5 list and addresses), p.69 (group general information), p.109 (company information)
- Result
- '[place]' hits only the company name in the list on this page; '[place]' hits this page (the country label in the list) and p.21 (Bank of [place] as a former lender); 'registered office' hits p.69 and p.109, both the parent company's own registered office; '[place]' has no hit.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.