7.06 Group notes: wrong note cross-references, a garbled row label and superseded accounting terms (the label and terms repeated in the 2025 report)
UK Company C · an AIM-quoted scientific instruments group · Drafting slip
In brief
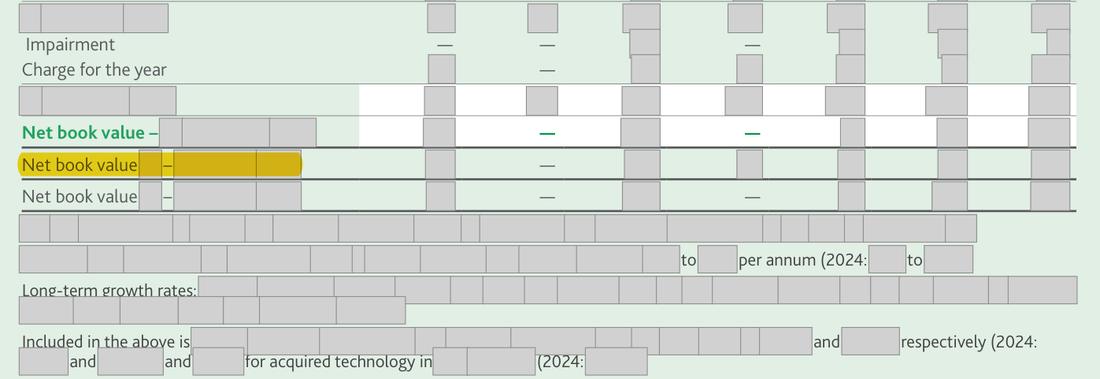
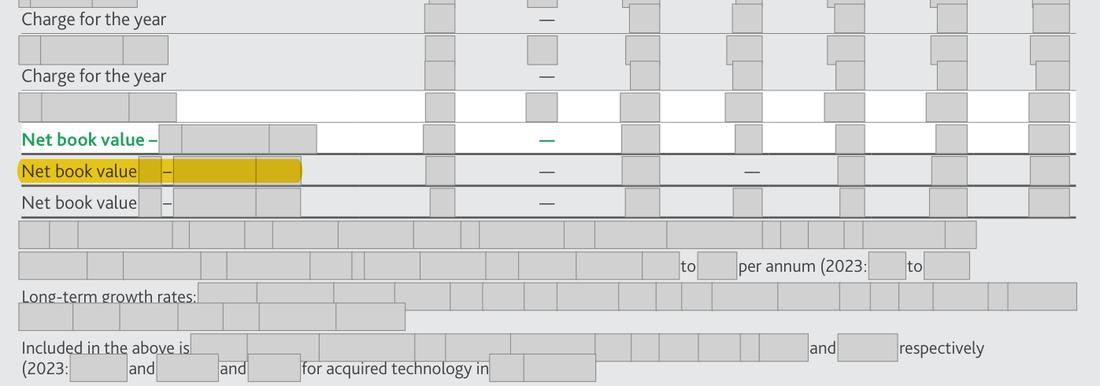
Slips in the 2024 group notes change no figure: the retirement-benefits estimate points to note 3 (segments) instead of note [n]; the share-premium paragraph points to note [n] (capital commitments) instead of note [n] (related parties); the intangibles table labels a row 'Net book value [n] - [date]'; the same swap fair-value line is called 'interest rate swaps' in note 4 and 'hedging contracts' in note 9; and the policies speak of the 'purchase method' and revenue at the 'fair value of consideration', terms replaced by IFRS 3 and IFRS 15. The 2025 report repeats the garbled label ('Net book value [n] - [date]') and both superseded terms.
The evidence, as filed
Further pages withheld to protect the company’s identity (six): Annual Report 2024, page 75; Annual Report 2025, page 71; Annual Report 2024, page 90; Annual Report 2024, page 79; Annual Report 2024, page 71; Annual Report 2024, page 72. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2024 report: 'See note 3' for retirement benefits; '(note [n])' for the share issue settling acquisition costs; row label 'Net book value [n] - [date]'; one line captioned two ways; 'purchase method' and 'fair value of consideration received or receivable'. 2025 report: 'Net book value [n] - [date]'; 'purchase method'; 'fair value of consideration received or receivable'. | What the rule requires 'See note [n]'; '(note [n])'; 'Net book value - [date]'; one caption for the swap line in notes 4 and 9; 'acquisition method' (IFRS 3) and revenue measured at the transaction price (IFRS 15) |
What we checked: Each slip read on the page image in the 2024 report and the repeated items in the 2025 report (pages 71 and 82); note headings on pages 75, 81, 89 and 98 of the 2024 report
Why it matters
Readers following the cross-references land on the wrong note, and outdated terms suggest the policies were not refreshed for current standards.
Exposure
Drafting only; no figure affected.
Our workings
each item is shown in the evidence rows. The pension note is note [n] and note 3 is the segmental analysis; note [n] is capital commitments, while the share issue in settlement of the introduction fee is described in note [n]. The 2025 report keeps the 'purchase method' and 'fair value of consideration' wording and the garbled 'Net book value [n] - [date]' label.
Management’s best defence, and our reply
The finance team would say these are cosmetic and no reader is misled on any amount. That is right, which is why they are listed only as drafting slips to correct in the next report.
The fix
- Correct the two cross-references to notes [n] and [n], fix the row label, use one caption for the swap line in notes 4 and 9, and update the policy wording to 'acquisition method' and 'transaction price' in the 2026 report.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The retirement-benefits estimate refers to note 3, which is the segmental analysis | Document | Annual Report 2024, page 75 |
| 2 | The share-premium paragraph refers to note [n] | Document | Annual Report 2024, page 90 |
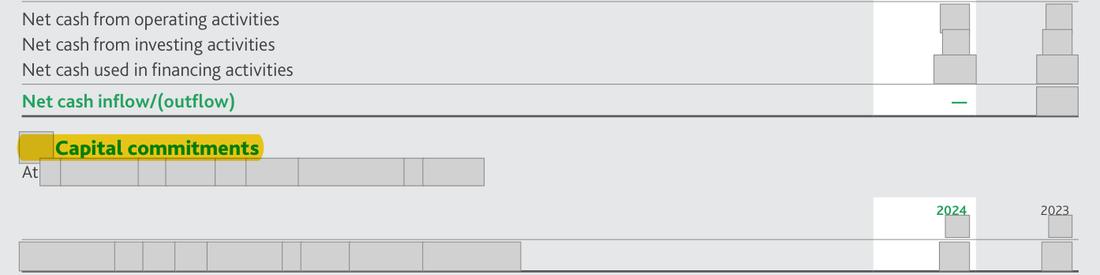
| 3 | Note 32 is capital commitments; the share-settled introduction fee is in note [n] | Document | Annual Report 2024, page 98 |
| 4 | Garbled row label in the intangible assets table | Document | Annual Report 2024, page 81 |
| 5 | Note 4 calls the swap fair-value line 'interest rate swaps' | Document | Annual Report 2024, page 77 |
| 6 | Note 9 calls the same finance-cost line 'hedging contracts' | Document | Annual Report 2024, page 79 |
| 7 | Superseded term: IFRS 3 calls it the acquisition method | Document | Annual Report 2024, page 71 |
| 8 | Superseded wording: IFRS 15 measures revenue at the transaction price | Document | Annual Report 2024, page 72 |
| 9 | 2025 policy still uses the superseded term 'purchase method' | Document | Annual Report 2025, page 71 |
| 10 | 2025 revenue policy keeps the pre-IFRS 15 wording | Document | Annual Report 2025, page 71 |
| 11 | Garbled row label repeated in the 2025 intangible assets table | Document | Annual Report 2025, page 82 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.