5.02 Shares bought for the reward scheme: the directors' report gives none of the particulars required when a company buys its own shares
UK Company C · an AIM-quoted scientific instruments group · Regulator-style question
In brief
The Company announced that on [date] it acquired [n] of its own shares and allocated them at once to employees under its reward scheme; the group and parent statements of changes in equity show a '[wording masked]' of [amount]. The directors' report gives no number, nominal value, consideration, percentage of capital or reasons for the purchase, which the law requires where a public company buys its own shares. The 2025 report is silent in the same way about the [n] and [n] shares bought in May and [date].
The evidence, as filed
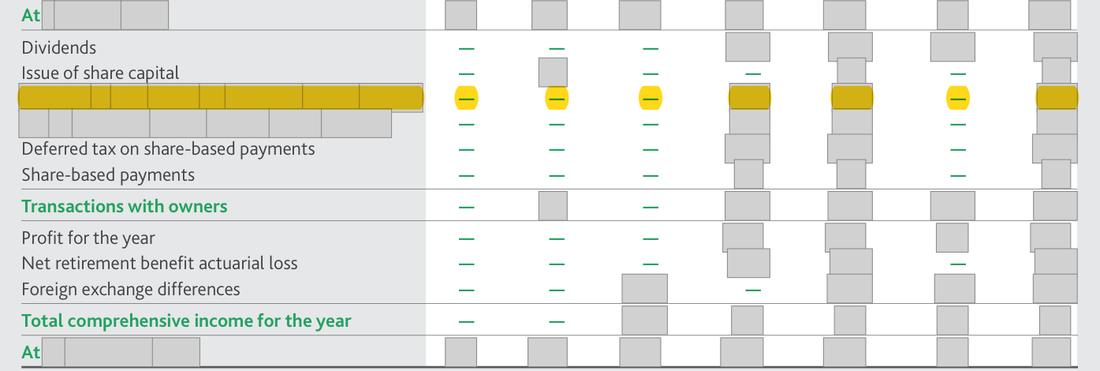
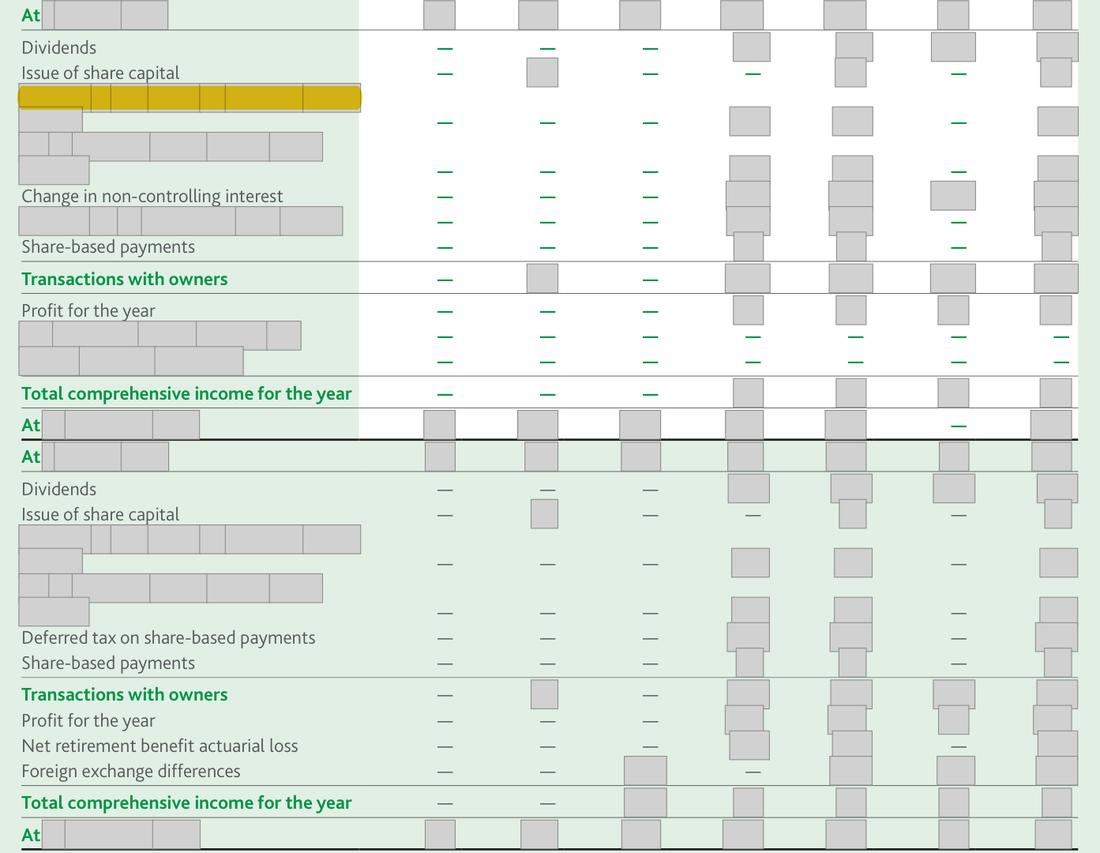
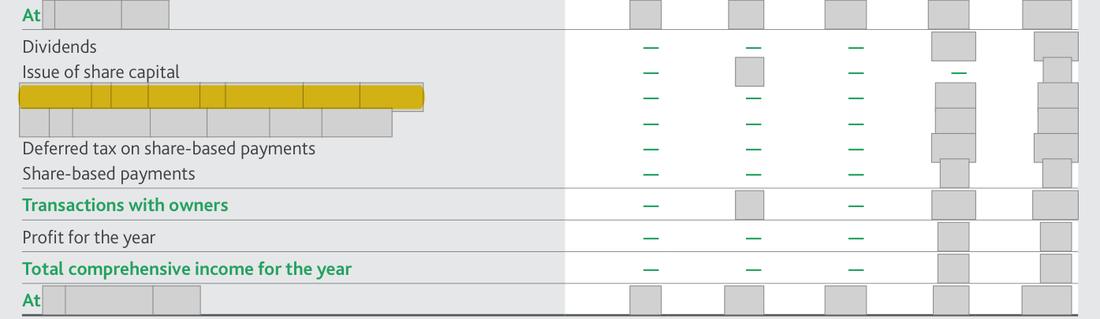
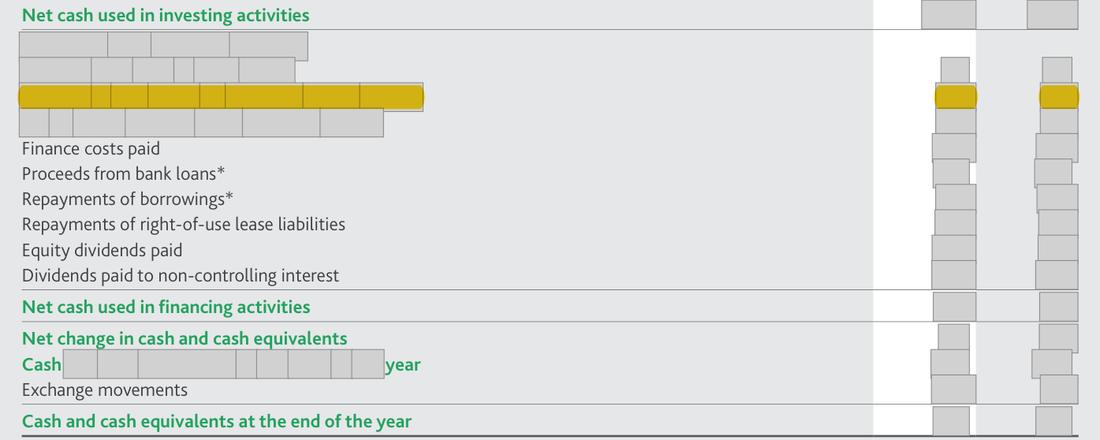
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 56; Annual Report 2024, page 56. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Statements of changes in equity and cash flow: '[wording masked]' ([n]) in 2024 and 2023; directors' report (pp.56-57): no own-share disclosure. | What the rule requires If the Company was the purchaser: the number and nominal value of shares bought, the consideration paid, the percentage of called-up capital and the reason, in the directors' report; if a trustee or broker bought the shares for employees, a note saying so. |
The rule
SI 2008/410 Schedule 7 Part 2 paragraph 9(a) and (e)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
(a) the number and nominal value of the shares so purchased, the aggregate amount of the consideration paid by the company for such shares and the reasons for their purchase
Why it applies here: the parent company's own equity statement records the purchase, which points to the Company as the purchaser; but the shares may have been bought through a broker or trustee for the employees, in which case Part 2 would not apply.
Why it matters
If the Company was the purchaser, members are not told in the directors' report how many shares were bought, at what cost and why, as the law requires for every purchase of own shares, however small.
Exposure
None while the point is a question; if the Company was the purchaser, the particulars would be added in the next directors' report.
Our workings
the regulatory announcement of [date] says that on [date] the Company 'acquired [n] ordinary shares of [amount] each' at [amount] and that they '[wording masked]'. The group and the parent company statements of changes in equity both carry a line '[wording masked]' of ([n]), and the group cash flow shows the same outflow. Similar announcements in May and [date] report [n] and [n] shares. The directors' reports of both years say nothing about these purchases.
[n] shares at [amount] cost about [amount], so the amount is small. Law: where shares in a public company are purchased by the company, the directors' report must state the number and nominal value of the shares purchased, the consideration and the reasons, with the percentage of called-up capital (Schedule 7 Part 2 paragraph 9).
Only the Company can say which, so this is put as a question.
| Item | Figure | Working |
|---|---|---|
| Price per share | [amount] | [amount] / [n] = [amount] |
| Cost of [n] shares, [date] | [amount] | [n] x [n] = [n] |
| As % of 2024 profit before tax | 1% | [n] / [n] = 1% |
Management’s best defence, and our reply
The Company may say the shares were bought in the market by its broker or the scheme trustee on behalf of the employees, so that the Company never held them and Part 2 of Schedule 7 does not apply. It may add that the amount is trivial, that the purchases were announced to the market at the time, and that the statements of changes in equity and cash flow show them. The answer: the announcement says the Company 'acquired' the shares and the parent company's own equity statement records a purchase of own shares, which points the other way; an announcement outside the report does not complete the directors' report, and Part 2 has no size threshold. Because the legal form of the purchase is not shown in the report, the point is put as a question.
The fix
- Add to the directors' report: 'During the year the Company purchased [654] ordinary shares of [amount] each (nominal value £[33]; [0.01]% of called-up share capital) for £[74,[n]] [wording masked]; the shares were transferred to employees.'
Question for the company
Did the Company itself purchase the [n] shares on [date] (and the [n] and [n] shares in May and [date]) before allocating them to employees, under what shareholder authority, and if so why does the directors' report not give the particulars required for a company acquiring its own shares?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The Company announced that it acquired [n] of its own shares | Document | |
| 2 | the purpose of the purchase: [wording masked] | Document | |
| 3 | group statement of changes in equity records the purchase of own shares in 2024 (and 2023) | Document | Annual Report 2024, page 69 |
| 4 | the parent company's own statement of changes in equity records the purchase, pointing to the Company as purchaser | Document | Annual Report 2024, page 101 |
| 5 | the group cash flow shows the outflow | Document | Annual Report 2024, page 70 |
| 6 | the practice continued in 2025 | Document | |
| 7 | a second 2025 purchase | Document | |
| 8 | the 2025 group statement of changes in equity records the purchase again | Document | Annual Report 2025, page 67 |
Absence check
- Document
- Annual Report 2024
- Where it would appear
- Significant shareholders
- What is missing
- the number, nominal value, consideration, percentage of called-up capital and reasons for the shares the Company bought for its reward scheme
- Pages looked at
- Annual Report [amount].56-57 (directors' report), p.52-55 (remuneration report), p.90 (share capital note)
- Result
- 'purchase of own' and 'reward scheme' hit only the statement of changes in equity and cash flow lines (p.69, [n]), which give an amount but no number, nominal value or reason. 'nominal value' hits p.71 and [n] (merger reserve policy). 'called up' hits p.90 and [n] (share capital note and parent balance sheet), which deal with shares issued, not bought. '[n]' and 'market purchase' have no hits.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.