4.07 The segment assets in the results announcement differ from the audited report, although the market was told nothing had changed
UK Company C · an AIM-quoted scientific instruments group · Regulator-style question
In brief
The unaudited preliminary results announcement of [date] gave segment assets of [amount] ([segment]), [amount] ([segment]) and [amount] (Head office). The audited report approved on [date] gives [amounts] for the same date, and its 2024 comparatives differ from the announcement too. The confirmation announcement of [date] told the market 'There [wording masked] [date]'. Totals are the same, so the question is which split is right and why the change was not mentioned.
The evidence, as filed
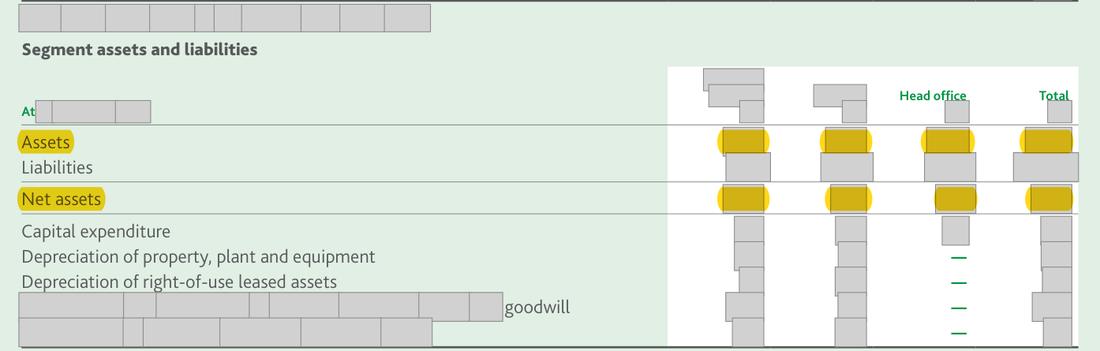
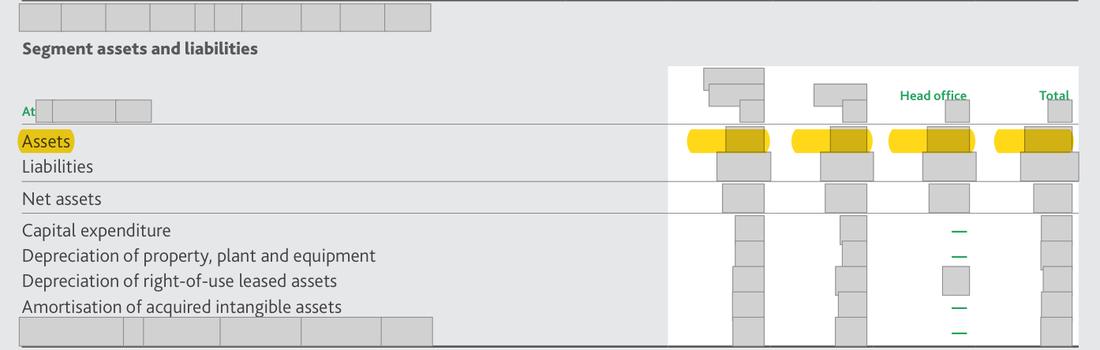
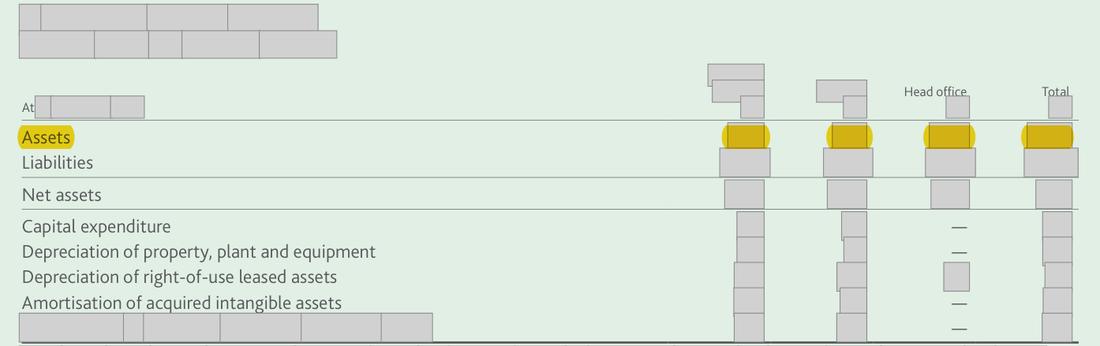
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Announcement, [date] segment assets: [n] / [n] / [n] (total [n]); audited report: [n] / [n] / [n] (total [n]). Announcement 2024 comparatives [n] / [n] / [n] against [n] / [n] / [n] in both the 2025 report and the 2024 report as published. Confirmation: no changes to the results. | What the rule requires The announcement's segment table agreeing with the audited note (and with the 2024 report for comparatives), or the confirmation announcement stating which figures changed after the audit and why. |
The rule
IFRS 8 Operating Segments paragraph 23 (measure of segment assets reported to the chief operating decision maker)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
A measure of profit or loss must be reported for each reportable segment, and segment assets and liabilities where they are regularly given to the chief operating decision maker.
Why it applies here: the statements of profit, the balance sheet totals and the earnings per share did not change, so 'results' in the narrow sense did not change; but the announcement's segment table, which included restated-looking 2024 comparatives that the audited report does not use, was replaced after the audit without the market being told.
Why it matters
Investors who used the announcement's segment balance sheet (for example to judge capital employed by segment) held figures the audited report does not support, after being told nothing had changed; the totals and profits were unaffected.
Exposure
A question on the accuracy of a market announcement; the audited report is not affected. A correcting statement in the next results announcement would answer it.
Our workings
the preliminary results announcement of [date] (unaudited) prints a segment assets and liabilities table: 2025 assets [n]; net assets [n]; 2024 assets [n]. Segment note 3 of the audited 2025 report (pp.75-76) prints 2025 assets [n], net assets [n], ([n]) and [n], and 2024 assets [n], the last agreeing with the 2024 report as published. The [date] announcement says the full financial statements were approved on [date] and 'There [wording masked] [date]'.
the segment allocation moved by up to [n] (Head office net assets [n] to ([n])) while every total stayed the same (workings).
| Segment assets, [date] (£m) | Announcement | Audited report | Difference |
|---|---|---|---|
| [segment] | [n] | [n] | [n] - [n] = [n] |
| [segment] | [n] | [n] | [n] - [n] = [n] |
| Head office | [n] | [n] | [n] - [n] = -[n] |
| Head office net assets | [n] | ([n]) | -[n] - [n] = -[n] |
| Segment assets, [date]: [segment] | [n] | [n] | [n] - [n] = -[n] |
| Segment assets, [date]: [segment] | [n] | [n] | [n] - [n] = [n] |
| Segment assets, [date]: Head office | [n] | [n] | [n] - [n] = [n] |
Management’s best defence, and our reply
The company can say that the 'results' are the income statement, earnings per share and the balance sheet totals, none of which changed, and that segment assets are a secondary allocation of head-office items (goodwill, borrowings, deferred tax) that was refined during the audit. It can add that the preliminary announcement was clearly labelled unaudited and that the audited note is the authoritative figure. That is a fair reading of 'results', which is why this is a question; however, the announcement printed a full segment balance sheet, its 2024 column did not match the company's own published 2024 note, and a sentence in the confirmation would have cost nothing.
The fix
- Tie the announcement's notes to the audited note before release; where the audit changes any table, say so in the confirmation (for example: 'The segment analysis of assets and liabilities in note 3 has been updated; the totals and the results are unchanged').
Question for the company
Which segment split of assets and liabilities at [date] and 2024 is correct, why did the preliminary results announcement give different figures (including 2024 comparatives that differ from the 2024 report), and why did the confirmation announcement not mention the change?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Announcement: 2025 segment assets | Document | |
| 2 | Announcement: 2025 segment net assets | Document | |
| 3 | Announcement: 2024 segment assets | Document | |
| 4 | The market was told the audited accounts changed nothing | Document | |
| 5 | Audited 2025 segment assets | Document | Annual Report 2025, page 75 |
| 6 | Audited 2025 segment net assets | Document | Annual Report 2025, page 75 |
| 7 | Audited 2024 comparative segment assets | Document | Annual Report 2025, page 76 |
| 8 | The 2024 report as published: the same split as the 2025 report, not the announcement's | Document | Annual Report 2024, page 76 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.