1.10 Financial instruments note calls the earn-out reversal finance income and the hedging gain interest income, while notes 5 and 9 put both in operating costs
UK Company C · an AIM-quoted scientific instruments group · Presentation point
In brief
Note 24 says finance income from contingent acquisition consideration totalled [amount] and interest income from in-the-money derivatives [amount]. Notes 5 and 9 show the [amount] earn-out reversal and the [amount] hedging-contract gain inside operating costs, with nothing for contingent consideration in interest. The [amount] fair value loss on interest rate swaps, charged in finance costs, is not mentioned in note [n]'s account of fair value gains and losses.
The evidence, as filed
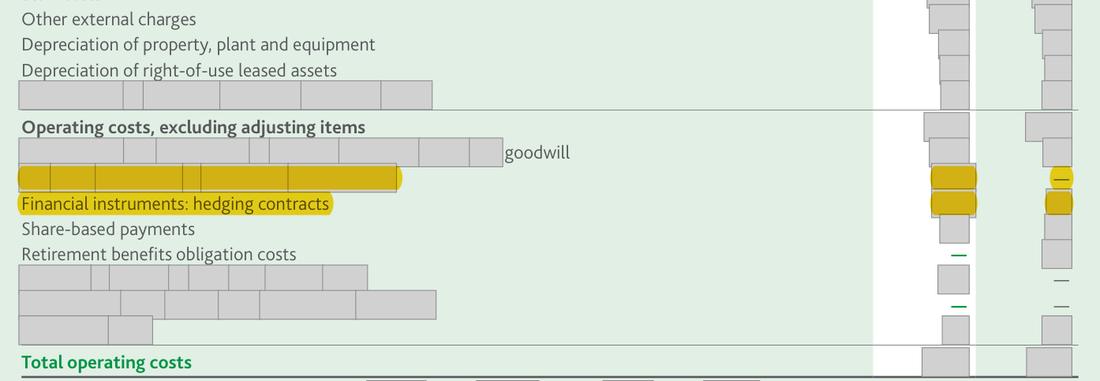
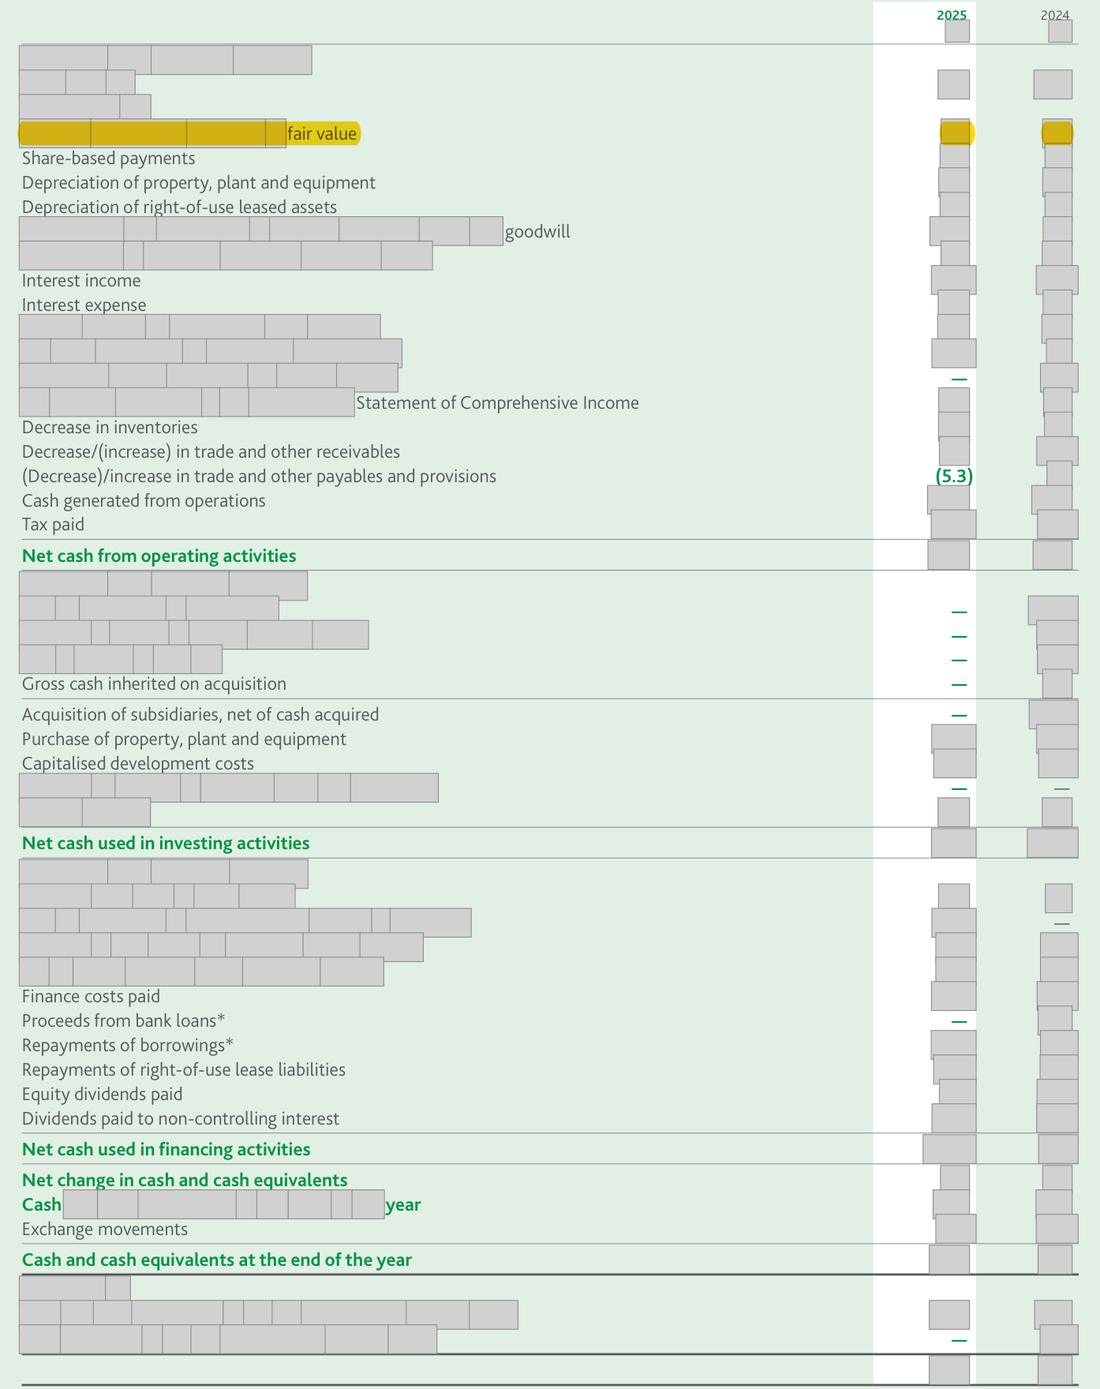
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 92; Annual Report 2025, page 79. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Note 24: finance income of [amount] on contingent consideration and interest income of [amount] on derivatives. Note 9: contingent consideration nil in 2025 and interest rate swaps ([n]). Note 5: [wording masked] ([n]) and hedging contracts ([n]) within total operating costs. | What the rule requires Note 24 describes each fair value through profit or loss gain or loss where the income statement records it: the [amount] credit and the [amount] hedging gain within operating costs, and the [amount] swap loss within finance costs, a net loss of [amount] on derivatives. |
The rule
IFRS 7 Financial Instruments: Disclosures, paragraph 20(a)(i)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Gains and losses on financial assets and liabilities at fair value through profit or loss must be disclosed, on the face of the statements or in the notes.
Why it applies here: the amounts are recorded correctly in the primary statements, but note [n] labels them as finance and interest income and leaves out the swap loss, so the note and the income statement notes disagree.
Why it matters
A reader of note [n] would place a [amount] credit below operating profit and would not learn of the [amount] swap loss, while the income statement notes show the opposite; the operating profit and adjusted measures are read on the basis of where these items sit.
Exposure
Presentation inconsistency within the notes; the primary statements are not affected.
Our workings
note [n] (page 92) gives finance income of [amount] from contingent acquisition consideration and interest income of [amount] from in-the-money derivatives. Note 9 (page 79) shows nil for [wording masked] in 2025 and a [amount] charge for interest rate swaps in net interest expense. Note 5 (page 77) shows the [amount] credit and the [amount] hedging gain within total operating costs, and the cash flow statement adds back [amount] for financial instruments measured at fair value.
the derivative result is a net loss of [n] less [n], or [amount], which agrees with the cash flow add-back; the [amount] credit equals [n]% of statutory profit before tax (workings).
| Item | Note 24 says | Notes 5 and 9 show |
|---|---|---|
| Earn-out reversal (contingent consideration) | finance income [n] | operating costs ([n]); interest nil |
| Foreign currency hedging contracts | interest income [n] | operating costs ([n]) |
| Interest rate swaps | not mentioned | interest expense ([n]) |
| Net result on derivatives at fair value | [n] income | -[n] + [n] = -[n] (cash flow add-back [n]) |
| Earn-out credit against statutory profit before tax | [n] / [n] = [n]% |
Management’s best defence, and our reply
The finance team would say the contingent consideration was a liability measured at fair value through profit or loss, so describing the gain as finance income in a financial instruments note is a loose label rather than a statement of where it is presented, and notes 4, 5 and 9 show the presentation correctly; the swap loss is visible in note 9. However, the note gives the amounts as finance and interest income in terms that a reader will take literally, and its account of fair value results leaves out the largest one, so the notes contradict each other even though the primary statements are right.
The fix
- Reword note [n]: 'Gains on financial liabilities at fair [wording masked] the [amount] reversal of contingent acquisition consideration, are included in operating costs (note 5); net losses on derivatives of [amount] comprise a [amount] loss on interest rate swaps in finance costs (note 9) and a [amount] gain on currency options in operating costs.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Note 24 calls the [amount] credit finance income | Document | Annual Report 2025, page 92 |
| 2 | Note 24 calls the derivative gain interest income and gives no swap loss | Document | Annual Report 2025, page 92 |
| 3 | Note 9: nothing for contingent consideration in interest in 2025 | Document | Annual Report 2025, page 79 |
| 4 | Note 9: [amount] swap loss in net interest expense | Document | Annual Report 2025, page 79 |
| 5 | Note 5: the [amount] credit sits in total operating costs | Document | Annual Report 2025, page 77 |
| 6 | Note 5: the [amount] hedging gain sits in total operating costs | Document | Annual Report 2025, page 77 |
| 7 | Cash flow add-back equals the [amount] net derivative loss | Document | Annual Report 2025, page 68 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.