6.20 Four labels in the notes do not match the figures they head
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
The joint venture's 2024 result of [amount] is labelled 'Loss and total comprehensive expense' although it is a profit. The bond carrying amounts are headed '52 weeks ended' instead of a balance sheet date. The FVTOCI column of the financial instruments table is headed '£' instead of '£m', and one comparative in the hedging note reads '[amount] loss' with no unit.
The evidence, as filed
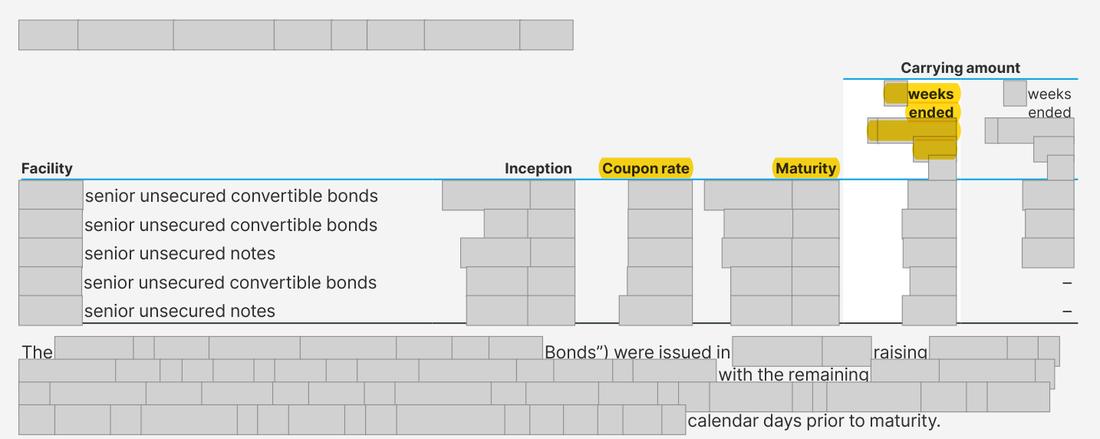
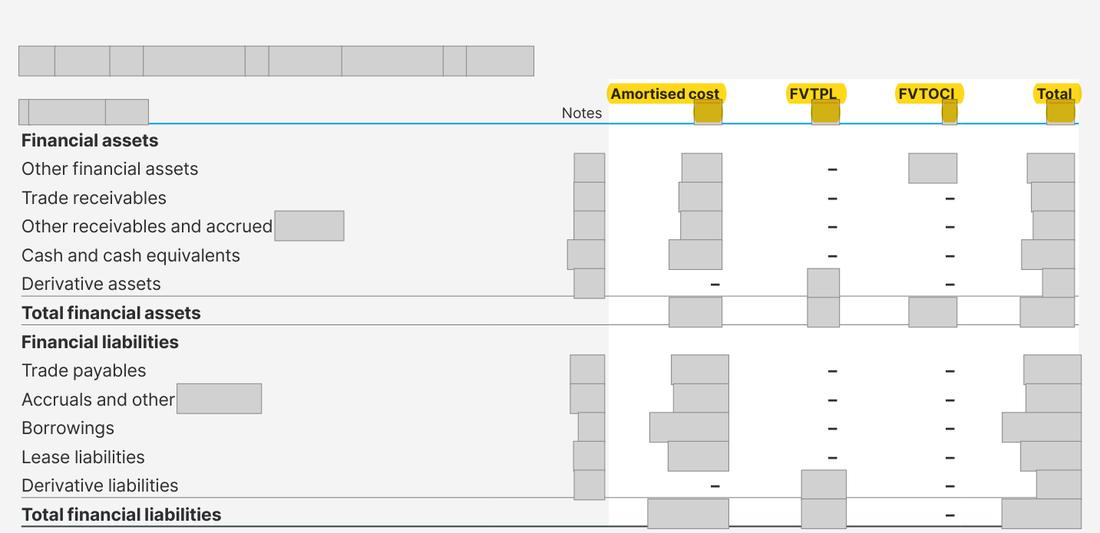
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 198; Annual Report 2024, page 209. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Joint venture note: '[wording masked]' over a profit of [amount]; borrowings note: carrying amounts under '52 weeks ended [date]'; financial instruments note: FVTOCI column in '£'; derivatives note: '(FY23: [amount] loss)'. | What the rule requires '[wording masked]'; 'At [date]'; '£m'; '(FY23: [amount] loss)'. |
Why it matters
None for the figures; the labels can mislead a reader scanning the tables.
Exposure
Drafting only.
Our workings
Each slip is a label or unit; the figures under them agree with the other notes and no reader decision turns on them.
Management’s best defence, and our reply
The finance team would say these are cosmetic and that each figure is clear from its context and from the other notes. That is right for the figures, which is why the point is only a drafting note; the labels should still describe what is shown.
The fix
- Relabel the four items as shown in the should-be column.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The 2024 result of [n] is a profit but is labelled a loss and an expense | Document | Annual Report 2024, page 198 |
| 2 | Carrying amounts at a date are headed as a 52-week period | Document | Annual Report 2024, page 207 |
| 3 | The FVTOCI column is headed in pounds, not pounds million | Document | Annual Report 2024, page 211 |
| 4 | The comparative omits the unit | Document | Annual Report 2024, page 209 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.