6.12 Drafting slips in the Audit Committee and remuneration reports
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
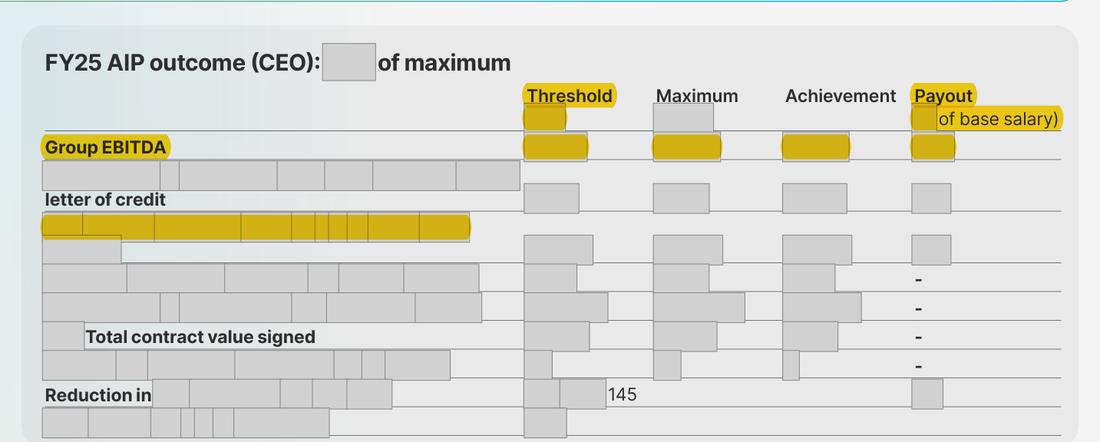
Ten slips: the Audit Quality Review is said to cover the 2023 Financial Statements on one page and the 2024 Annual Report on the next; the rolling non-audit fee percentages for FY23 and FY24 ([n]%, [n]%) differ from those printed last year ([n]%, [n]%) for the same fees; the bonus EBITDA maximum is [amount] on one page and [amount] on another; the at-a-glance bonus table heads its payout column '% of base salary' though its figures are '% of maximum', shows threshold as [n]% while another page says 25% vests at minimum, and reads '[platform] director operating costs'; 'Materials Controls Working Group'; 'commerically'; the CEO history table is introduced as the current and previous 10 years but covers 2016-2025; FY24 employee pay is printed '[n]'; and the CFO's [name] options are printed [n] with the same [amount] face value as the CEO's [n].
The evidence, as filed
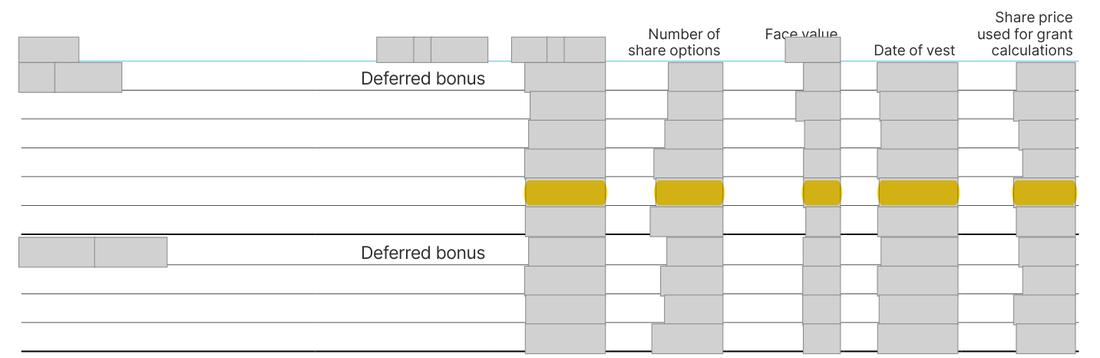
Further pages withheld to protect the company’s identity (17): Annual Report 2025, page 130; Annual Report 2024, page 123; Annual Report 2025, page 131; Annual Report 2024, page 180; Annual Report 2025, page 132; Annual Report 2024, page 129; Annual Report 2024, page 132; Annual Report 2025, page 145; Annual Report 2025, page 146; Annual Report 2024, page 141; Annual Report 2025, page 129; Annual Report 2025, page 141; Annual Report 2024, page 145; Annual Report 2025, page 151; Annual Report 2024, page 140; Annual Report 2025, page 156; Annual Report 2025, page 143. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows As listed in the evidence rows. | What the rule requires One AQR year; a note on the change in the rolling percentages; one EBITDA maximum; column heading '% of maximum'; one threshold vesting statement; 'Direct'; 'Material Controls'; 'commercially'; 'previous nine financial years'; '[n]'; the correct CFO option count ([n] if transposed). |
Why it matters
Small slips in governance reports reviewed by two committees; the [name] count is in an audited table.
Exposure
Drafting only.
Our workings
Each item is a label, year, spelling or digit slip confirmed on the page image; none changes an audited total. The [name] option count sits in an audited table and should be corrected.
Management’s best defence, and our reply
The company would say none of these slips affects any decision or any audited total, and that the AQR sentence refers to the same inspection described two ways. It would add that the rolling percentage is a voluntary chart statistic. That is right for most items, which is why they are drafting points; the [name] count is an audited figure and should be corrected.
The fix
- Correct each item as in the should-be cell; confirm the CFO's [name] option count from the option certificate.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | AQR: 2023 Financial Statements | Document | Annual Report 2025, page 130 |
| 2 | AQR: 2024 Annual Report - a different year | Document | Annual Report 2025, page 131 |
| 3 | Rolling non-audit fee percentages FY23 [n]%, FY24 [n]%, FY25 [n]% | Document | Annual Report 2025, page 132 |
| 4 | 2024 report: FY23 [n]%, FY24 [n]% for the same fees | Document | Annual Report 2024, page 123 |
| 5 | At a glance: maximum [amount] | Document | Annual Report 2025, page 135 |
| 6 | Audited AIP table: maximum [amount] | Document | Annual Report 2025, page 145 |
| 7 | Column heading says % of base salary; the total line says % of maximum | Document | Annual Report 2025, page 135 |
| 8 | At a glance shows [n]% at threshold | Document | Annual Report 2025, page 135 |
| 9 | AIP narrative says 25% vests at minimum | Document | Annual Report 2025, page 146 |
| 10 | 'director' for 'Direct' | Document | Annual Report 2025, page 135 |
| 11 | 'Materials' for 'Material' | Document | Annual Report 2025, page 129 |
| 12 | Spelling | Document | Annual Report 2025, page 141 |
| 13 | Table covers 2016-2025, the current and previous nine years | Document | Annual Report 2025, page 151 |
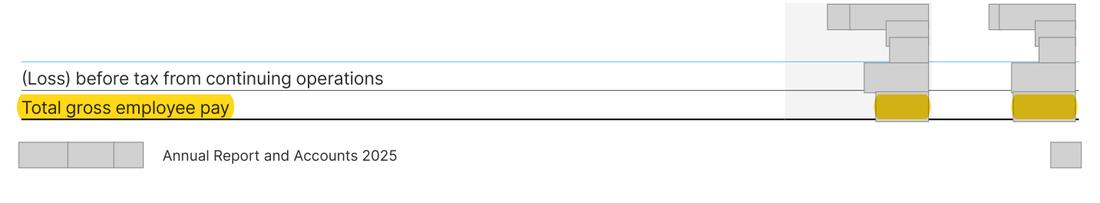
| 14 | '[n]' printed to two decimals | Document | Annual Report 2025, page 153 |
| 15 | CFO [name]: [n] options with the same face value as the CEO's | Document | Annual Report 2025, page 156 |
| 16 | CEO [name]: [n] options, same price and face value | Document | Annual Report 2025, page 156 |
| 17 | The basis the report gives for the non-audit fee measure: fees of the year against the average audit fee of the previous three years | Document | Annual Report 2024, page 123 |
| 18 | The 2024 report's chart prints [n]% for FY23 and [n]% for FY24 as the three-year rolling non-audit fee percentage | Document | Annual Report 2024, page 123 |
| 19 | Note 2.3: non-audit fees paid to the auditor were [n] (FY24) and [n] (FY23), in GBP million | Document | Annual Report 2024, page 180 |
| 20 | Note 2.3: audit fees were [n] (FY24) and [n] (FY23), in GBP million | Document | Annual Report 2024, page 180 |
| 21 | The column for the year ending [date] is headed 'Maximum potential for FY24' | Document | Annual Report 2024, page 129 |
| 22 | 2023 salaries of the directors who stepped down are shown as effective from [date] | Document | Annual Report 2024, page 132 |
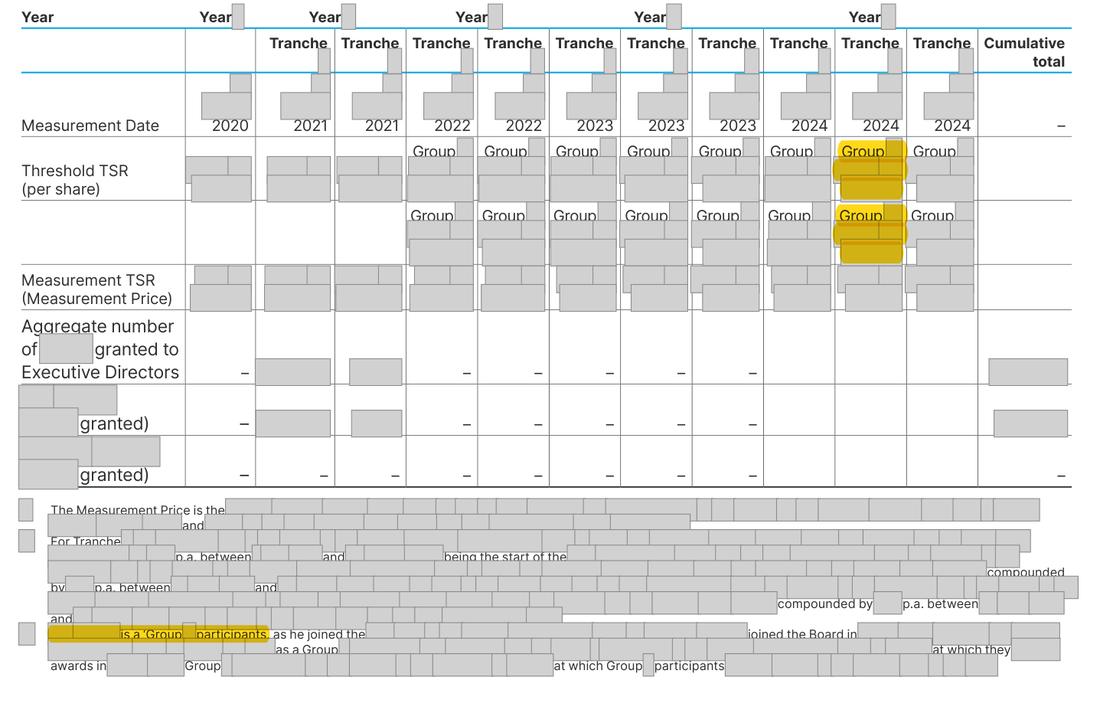
| 23 | Year 5, Tranche 2, Group 1 threshold: [amount] at [amount] per share | Document | Annual Report 2024, page 135 |
| 24 | Year 5, Tranche 2, Group 2 threshold printed [amount] at the same [amount] per share | Document | Annual Report 2024, page 135 |
| 25 | Grammar slip in footnote 3 | Document | Annual Report 2024, page 135 |
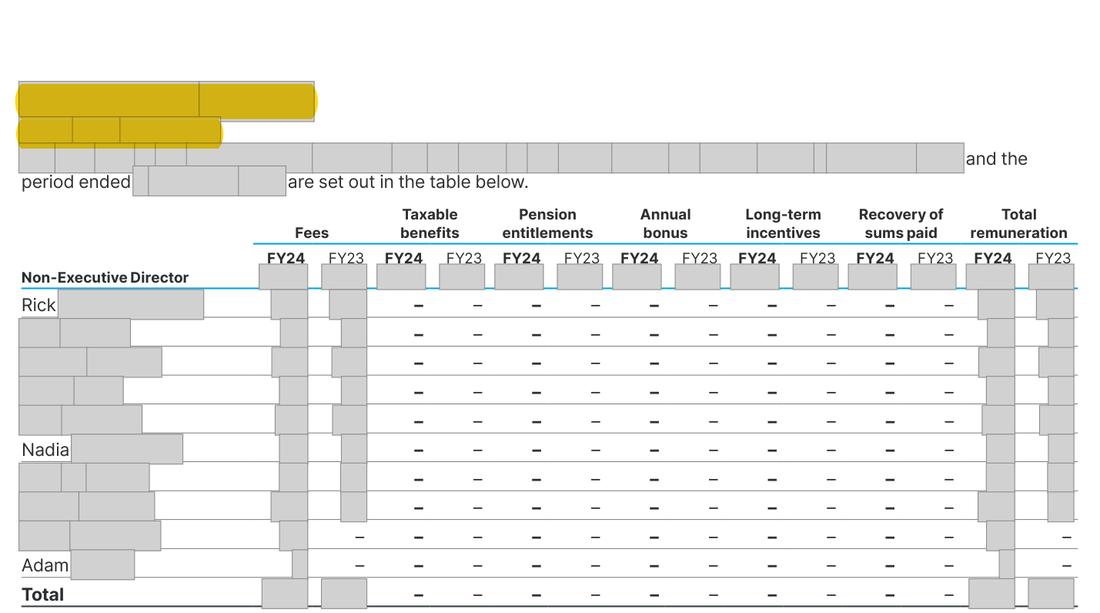
| 26 | The 2023 Total ([n]) exceeds the sum of the 2023 columns shown ([n] + [n] + [n] + [n]) | Document | Annual Report 2024, page 132 |
| 27 | A former director who served in 2023 is named in a footnote but has no column | Document | Annual Report 2024, page 132 |
| 28 | The following year's report totals only the directors shown (2024: [n] + [n]) | Document | Annual Report 2025, page 143 |
| 29 | Footnote 4 points to page 139 (the pay ratio page); the NED fees table is on page 137 | Document | Annual Report 2024, page 141 |
| 30 | The NED fees table the footnote means is on page 137 | Document | Annual Report 2024, page 137 |
| 31 | Deferred bonus granted [date] shown vesting [date] (both directors); the 2025 report shows [date] | Document | Annual Report 2024, page 145 |
| 32 | 2025 report: same award vests [date] | Document | Annual Report 2025, page 155 |
| 33 | Introduced as current period plus [n] previous years, but the table covers 2015-2024 (ten years in all) | Document | Annual Report 2024, page 140 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.