6.01 'Group adjusted revenue' carries the APM symbol in the KPIs and Financial Review but is not one of the measures the APM section lists, and the Financial Review calls the same figure 'revenue'
UK Company B · a UK-listed technology and logistics group · Drafting slip
In brief
The KPI page and the Financial Review chart show 'Group adjusted revenue' of [n] with the alternative performance measure (APM) symbol. The APM section lists eight APMs and adjusted revenue is not among them. The figure is revenue before [wording masked], where revenue is [n] after [n] of [customer] Letter of Credit revenue treated as an adjusting item; the Financial Review text calls the [n] simply 'revenue'. The 2024 report named its revenue KPI 'Total Group' and listed that APM.
The evidence, as filed
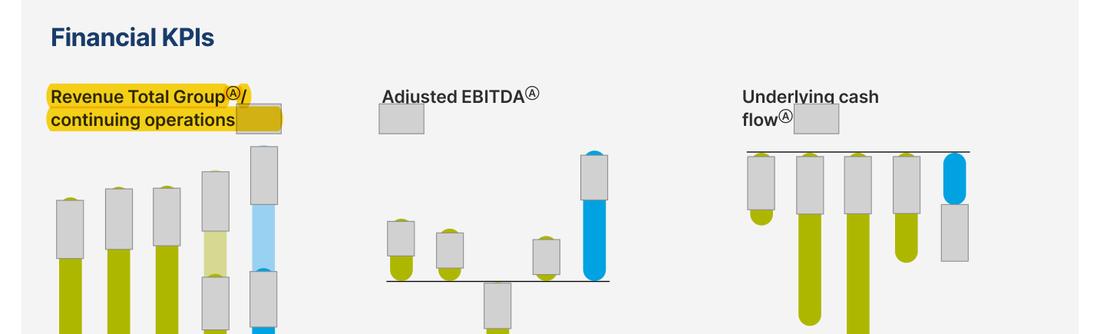
Annual Report 2024, page 16 · Prior year: The 2024 report labelled the revenue KPI 'Revenue Total Group / continuing operations', and 'Total Group' was on its list of APMs with a definition; this report renames the KPI to a label the APM section does not use.
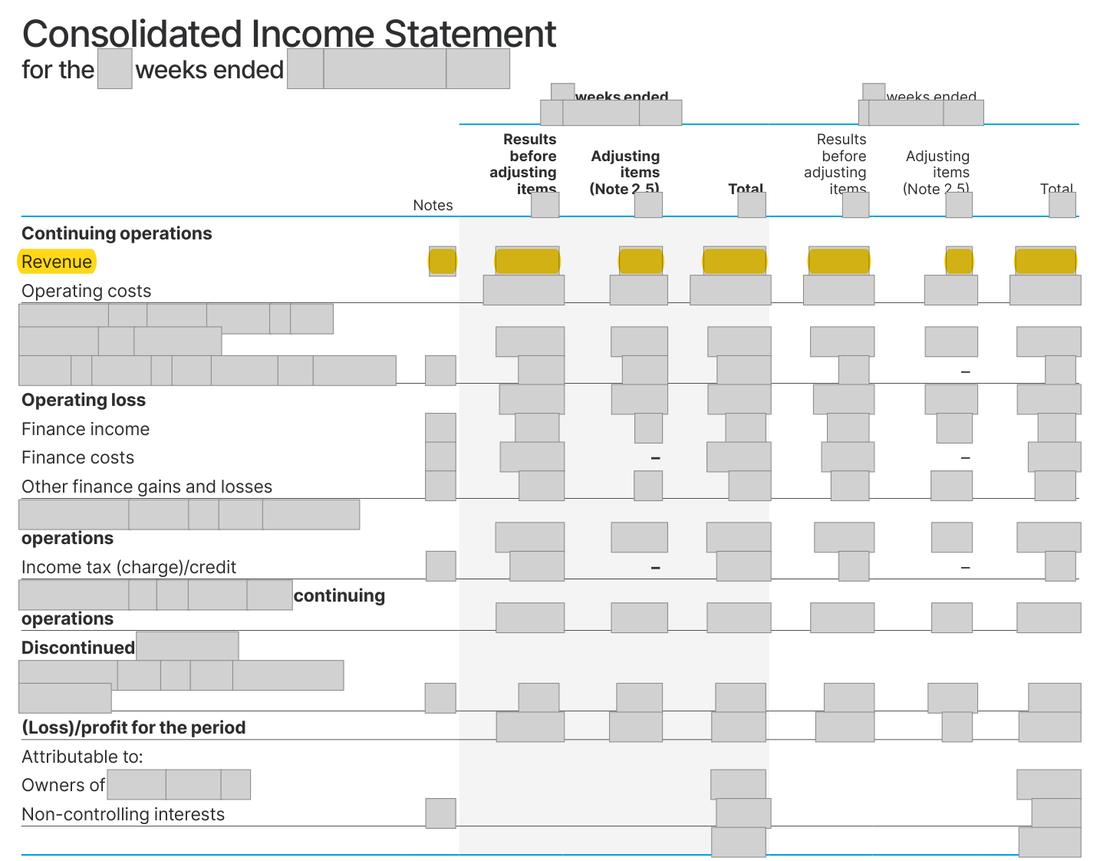
Further pages withheld to protect the company’s identity (five): Annual Report 2025, page 11; Annual Report 2025, page 22; Annual Report 2025, page 23; Annual Report 2025, page 202; Annual Report 2025, page 270. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.11 and p.22: 'Group adjusted revenue' with the APM symbol, [n]; p.23: 'delivered revenue of [amount]'; p.183: revenue before adjusting items [n], adjusting items [n], revenue [n]; p.270: the list of APMs used has no revenue measure | What the rule requires The KPI labelled as the measure it is ('revenue before adjusting items') and named in the APM list with its definition, and the Financial Review saying 'revenue before adjusting items' rather than 'revenue' |
What we checked: KPI page, Financial Review, income statement, Note 2.5, APM section and the 2024 report's KPI page (Annual Report [amount].16)
The rule
ESMA Guidelines on Alternative Performance Measures, paragraph 22
Version relied on: ESMA Guidelines on Alternative Performance Measures, ESMA/2015/1415, published October 2015, applying from July 2016; the FCA expects UK issuers to continue to apply them after EU exit
APMs disclosed should be given meaningful labels reflecting their content and basis of calculation in order to avoid conveying misleading messages to users.
Why it applies here: a labelling slip.
Why it matters
No amount is wrong; the headline revenue KPI cannot be matched to a listed APM, and the Financial Review gives a non-statutory figure the statutory name.
Exposure
Drafting only.
Our workings
the KPI and Financial Review charts label [n] 'Group adjusted revenue' with the APM symbol, and the KPI text describes it as '[wording masked]'. The APM section opens with the list of APMs used, and no revenue measure is on it; the pro-forma income statement on p.272 starts from revenue 'as reported (pre-adjusting items)'. The income statement gives revenue of [n], of which [n] is the [customer] Letter of Credit revenue in Note 2.5 shown as an adjusting item.
Every printed figure agrees to the audited income statement column before adjusting items, so no amount is wrong, but the KPI name matches no listed APM and the Financial Review gives it the statutory name.
Management’s best defence, and our reply
Management would say the figure is the income statement column before adjusting items and the starting line of the pro-forma income statement APM, so it is reconciled on the face of the audited statements. However, the KPI label is not the name of any listed APM and the Financial Review drops the qualifier, so a reader has to find the reconciliation unaided.
The fix
- Label the KPI 'revenue before adjusting items' (or add 'Group adjusted revenue' to the APM list with its definition and a reconciliation to statutory revenue), and say 'revenue before adjusting items' in the Financial Review.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | KPI page: the revenue KPI is labelled 'Group adjusted revenue' with the APM symbol | Document | Annual Report 2025, page 11 |
| 2 | The KPI is described as total turnover | Document | Annual Report 2025, page 11 |
| 3 | Financial Review chart uses the same label | Document | Annual Report 2025, page 22 |
| 4 | The Financial Review text calls the figure 'revenue' | Document | Annual Report 2025, page 23 |
| 5 | Income statement: [n] is revenue before adjusting items; statutory revenue is [n] | Document | Annual Report 2025, page 183 |
| 6 | The [n] adjusting item in revenue is the [customer] Letter of Credit revenue | Document | Annual Report 2025, page 202 |
| 7 | The list of APMs used ends without any revenue measure | Document | Annual Report 2025, page 270 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- The APMs used are:
- What is missing
- 'Group adjusted revenue' (or revenue before adjusting items) as a listed and defined APM
- Pages looked at
- p.270-273 (Alternative Performance Measures) and the glossary p.279-284
- Result
- 'adjusted revenue' and 'Group adjusted revenue' hit only the KPI and Financial Review chart labels on p.11 and [n]; 'revenue before adjusting items' hits only the segment table on p.199. None is a definition.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.