2.15 The Corporate Governance Statement says it [wording masked], a paragraph later, calls itself a separate statement with its own approval and signature
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
The Corporate Governance Statement on p.169 says it '[wording masked]', which is the route in Disclosure Guidance and Transparency Rule (DTR) 7.2.1R. Its board approval paragraph then calls it 'This separate Corporate Governance Statement 2025' and has it signed by the Chair and the Company Secretary, which is the formality the Companies Act 2006 sets for a separate statement (s.419A). Where a statement is separate, s.497A requires the auditor to give specific statements on it; the auditor's report gives none. The 2024 report used the same two descriptions.
The evidence, as filed
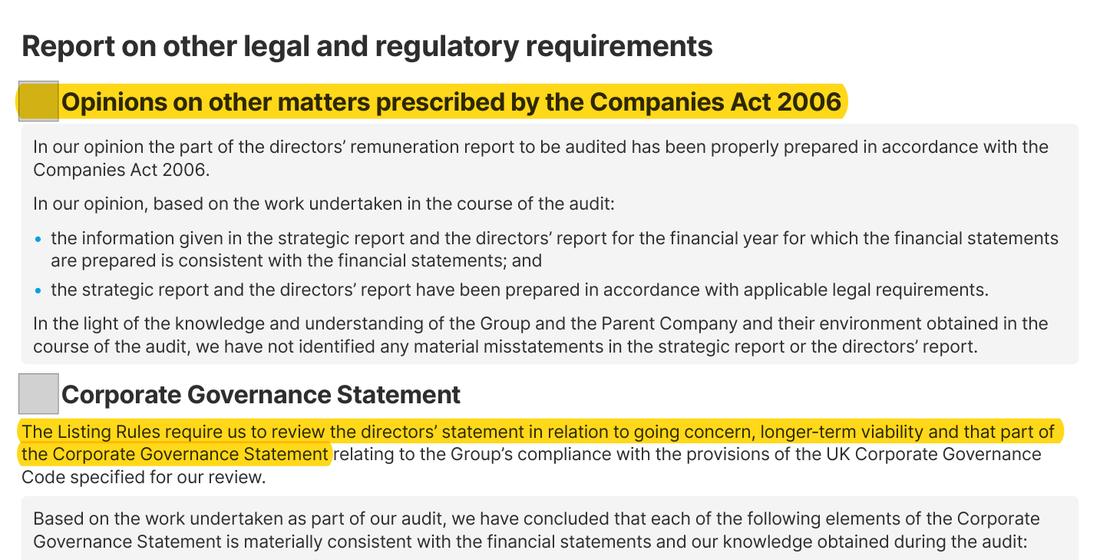
Further pages withheld to protect the company’s identity (three): Annual Report 2025, page 169; Annual Report 2024, page 155; Annual Report 2025, page 159. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows One statement described both as [wording masked] as a separate statement approved and signed in its own right; no s.497A statements in the auditor's report | What the rule requires One route stated consistently: either a specific section of the Directors' Report (DTR 7.2.1R, covered by the auditor's s.496 opinion), or a separate statement under DTR 7.2.9R with the s.497A statements in the auditor's report |
What we checked: Corporate Governance Statement, Directors' Report cross-reference table, auditor's report sections 12-14, 2024 report (Annual Report [amount].155)
The rule
FCA DTR 7.2.1R
Version relied on: FCA Handbook, Disclosure Guidance and Transparency Rules sourcebook, as in force at the financial year end
An issuer to which this section applies must include a corporate governance statement in its directors’ report. That statement must be included as a specific section of the directors’ report
FCA DTR 7.2.9R(1)
Version relied on: FCA Handbook, Disclosure Guidance and Transparency Rules sourcebook, as in force at the financial year end
An issuer may elect that, instead of including its corporate governance statement in its directors’ report, the information required by DTR 7.2.1 R to DTR 7.2.8AR may be set out in: (1) a separate report published together with and in the same manner as its annual report
Companies Act 2006 s.419A
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
Any separate corporate governance statement must be approved by the board of directors and signed on behalf of the board by a director or the secretary of the company.
Companies Act 2006 s.497A(1)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
Where the company prepares a separate corporate governance statement in respect of a financial year, the auditor must, in his report of the company’s annual accounts for that year
Why it applies here: the two descriptions point to different legal routes with different audit reporting duties; which one the Company intends cannot be told from the report.
Why it matters
Readers cannot tell which statutory route applies, and therefore whether the auditor's report contains every statement the law requires on the governance statement.
Exposure
No penalty attaches to the description itself; if the statement is separate, the missing s.497A statements are a matter for the auditor's report.
Our workings
p.169 says the statement '[wording masked], in the board approval paragraph, 'This separate Corporate Governance Statement 2025 [wording masked] signed on behalf of the Board'. The Directors' Report cross-reference table lists it under '[wording masked] [n]'. The auditor's report gives the s.496 opinion on the Directors' Report and the Listing Rules review of the governance statement, but none of the s.497A(1)(a)-(d) statements.
If the statement is part of the Directors' Report, the word 'separate' and the separate signature are surplus and the s.496 opinion covers it; if it is separate, the auditor's report lacks the s.497A statements.
Management’s best defence, and our reply
The statement sits in the Directors' Report section, the cross-reference table lists it there, and 'separate' means only that it is a distinct, specific section, which DTR 7.2.1R itself requires. The additional signature by the Chair and the Company Secretary is a governance formality that harms no one, and the auditor's s.496 opinion on the Directors' Report already covers the statement. That reading is tenable, so the point is put as a question; the answer is still needed because the word 'separate' and the s.419A-style approval are exactly what the law uses to switch on the s.497A reporting duty.
The fix
- Delete 'separate' and the separate approval paragraph (relying on the Directors' Report approval and the s.496 opinion), or state that the statement is a separate report under DTR 7.2.9R(1) and ask the auditor to include the s.497A statements.
Question for the company
Is the Corporate Governance Statement a specific section of the Directors' Report under DTR 7.2.1R, or a separate statement under DTR 7.2.9R and s.419A? If it is separate, where are the auditor's statements required by s.497A; if it is part of the Directors' Report, will the word 'separate' and the separate approval be removed?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | First description: part of the Directors' Report | Document | Annual Report 2025, page 169 |
| 2 | Second description: a separate statement approved and signed in its own right | Document | Annual Report 2025, page 169 |
| 3 | Directors' Report table lists the statement under DTR 7.2 | Document | Annual Report 2025, page 159 |
| 4 | The auditor reports on the governance statement only under the Listing Rules review | Document | Annual Report 2025, page 181 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [n]. Opinions on other matters prescribed by the Companies Act 2006
- What is missing
- the s.497A statements on a separate corporate governance statement (consistency and legal preparation of the DTR 7.2.5 and 7.2.6 information, misstatements, compliance with DTR 7.2.2, 7.2.3 and 7.2.7)
- Pages looked at
- p.171-182 (whole auditor's report)
- Result
- 'separate corporate governance statement' hits only p.169, the board approval sentence itself; '7.2.5', '7.2.6', '497A' and 'share capital structures' have no hit anywhere in the report
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.