2.10 The annual bonus outturns for 'Group EBITDA' and cash-flow improvement do not match the figures reported in the Financial review, and the basis is not explained
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
The audited annual bonus (Annual Incentive Plan, AIP) table records 'Group EBITDA' of [amount] and an '[wording masked] [customer] Letter of Credit' of [amount], both at 100% of maximum. The Financial review reports adjusted EBITDA of [amount] and an [wording masked] of [amount]. The remuneration report does not define either bonus measure or bridge it to the reported figures, so a shareholder cannot see how the actual performance was measured.
The evidence, as filed
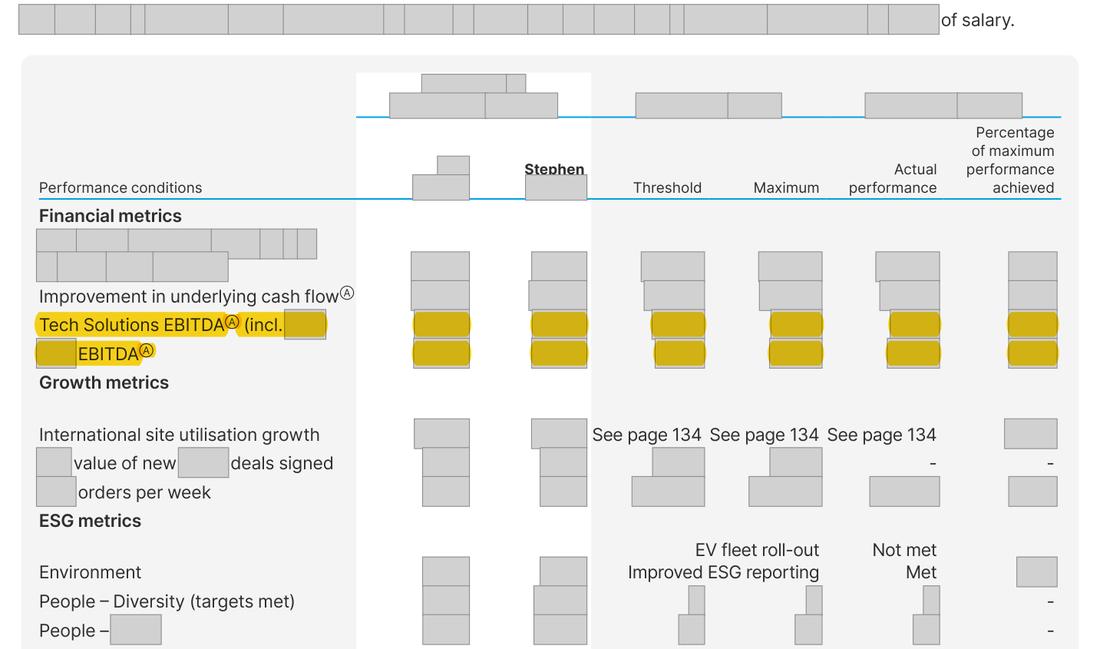
Further pages withheld to protect the company’s identity (four): Annual Report 2025, page 145; Annual Report 2025, page 144; Annual Report 2025, page 23; Annual Report 2025, page 26. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows AIP actual performance: Group EBITDA [amount] (threshold [amount], maximum [amount]); cash-flow improvement [amount] (threshold [amount], maximum [amount]). Financial review: adjusted EBITDA [amount]; [wording masked] [amount]. No definition or reconciliation in the remuneration report. | What the rule requires Each AIP financial measure defined (perimeter, e.g. whether [former subsidiary] is included, and any adjustments) and its actual performance reconciled to the nearest reported figure, as the 2024 report's bonus measures were. |
The rule
SI 2008/410 Schedule 8, paragraph 12(3)(a)-(c)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
details of any performance measures and the relative weighting of each; (b)within each performance measure, the performance targets set at the beginning of the performance period and corresponding value of the award achievable; (c)for each performance measure, details of actual performance relative to the targets set
UK Corporate Governance Code 2018, Provision 41
Version relied on: UK Corporate Governance Code, FRC, July 2018; applies to financial years beginning from January 2019 (the 2024 edition applies from January 2025)
an explanation of the strategic rationale for executive directors' remuneration policies, structures and any performance metrics
Why it applies here: the bonus Group EBITDA is probably a wider perimeter (for example including [former subsidiary], whose adjusted EBITDA was [amount]), but the report does not say so, and the requirement to set out actual performance relative to the targets is only meaningful if the reader knows what was measured.
Why it matters
Shareholders voting on the remuneration report cannot verify that the two elements paid at maximum were measured on the reported results; if the bonus EBITDA were the reported [amount], that element would not be at maximum.
Exposure
A question for the Remuneration Committee; no penalty attaches unless the answer showed the audited table did not comply.
Our workings
the AIP table gives Group EBITDA actual [amount] against a [amount] maximum, and a cash-flow improvement of [amount] against an [amount] maximum; the Committee says the [customer] termination fees '[wording masked]' and that the Letter of Credit drawdown [wording masked]. The Financial review gives adjusted EBITDA of [amount] and an [wording masked] of [amount]. 'Group EBITDA' appears nowhere else in the report. In the 2024 report the bonus EBITDA measures ([segment] EBITDA [amount], [former subsidiary] EBITDA [amount]) were the reported alternative performance measures.
the gaps are [amount] and [amount] (workings). The reported adjusted EBITDA of [amount] lies between the [amount] threshold and the [amount] maximum, so the basis of the measure decides whether that element pays in full; it carries 20% of the Chief Executive Officer's maximum ([amount] and 25% of the Chief Financial Officer's ([amount]. The cash-flow element pays in full on either figure, as [amount] is above the [amount] maximum.
| Measure | AIP actual | Reported figure | Gap |
|---|---|---|---|
| Group EBITDA (£m) | [n] | [n] adjusted EBITDA | [n] - [n] = [n] |
| Cash-flow improvement incl. Letter of Credit (£m) | [n] | [n] | [n] - [n] = [n] |
| Reported EBITDA within bonus range (£m) | [n] < [n] < [n] | ||
| CEO maximum on EBITDA element (£) | 20% x [n]% x [n] = [n] | ||
| CFO maximum on EBITDA element (£) | 25% x [n]% x [n] = [n] |
Management’s best defence, and our reply
The Committee would say the bonus measures were set at the start of the year on a perimeter and basis that suited the business before [former subsidiary] was deconsolidated, and that targets and outturns are measured consistently on that basis. It would add that the cash-flow element pays in full on either figure, and that the auditor has audited the table. The answer: consistency with the targets is the point, but the reader still has to be told what the basis is; the 2024 report used measures that tied to reported figures, and this year's 'Group EBITDA' appears nowhere outside the bonus tables.
The fix
- Add under the AIP table: 'Group EBITDA for AIP purposes comprises Group adjusted EBITDA ([amount]) plus [items], and the cash-flow measure is [definition]; reconciliation: ...'.
Question for the company
How are the AIP 'Group EBITDA' ([amount]) and '[wording masked] [customer] Letter of Credit' ([amount]) defined, and how do they reconcile to the reported adjusted EBITDA of [amount] and the reported [amount] [wording masked]?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Bonus Group EBITDA: weights, threshold, maximum, actual [amount], paid at maximum | Document | Annual Report 2025, page 145 |
| 2 | Bonus cash-flow measure: actual improvement [amount], paid at maximum | Document | Annual Report 2025, page 145 |
| 3 | The Committee's only statement on what the outturn includes | Document | Annual Report 2025, page 145 |
| 4 | Maximum bonus percentages used in the workings | Document | Annual Report 2025, page 145 |
| 5 | CEO base salary used in the workings | Document | Annual Report 2025, page 144 |
| 6 | CFO base salary used in the workings | Document | Annual Report 2025, page 144 |
| 7 | Reported adjusted EBITDA [amount] | Document | Annual Report 2025, page 23 |
| 8 | Reported [wording masked], [amount] | Document | Annual Report 2025, page 23 |
| 9 | [former subsidiary] adjusted EBITDA, a possible component of a wider perimeter | Document | Annual Report 2025, page 26 |
| 10 | 2024 report: the bonus EBITDA measure was the reported segment figure ([amount]) | Document | Annual Report 2024, page 133 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- Performance conditions
- What is missing
- a definition of the bonus 'Group EBITDA' and cash-flow measures and a reconciliation of their actuals to the reported figures
- Pages looked at
- p.133-135, 143-147 (remuneration report), p.22-27 and 40-42 (Financial review), alternative performance measures section
- Result
- 'Group EBITDA' hits only the two bonus tables (p.135 and [n]) and 'Group adjusted EBITDA' (p.1, [n]), which is the reported [amount] measure; 'reconciliation' hits only the alternative performance measure and statutory reconciliations, none of which mention the bonus; '[amount]' hits only the bonus tables; 'AIP EBITDA' and 'bonus EBITDA' do not hit.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.