1.27 Fair value and pricing inputs are given only for the Performance Share Plan, not for the other share options and awards granted in the year
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
International Financial Reporting Standard 2 (IFRS 2) asks for the weighted average fair value of the options and share awards granted in the year and how it was measured. The 2024 note gives this only for the Performance Share Plan ([amount], with Monte Carlo inputs). For [n] [name] options, [n] consultant options, [n] Restricted Share Plan awards and [n] Annual Incentive Plan awards granted in the year it gives the numbers only. The 2025 report is the same for the [n] [name] options it granted.
The evidence, as filed
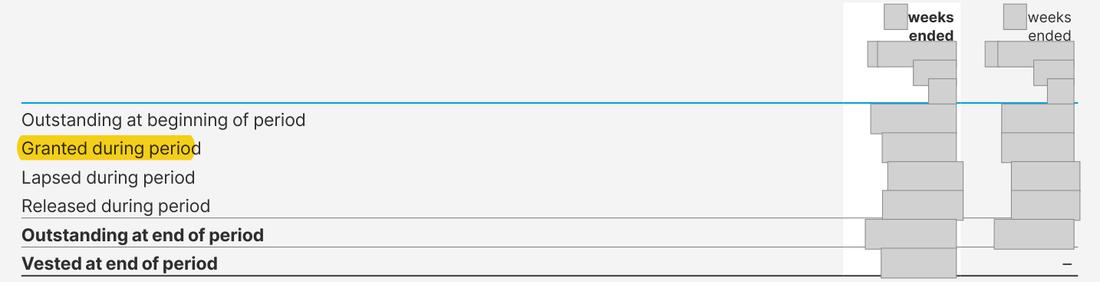
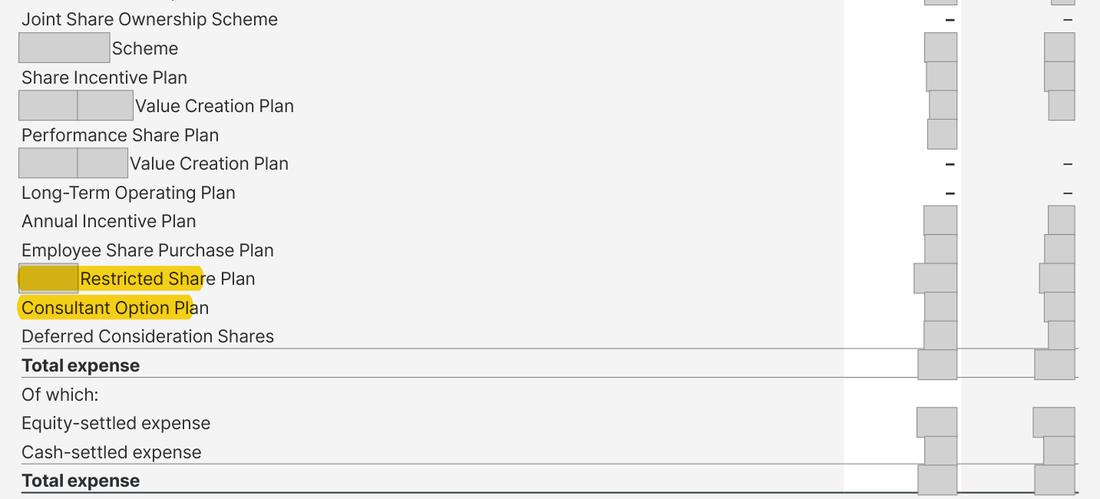
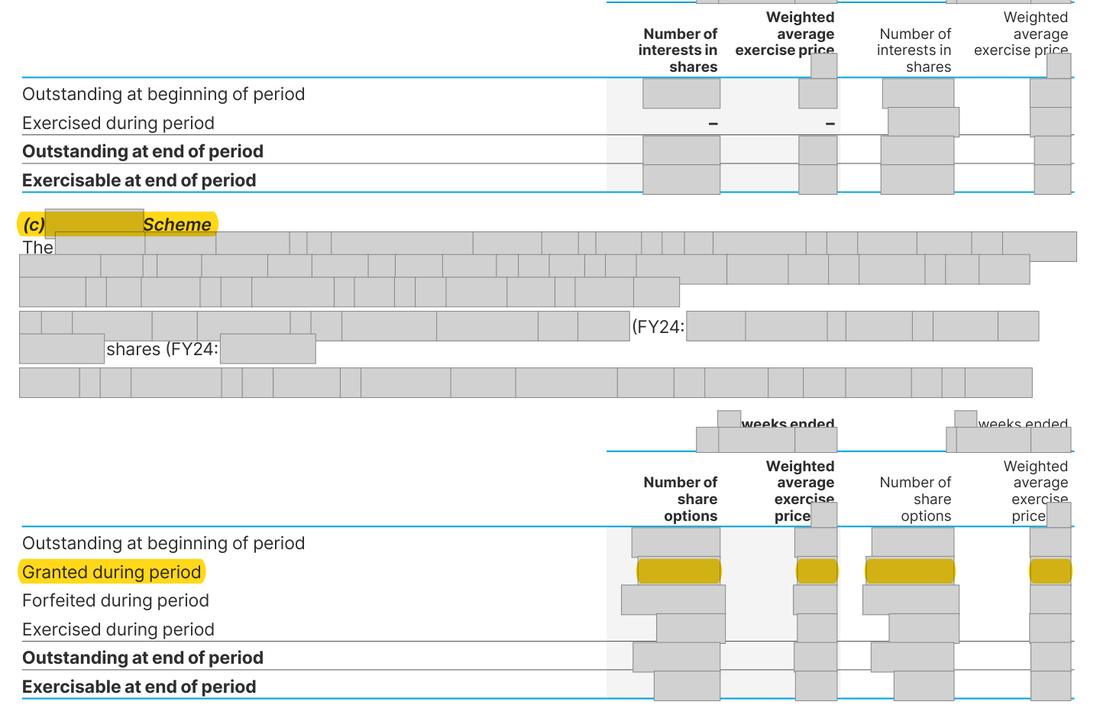
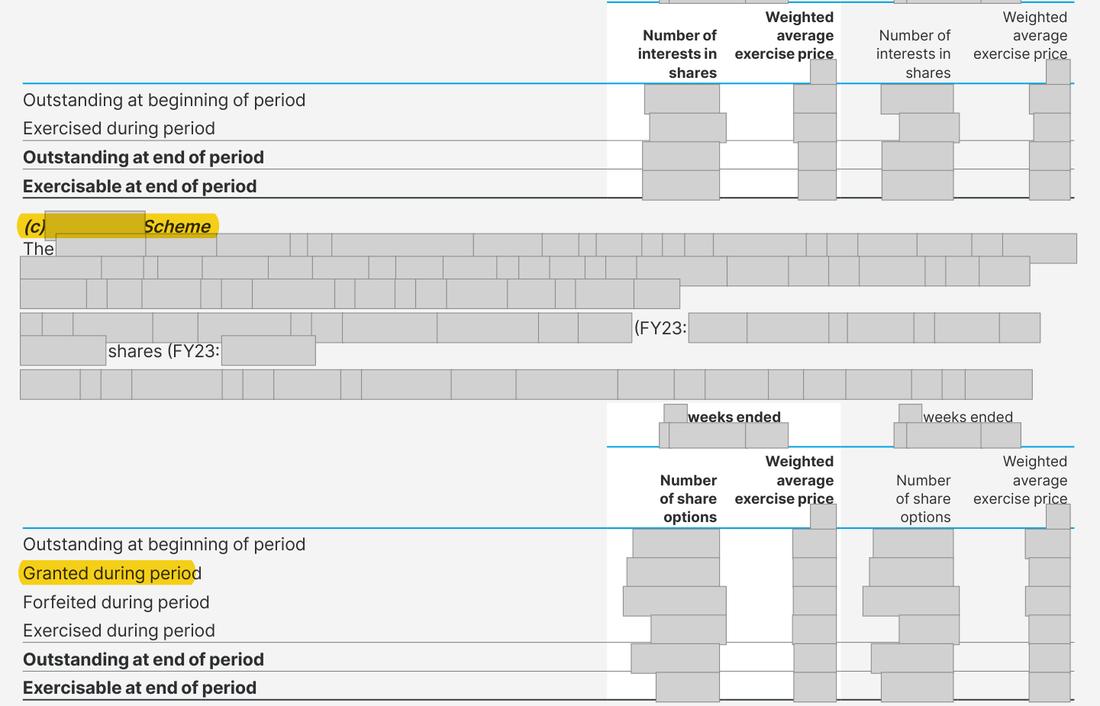
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 226; Annual Report 2024, page 225. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Grants of the year shown by number only: [name] [n] options; consultant options [n]; Restricted Share Plan [n] awards; Annual Incentive Plan [n] awards. Fair value and model inputs are given only for the Performance Share Plan ([amount]). | What the rule requires For each option plan with grants in the year, the weighted average grant-date fair value and the pricing model with its inputs; for each share-award plan, the number and weighted average grant-date fair value and how it was measured. If the Board judges any of this immaterial, the note should not imply that the model inputs are complete. |
What we checked: Every plan section of Note 4.7 read on the page images; whole-report search for fair value and pricing-model wording; the 2025 report's [name] section.
The rule
IFRS 2 Share-based Payment, paragraph 47(a)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
For options granted in the year, the accounts must give their weighted average fair value at the measurement date and explain how that fair value was measured.
IFRS 2 Share-based Payment, paragraph 47(b)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
For equity instruments other than options granted in the year, the accounts must give their number and weighted average fair value at the measurement date and how that fair value was measured.
Why it applies here: IFRS 2 paragraph 47(a) requires, for options granted in the period, the weighted average fair value and the model and inputs; paragraph 47(b) requires, for other equity instruments granted, the number and the weighted average fair value and how it was measured.
Why it matters
A reader cannot see how the largest share-based charges were measured or test the reasonableness of the inputs; the Financial Reporting Council (FRC) Corporate Reporting Review team can ask for the missing information.
Exposure
None while this is a question; if the Board cannot show the omitted information is immaterial, the realistic outcome of an FRC Corporate Reporting Review enquiry is an undertaking to add it in the next Annual Report.
Our workings
Note 4.7 lists twelve plans. For 2024 it gives a fair value only for the Performance Share Plan ('[wording masked] [amount]') with a Monte Carlo input table. The [name] table shows [n] options granted at a weighted average exercise price of [amount], the consultant table [n] options granted, the Restricted Share Plan table [n] awards granted and the Annual Incentive Plan table [n] awards granted; none of these sections gives a grant-date fair value or how it was measured. The Restricted Share Plan charge was [amount] and the [name] charge [amount] of a total charge of [amount].
the Restricted Share Plan alone is [n] / [n] = [n]% of the total charge (workings).
The note meets this for the Performance Share Plan and the earlier Executive Share Option Scheme and Value Creation Plan grants, which shows the company applies the requirement, but not for the plans that carry most of the charge. Whether the Board treated the rest as immaterial under IAS 1 paragraph 31 is not stated, so the point is put as a question.
| Plan | Granted in 2024 | Fair value or model given? |
|---|---|---|
| [name] options | [n] | No |
| Consultant options | [n] | No |
| Restricted Share Plan awards | [n] | No |
| Annual Incentive Plan awards | [n] | No |
| Performance Share Plan awards | [n] | Yes: [amount] and Monte Carlo inputs |
| Restricted Share Plan share of total charge | [n] / [n] = [n]% |
Management’s best defence, and our reply
The finance team would say that the [wording masked] awards are nil-cost conditional shares whose fair value is simply the quoted share price on the grant date with no dividends expected, so the measurement is evident from the accounting policy. They would add that the [name] and consultant charges ([amounts]) are small against a loss before tax of [amount], so IAS 1 paragraph 31 lets a specific IFRS 2 disclosure be left out as immaterial, and the auditor raised no point. However, paragraph 47(b) asks for the number and the weighted average fair value even where the price is observable, and the Restricted Share Plan carried [amount] of the [amount] charge; the [name] options carry an exercise price, so their value depends on volatility and life inputs the note never gives. The materiality answer is respectable for the smaller plans, which is why the point is a question rather than a finding.
The fix
- For each plan with grants in the year give the number and weighted average grant-date fair value, and for the [name] and consultant options the pricing model and inputs, e.g. '[name] options granted in the year had a weighted average fair value of £x, measured using the Black Scholes model with the following inputs ...'.
Question for the company
For the [name] and consultant options and the [wording masked] awards granted in 2024 (and the [name] options granted in 2025), what was the weighted average grant-date fair value and how was it measured, and did the Board decide that this information was not material?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Fair value is given for the Performance Share Plan grant | Document | Annual Report 2024, page 226 |
| 2 | Performance Share Plan awards granted in 2024 | Document | Annual Report 2024, page 226 |
| 3 | [name] options granted in 2024 at a weighted average exercise price of [amount]; the section gives no fair value or model | Document | Annual Report 2024, page 221 |
| 4 | Restricted Share Plan awards granted in 2024: [n]; no fair value given | Document | Annual Report 2024, page 225 |
| 5 | Consultant options granted in 2024; no fair value or model given | Document | Annual Report 2024, page 225 |
| 6 | Annual Incentive Plan awards granted in 2024; no fair value given | Document | Annual Report 2024, page 224 |
| 7 | Restricted Share Plan charge for 2024 | Document | Annual Report 2024, page 219 |
| 8 | [name] charge for 2024 | Document | Annual Report 2024, page 219 |
| 9 | Consultant option charge for 2024 | Document | Annual Report 2024, page 219 |
| 10 | Total share-based payment charge for 2024 | Document | Annual Report 2024, page 219 |
| 11 | Group loss before tax for 2024 (including discontinued operations), the scale for the charge | Document | Annual Report 2024, page 227 |
| 12 | 2025 report: [name] options granted in 2025, again with no fair value or model inputs | Document | Annual Report 2025, page 248 |
Absence check
- Document
- Annual Report 2024
- Where it would appear
- (c) [name] Scheme
- What is missing
- the weighted average fair value of the [name] options granted in 2024 and the pricing model and inputs used
- Pages looked at
- Annual Report [amount].219-226 (all of Note 4.7) on the page images; whole report searched
- Result
- 'weighted average fair value' does not appear. 'Black Scholes' appears only on p.220 (Executive Share Option Scheme options granted in 2023; none granted in 2024). 'Monte Carlo' appears on p.223 (Value Creation Plan awards granted in 2023) and p.226 (Performance Share Plan 2024). 'option pricing model' appears on p.213-214 (valuation of the [investee] investment) and p.220 (the 2023 option grant). 'fair value of awards granted' appears only on p.223 (Value Creation Plan); the Performance Share Plan section on p.226 reads '[wording masked]'. None covers the [name], consultant, Restricted Share Plan or Annual Incentive Plan grants.
Absence check
- Document
- Annual Report 2024
- Where it would appear
- (i) the Company Restricted Share Plan
- What is missing
- the weighted average grant-date fair value of the [n] Restricted Share Plan awards and how it was measured
- Pages looked at
- Annual Report [amount].219-226 on the page images; whole report searched
- Result
- 'weighted average fair value' does not appear. 'Monte Carlo' and 'fair value of awards granted' hit only the Value Creation Plan and Performance Share Plan sections. 'Restricted Share Plan' hits the charge table, this section and the remuneration report, none of which gives a grant-date fair value.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.