1.24 The 2024 comparatives in the facilities table are [amount] lower than the 2024 report printed, with no explanation of the change
UK Company B · a UK-listed technology and logistics group · Regulator-style question
In brief
The capital management note shows, for [date] (in £ million), total facilities of [n], drawn facilities of [n] and undrawn facilities of [n]. The 2024 report gave [n] for the same date, and said that [amount] of the undrawn amount was lease facilities. The 2025 report changes the comparatives, apparently by taking out the lease facilities, without saying so, and liquidity for 2024 (undrawn facilities plus cash) falls from [n] to [n].
The evidence, as filed
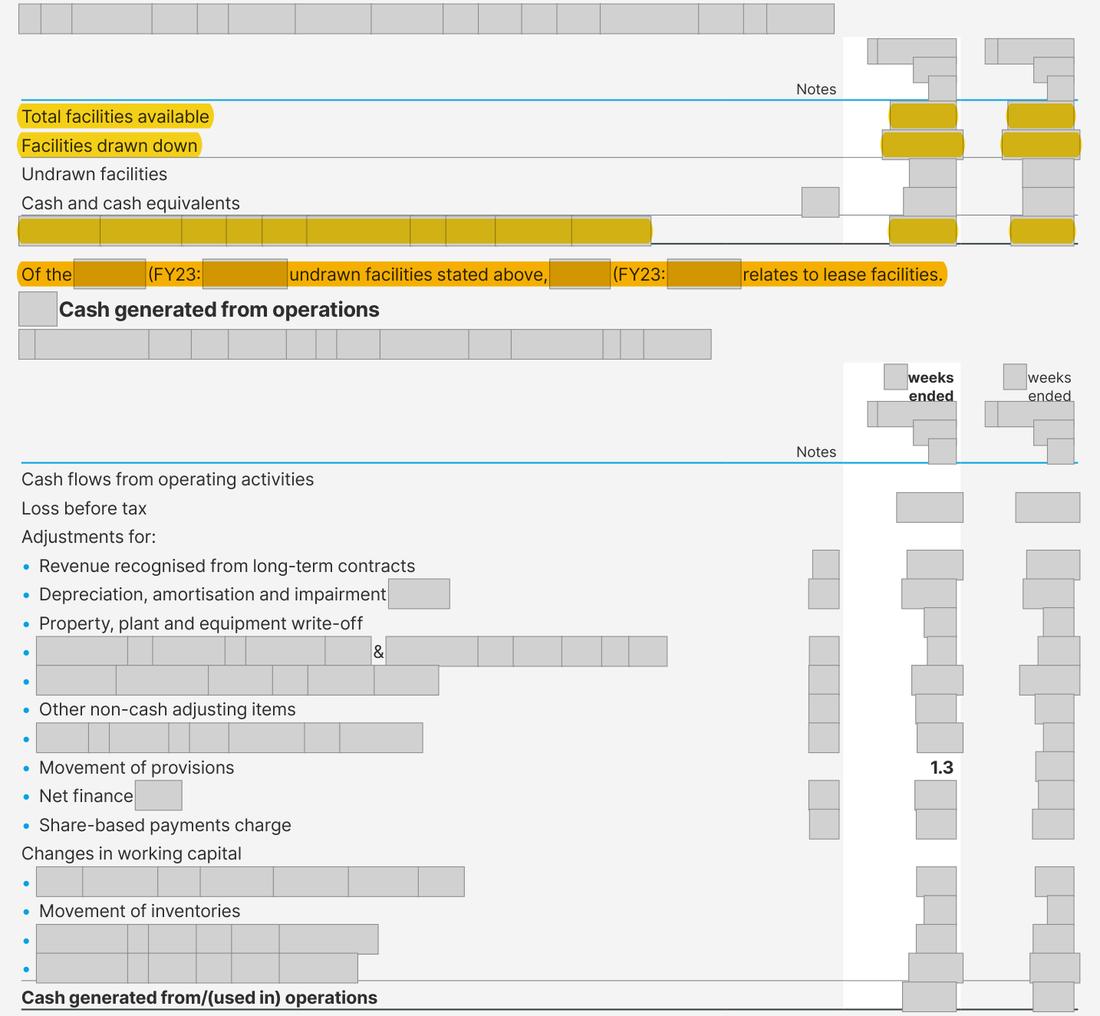
Further pages withheld to protect the company’s identity (one): Annual Report 2025, page 252. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2025 report, [date] column (£ million): total facilities [n]; drawn ([n]); undrawn [n]; with cash [n]. 2024 report, same date: [n]; ([n]); [n] (of which [amount] lease facilities); with cash [n]. | What the rule requires Comparatives that agree with the 2024 report, or a statement that they have been re-presented (for example to exclude lease facilities), with the amounts changed and the reason. |
The rule
IAS 1 Presentation of Financial Statements, paragraph 41
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
When presentation or classification changes, the comparatives must be reclassified (unless impracticable), with disclosure of what was reclassified, how much and why.
Why it applies here: the comparatives appear to have been re-presented to leave out lease facilities, drawn and undrawn.
Why it matters
A reader comparing the two reports sees 2024 liquidity reduced by [amount] with no explanation, and cannot tell whether facilities have been redefined or the earlier figures were wrong.
Exposure
A comparative presentation point; no penalty attaches. An explanation in the next Annual Report is the remedy.
Our workings
the facilities table on p.252 and the 2024 report's table on its p.227 give the figures quoted in the evidence rows for the same date. The 2025 note no longer has the sentence on lease facilities, and the whole-report search found no statement that the comparative was changed.
undrawn facilities fall by [n] - [n] = [n], exactly the lease facilities the 2024 report identified; total facilities fall by [n] - [n] = [n] and drawn facilities by [n] - [n] = [n], and [n] - [n] = [n]. Liquidity with cash falls by [n] - [n] = [n].
That may well be a sensible change (the 2025 figures show undrawn facilities equal to the [amount] revolving credit facility only), but a reader comparing the two reports is not told. Whether IAS 1.41 strictly applies to a capital management table is arguable, so the point is put as a question.
| Step | Computation | Result (GBP m) |
|---|---|---|
| Change in undrawn facilities | [n] - [n] = [n] | [n] |
| Change in total facilities | [n] - [n] = [n] | [n] |
| Change in drawn facilities | [n] - [n] = [n] | [n] |
| Net change (undrawn lease facilities) | [n] - [n] = [n] | [n] |
| Change in liquidity with cash | [n] - [n] = [n] | [n] |
| Share of the 2025 loss before tax | [n] / [n] = [n]% | [n]% |
Management’s best defence, and our reply
Management could say that the facilities table is an encouraged disclosure rather than an item in the primary statements, that excluding lease facilities gives a cleaner measure of committed liquidity, and that the change is self-evident because the 2025 undrawn figure equals the revolving credit facility. They might also argue that IAS 1.41 is aimed at line items of the statements. That has some merit, which is why the point is a question; but a comparative that differs from the published figure by [amount] should carry a one-line explanation whatever the standard's reach.
The fix
- Add a footnote: "The comparatives for [date] have been re-presented to exclude lease facilities (undrawn [amount], drawn [amount]) to align with the current-period definition."
Question for the company
Why do the [date] facility figures in the 2025 report (total [amount], drawn [amount], undrawn [amount]) differ from those in the 2024 report ([amounts]), and was the change to exclude lease facilities disclosed anywhere?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2025 report: total facilities at [date] [amount] | Document | Annual Report 2025, page 252 |
| 2 | 2025 report: drawn facilities at [date] [amount] | Document | Annual Report 2025, page 252 |
| 3 | 2025 report: undrawn facilities at [date] [amount] | Document | Annual Report 2025, page 252 |
| 4 | 2025 report: undrawn facilities and cash at [date] [amount] | Document | Annual Report 2025, page 252 |
| 5 | 2024 report as published: total facilities [amount] | Document | Annual Report 2024, page 227 |
| 6 | 2024 report as published: drawn facilities [amount] | Document | Annual Report 2024, page 227 |
| 7 | 2024 report as published: undrawn facilities and cash [amount] | Document | Annual Report 2024, page 227 |
| 8 | 2024 report as published: undrawn facilities [amount], of which [amount] lease facilities | Document | Annual Report 2024, page 227 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [wording masked]
- What is missing
- a statement that the [date] comparatives differ from the 2024 report, with the amounts and the reason
- Pages looked at
- p.231-234 and [n] (borrowings, net debt and capital management notes)
- Result
- 'lease facilities': no hit. 're-presented': p.22, [n] (equity accounting of [former subsidiary] in the income statement and cash flows). 'restated': p.60, [n] (emissions, remuneration history, the adjusted EBITDA definition). 'undrawn': p.27, [n] (liquidity totals, a principal risk, the undrawn revolving credit facility and this table). None explains the change to the 2024 facility figures.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.