1.02 Diluted earnings per share for 2025 includes convertible-bond shares that the standard requires to be excluded, and no diluted figure is given for the discontinued operation
UK Company B · a UK-listed technology and logistics group · Compliance or disclosure gap
In brief
The 2025 income statement shows diluted earnings per share (EPS) for the year of [amount] against basic EPS of [amount], by adding [n] potential shares and [amount] of convertible-bond cost. The same statement treats those shares as having no effect on the loss per share from continuing operations, which is the only test IAS 33 allows. Applied consistently, diluted EPS for the year equals basic EPS at [amount]. Note 2.8 gives a basic per-share figure for the discontinued operation ([amount]) but no diluted figure; the 2024 report had given the discontinued figure on the basic and diluted share count.
The evidence, as filed
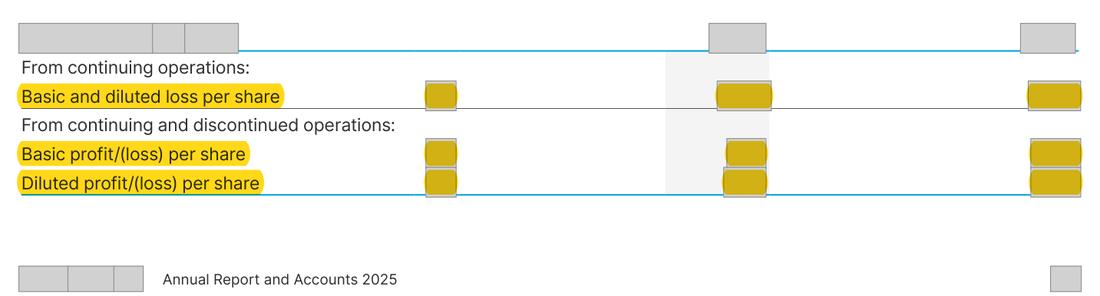
Further pages withheld to protect the company’s identity (three): Annual Report 2024, page 187; Annual Report 2025, page 208; Annual Report 2025, page 209. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2025: diluted profit per share [amount] ([n] shares; earnings [n] including the [n] bond add-back), while continuing operations show basic and diluted loss per share of ([n])p on the same potential shares; only a basic per-share figure ([amount]) for the discontinued operation | What the rule requires Diluted EPS for the year [amount] (the potential shares are antidilutive against the continuing-operations loss and so are excluded from every diluted figure); basic and diluted per-share amount for the discontinued operation disclosed ([amount]) |
The rule
IAS 33 Earnings per Share, paragraph 41
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Potential ordinary shares are dilutive only if converting them would reduce earnings per share, or increase loss per share, from continuing operations.
IAS 33, paragraph 42
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Profit or loss from continuing operations attributable to the parent is the control number used to decide whether potential shares are dilutive or antidilutive.
IAS 33, Appendix A application guidance (control number example)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Because the continuing-operations figure is the control number, shares that are dilutive on that basis are included in every other diluted per-share figure, even where the result is antidilutive.
IAS 33, paragraph 68
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
An entity with a discontinued operation must give basic and diluted per-share amounts for that operation, on the face of the income statement or in the notes.
Why it applies here: the company applied the antidilution test to the continuing line (presenting basic and diluted together) but then tested dilution separately against the total profit, which IAS 33 does not permit: profit or loss from continuing operations is the single control number for all diluted amounts.
Why it matters
- Diluted earnings per share is printed on the face of the audited income statement, and [amount] tells readers that conversion of the bonds dilutes earnings when, for this year, the standard says it does not.
- The per-share disclosure for the discontinued operation lacks the diluted amount the standard requires and the 2024 report gave.
Diluted EPS for 2025 on the face of the audited income statement is understated by [amount], and the reader is told that conversion of the bonds dilutes earnings when the standard says that for this year it does not; the per-share disclosure for the discontinued operation lacks its diluted amount.
Exposure
No sanction is stated. If the Financial Reporting Council's Corporate Reporting Review raised it, the realistic outcome is a letter and an undertaking to correct the comparative in the next report; a formal revision under sections 454-456 of the Companies Act 2006 would be unlikely for a [amount] difference.
Our workings
the 2025 income statement shows basic [wording masked] operations of ([n])p, basic profit per share for the year of [amount] and diluted profit per share of [amount]. Note 2.8 builds the [amount] from [n] diluted shares ([n] basic plus [n] dilution) and earnings of [n] after adding back [n] for conversion of the convertible bonds. The loss from continuing operations attributable to owners is ([n]). Note 2.8 gives basic EPS from discontinued operations of [amount] and no diluted figure. The 2024 report (Note 2.8, p.187) computed the discontinued loss per share of ([n])p on the '[wording masked] shares' and stated that all potentially dilutive shares were anti-dilutive, so the 2025 omission is a departure from the prior year.
with the [n] shares and the [n] add-back, the continuing loss per share becomes ([n])p, a smaller loss than basic ([n])p, so the potential shares are antidilutive at the control number. Excluding them from every diluted figure, as the control-number rule requires, gives diluted EPS for the year of [amount], not [amount] (difference [amount], 1% of the figure), and diluted EPS from the discontinued operation of [amount].
The face of the income statement shows a dilution that the standard says does not exist for this year.
| Step | Computation | Result |
|---|---|---|
| Basic EPS for the year | [n] / [n] = [n] | [amount] |
| Control-number test: continuing loss with dilution | (-[n] + [n]) / ([n] + [n]) = -[n] / [n] = -[n] | ([n])p, a smaller loss than ([n])p: antidilutive |
| Diluted EPS as reported | [n] / [n] = [n] | [amount] |
| Diluted EPS with potential shares excluded | [n] / [n] = [n] | [amount] |
| Difference (reported - correct) | [n] - [n] = -[n] | -[n] |
| Size of the difference | [n] / [n] = 1% | 1% |
| Diluted EPS, discontinued operation (missing) | [n] / [n] = [n] | [amount] |
Management’s best defence, and our reply
The company could say that the total profit for the year, including the [amount] discontinued result, is the figure investors look at, and that showing the dilution from the convertible bonds against that profit is more informative than showing none. It could add that [amount] on [amount] is immaterial and that the continuing line, which is the one used for performance, is correctly shown as basic and diluted. The answer: IAS 33.42 and the control-number example in Appendix A leave no choice, because the control number is profit or loss from continuing operations and the same potential shares must be included in, or excluded from, every diluted amount; the standard's own example rejects testing each line separately. Materiality does not cure a primary-statement figure that the auditor's opinion covers, and IAS 33.68 separately requires the diluted discontinued figure, which the 2024 report did give on the basic and diluted share count.
The fix
- Re-present the 2025 comparative in the Annual Report 2026: 'Diluted profit per share [amount] (basic and diluted)', with a note that the convertible bonds and share awards are antidilutive at the continuing-operations level, and add 'Basic and diluted [wording masked] [amount]'.
Where: Consolidated income statement, page 183, and Note 2.8 Earnings per share
Proposed wording
Diluted profit/(loss) per share [n] (the convertible bonds and share awards are antidilutive at the continuing-operations level)
add to Note 2.8 'Basic and diluted [wording masked] [amount]'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Continuing operations: the potential shares are treated as having no dilutive effect (basic equals diluted) | Document | Annual Report 2025, page 183 |
| 2 | Diluted EPS for the year as presented on the face of the income statement | Document | Annual Report 2025, page 183 |
| 3 | Basic EPS for the year, the figure diluted EPS should equal | Document | Annual Report 2025, page 183 |
| 4 | [amount] potential shares added in the diluted share count | Document | Annual Report 2025, page 208 |
| 5 | Diluted share count used for [amount] | Document | Annual Report 2025, page 208 |
| 6 | Basic share count | Document | Annual Report 2025, page 208 |
| 7 | Control number: continuing loss attributable to owners | Document | Annual Report 2025, page 208 |
| 8 | Discontinued profit attributable to owners, used for the missing diluted figure | Document | Annual Report 2025, page 208 |
| 9 | Profit for the year attributable to owners | Document | Annual Report 2025, page 208 |
| 10 | Bond cost added back to earnings for the diluted figure | Document | Annual Report 2025, page 209 |
| 11 | Diluted earnings used for [amount] | Document | Annual Report 2025, page 209 |
| 12 | Only a basic per-share figure is given for the discontinued operation | Document | Annual Report 2025, page 209 |
| 13 | 2024 report: basic equals diluted because all potential shares were anti-dilutive | Document | Annual Report 2024, page 187 |
| 14 | 2024 report: a per-share figure for the discontinued operation, computed on the basic and diluted share count | Document | Annual Report 2024, page 187 |
| 15 | Profit or loss from continuing operations attributable to owners, the control number, is a loss of [n] | Document | Annual Report 2025, page 208 |
| 16 | [amount] potential shares are added to the diluted share count | Document | Annual Report 2025, page 208 |
| 17 | [n] of convertible bond costs is added back to earnings for diluted EPS | Document | Annual Report 2025, page 209 |
| 18 | Basic EPS for the year is [amount] | Document | Annual Report 2025, page 209 |
| 19 | Diluted EPS is printed as [amount], below basic | Document | Annual Report 2025, page 209 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [wording masked]
- What is missing
- a diluted per-share amount for the discontinued operation (basic only is given)
- Pages looked at
- p.183, 208-209, 268-273; Annual Report [amount].166, [n]
- Result
- 'diluted' hits p.183 (continuing basic and diluted, total diluted), [n] (method and share count), [n] (total diluted) and [n] (a shareholding in an investee diluted): none is a per-share amount for the discontinued operation. 'per share from discontinued' hits only p.209, the basic figure. 'discontinued operations' hits the statements, note [n] and note [n] with no per-share amount.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.