6.03 Scope 3: the '60% reduction from 2021 baseline' compares 2025 data for all [n] categories with a 2021 baseline built from 8 categories; the report does not say whether the baseline was recalculated
UK Company A · a UK-listed medical technology group · Regulator-style question
In brief
The Planet page reports Scope 3 emissions down 60% from the 2021 baseline. The baseline of [n] tonnes was built from 8 of the [n] Scope 3 categories; 2025 emissions of [n] tonnes cover all [n]. A footnote says the reductions shown result partly from improvements to data quality and methodologies, but the report does not say whether the baseline was recalculated on the [n]-category boundary or how much of the fall is methodology rather than lower emissions.
The evidence, as filed
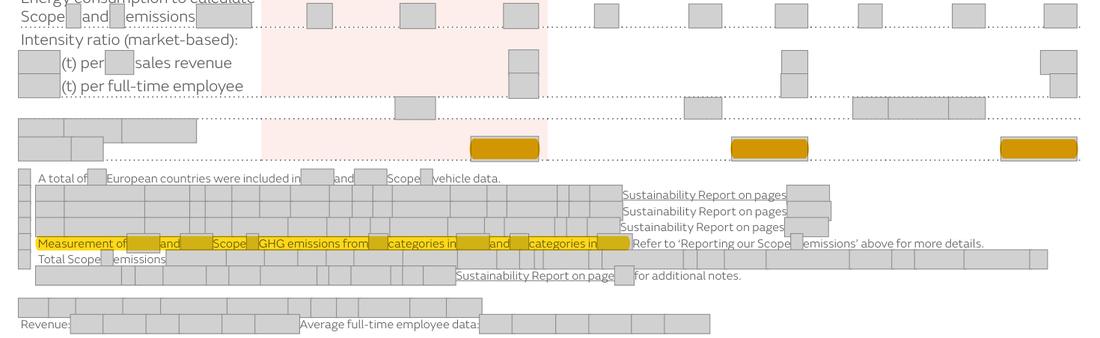
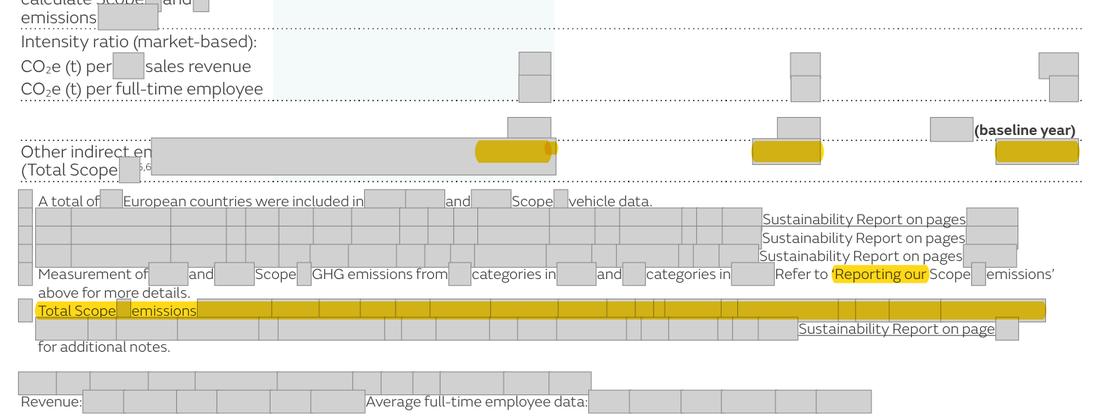
Further pages withheld to protect the company’s identity (two): Annual Report 2025, page 67; Annual Report 2025, page 73. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Headline KPI: Scope 3 down 60% from the 2021 baseline ([n] against [n] tonnes), with the baseline on 8 categories and 2025 on [n], and no statement whether the baseline was recalculated. | What the rule requires A Scope 3 reduction KPI computed on a like-for-like boundary (baseline recalculated for the categories added, or the methodology effect quantified), or the headline qualified where it appears, with the calculation basis described as the climate-related KPI disclosure requires. |
The rule
Companies Act 2006 s.414CB(2A)(h)
Version relied on: Companies Act 2006, revised text on legislation.gov.uk as in force for the financial year reviewed
a description of the key performance indicators used to assess progress against targets used to manage climate-related risks and realise climate-related opportunities and of the calculations on which those key performance indicators are based
Why it applies here: emissions fell sharply while the measured boundary widened, which points to a large methodology effect (for example a move from spend-based to activity-based factors); the report does not show whether the 2021 baseline was restated for the seven categories added or how much of the 60% is methodology.
Why it matters
Readers may take the 60% as a real fall in value-chain emissions on track for net zero by [n], when part of it, possibly most, reflects changes in how emissions are measured.
Exposure
A basis-of-calculation question on a climate KPI; dealt with by a basis note or a recalculated baseline in the next report.
Our workings
page 67 reports a 60% reduction in Scope 3 from the 2021 baseline. The GHG table on page 77 gives total Scope 3 of [n] tonnes for 2025, [n] for 2024 and [n] for the 2021 baseline year; footnote 5 says 2024 and 2025 cover [n] and [n] categories, and footnote 6 says the [wording masked] and improvements to data quality and methodologies. Page [n] says the 2021 baseline included data from eight of the [n] categories. The Annual Report 2024 gave 2023 Scope 3 of [n] tonnes from [n] categories, and 2024 of [n] from [n].
[n] / [n] = 40%, a 60% reduction (printed 60%); from 2023 to 2024 the total fell from [n] to [n], 48% in one year while one category was added.
The facts are disclosed in pieces; the question is the basis of the headline figure.
| Measure | Computation | Result |
|---|---|---|
| 2025 Scope 3 against 2021 baseline | [n] / [n] = 40%; 100% - 40% = 60% | 60% reduction (printed 60%) |
| 2024 against 2023 (as published in the Annual Report 2024) | [n] / [n] = 52%; 100% - 52% = 48% | 48% fall in one year, categories [n] to [n] |
| Categories measured | 2021 baseline 8; 2023 [n]; 2024 [n]; 2025 [n] | baseline covers 8 of [n] |
Management’s best defence, and our reply
Management would say the baseline year, the number of categories each year and the methodology effect (footnote 6) are all disclosed on the same pages, that base-year recalculation under the GHG Protocol depends on a significance threshold it applies, and that the 2025 Scope 3 total was independently assured for the first time; page 77 also refers readers to the 2025 Sustainability Report for the Scope 3 methodology and data notes. It could also argue that the added categories are small and that the fall reflects real supplier and logistics actions. That is a tenable position, so this is a question; but the headline 60% appears on the Planet page without the caveat, the size of the methodology effect is never given, and the [n]-to-2024 fall of 48% while a category was added suggests the effect is large.
The fix
- Either recalculate the 2021 Scope 3 baseline on the current [n]-category methodology and report the reduction against it, or qualify the headline wherever it appears: "60% below the 2021 baseline (8 categories); 2025 covers [n] categories and the change includes methodology improvements of approximately X%".
Question for the company
Was the 2021 Scope 3 baseline of [n] tonnes recalculated for the seven categories and the methodology changes introduced since 2021? If not, what would the baseline be on the 2025 methodology, and how much of the reported 60% reduction (and of the [n]-to-2024 fall from [n] to [n] tonnes) is due to changes in data and methodology rather than lower emissions?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | the headline Scope 3 KPI on the Planet page | Document | Annual Report 2025, page 67 |
| 2 | Scope 3 totals 2025, 2024 and 2021 baseline in the GHG table | Document | Annual Report 2025, page 77 |
| 3 | 2025 figure covers all [n] categories | Document | Annual Report 2025, page 77 |
| 4 | footnote 6: part of the reduction is methodology | Document | Annual Report 2025, page 77 |
| 5 | the 2021 baseline covers 8 of [n] categories | Document | Annual Report 2025, page 73 |
| 6 | Annual Report 2024: 2024, 2023 and 2021 baseline Scope 3 totals | Document | Annual Report 2024, page 77 |
| 7 | categories measured in 2023 and 2024 | Document | Annual Report 2024, page 77 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- Reporting our
- What is missing
- a statement whether the 2021 Scope 3 baseline was recalculated for the categories added since, or the share of the reduction due to methodology
- Pages looked at
- p.65-77 (ESG, TCFD, GHG and SECR pages) and p.17 (KPIs)
- Result
- 'base year' has no hit; 'recalculat' hits only p.201 (a finished goods provision in the auditor's report); 'restate' hits p.165, [n] (financial statements and remuneration items), none about emissions; 'baseline' hits p.67, [n] for the Scope 1 and 2 (2019) and Scope 3 (2021) baselines, which state the baseline year and categories but not whether it was recalculated, and p.61 and 155-159 (engagement and pay), unrelated.
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.