2.17 The Chief Executive's 2024 pension figure of [amount] cannot be reconciled with its footnote on the 2023 correction
UK Company A · a UK-listed medical technology group · Regulator-style question
In brief
The pensions table shows [amount] ([n]% of base salary) for the Chief Executive for 2024 and says it includes a [date] correction of a 2023 underpayment, and that the 2024 figure excluding the error was [amount]. But [amount] is exactly [n]% of his 2024 salary of [amount], and his 2025 pension is again [n]% ([amount]); on the footnote's own figures the 2024 contribution would have been only 2% of salary and the correction about [amount]. The report does not say how much the correction was or which year each part relates to.
The evidence, as filed
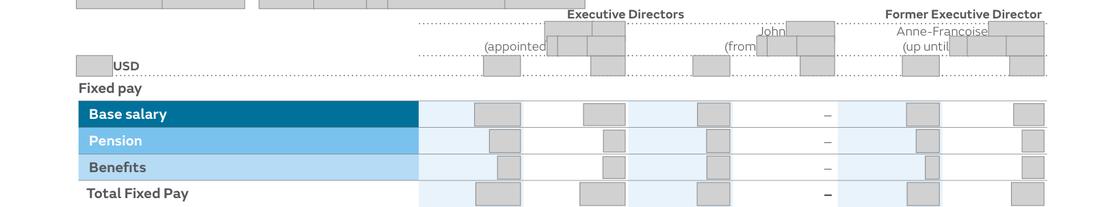
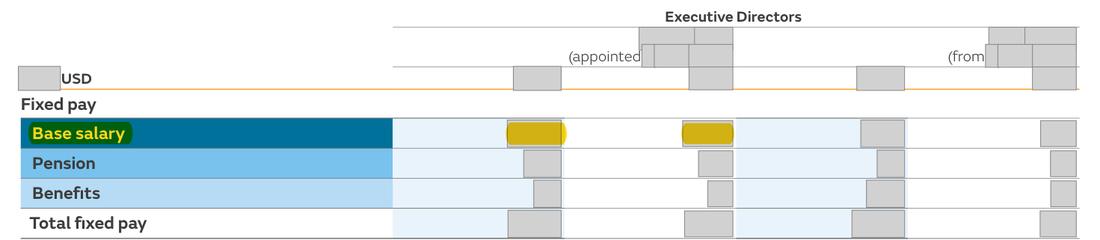
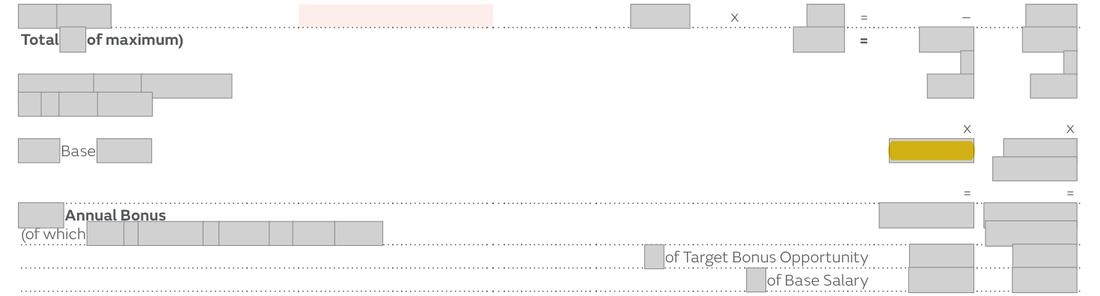
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 156; Annual Report 2025, page 176. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows Pension [amount] for 2024 shown as [n]% of base salary; footnote: includes the correction of a 2023 underpayment, 2024 figure excluding the error [amount]; 2023 comparative [amount]. | What the rule requires A figure whose components can be traced: the 2024 contribution, the amount of the 2023 correction and the year each relates to, with the [n]% rate applying to the 2024 element only. |
The rule
SI 2008/410 Schedule 8 paragraph 10(1)(e)(ii)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
what the aggregate pension input amount would be across all the pension schemes of the company or group in which the director accrues benefits
SI 2008/410 Schedule 8 paragraph 4(3)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
Unless otherwise indicated the sums set out in the table are those in respect of the relevant financial year and relate to the director’s performance of, or agreement to perform, qualifying services.
Why it applies here: either the [amount] is the 2024 entitlement alone (and the 2023 shortfall is reported nowhere), or it combines a 2% 2024 contribution with a [amount] catch-up (and the [n]% label is coincidental).
Why it matters
A reader cannot tell how much pension relates to 2024 service and how much to 2023, so the 2023 and 2024 single figures and the year-on-year change in benefits (shown as +[n]% on p.166) cannot be interpreted.
Exposure
Disclosure clarity in the remuneration report; no regulatory consequence expected.
Our workings
the pensions table shows '[amount]' and '[n]%' for the Chief Executive and the single figure shows pension [n] for 2024 and [n] for 2023. Footnote 1 says he 'was underpaid pension contributions in 2023', rectified in [date] and included in the figure, and that 'The figure for 2024 excluding this error was [amount].' The bonus table gives his 2024 base salary as [amount]. The 2025 report shows pension [n] for 2025 at [n]%.
[n]% x [n] = [n], so the whole [amount] equals a full year's contribution at [n]%; [n] - [n] = [n] would be the correction; [n] / [n] = 2% of salary; [n] / [n] = 2% in 2023; [n] / [n] = [n]% in 2025.
The report does not let a reader tell which.
| Item | Computation | Result |
|---|---|---|
| [n]% of 2024 base salary | [n]% x [n] | [n] |
| Implied correction on the footnote's figures | [n] - [n] | [n] |
| 2024 rate excluding the correction | [n] / [n] | 2% |
| 2023 rate | [n] / [n] | 2% |
| 2025 rate | [n] / [n] | [n]% |
| Implied correction in $ million | [n] / [n] | [n] |
Management’s best defence, and our reply
The company could say that the single figure records contributions paid in the year, as the pension input method measures them, so a correction paid in [date] belongs in 2024, and that the footnote disclosed it openly. It could add that [amount] is the contribution under the capped US plan and the rest is paid elsewhere. However, the footnote describes the excess over [amount] as the correction of an 'error', while the arithmetic and the 2025 figure show the same [n]% on full salary as a normal annual rate, so the two explanations conflict and only management can say which is right.
The fix
- Add to the footnote: 'The 2024 figure of [amount] comprises $X of contributions for 2024 and $Y paid in [date] to correct the 2023 underpayment.'
Question for the company
Please state how the Chief Executive's 2024 pension of [amount] splits between contributions for 2024 and the [date] correction for 2023, the amount of that correction, and why the 2024 figure equals [n]% of his full 2024 salary if the 2024 contribution excluding the correction was [amount].
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Pension [amount] shown as [n]% of base salary | Document | Annual Report 2024, page 156 |
| 2 | Footnote: the 2024 figure includes the correction of a 2023 underpayment | Document | Annual Report 2024, page 156 |
| 3 | Footnote: 2024 pension excluding the correction [amount] | Document | Annual Report 2024, page 156 |
| 4 | Single figure pension 2024 [amount], 2023 [amount] | Document | Annual Report 2024, page 155 |
| 5 | Base salary 2024 [amount], 2023 [amount] | Document | Annual Report 2024, page 155 |
| 6 | 2024 base salary used for the bonus: [amount] | Document | Annual Report 2024, page 157 |
| 7 | 2025 pension [amount], again [n]% of salary | Document | Annual Report 2025, page 176 |
| 8 | 2025 base salary [amount] | Document | Annual Report 2025, page 175 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.