2.14 The Directors' Report gives an average buyback price of [amount] a share, but the shares and consideration it states imply [amount]
UK Company A · a UK-listed medical technology group · Regulator-style question
In brief
The Directors' Report says [n] shares were bought [wording masked] [amount] for a total consideration of [amount]. Those shares at [amount] would have cost about [amount]. The company's own final buyback announcement gives a cost of [amount] for the same [n] shares, an average of [amount], and the share capital note gives a total cost of [amount] including [amount] of costs, an average of [amount]. None of these reproduces [amount].
The evidence, as filed
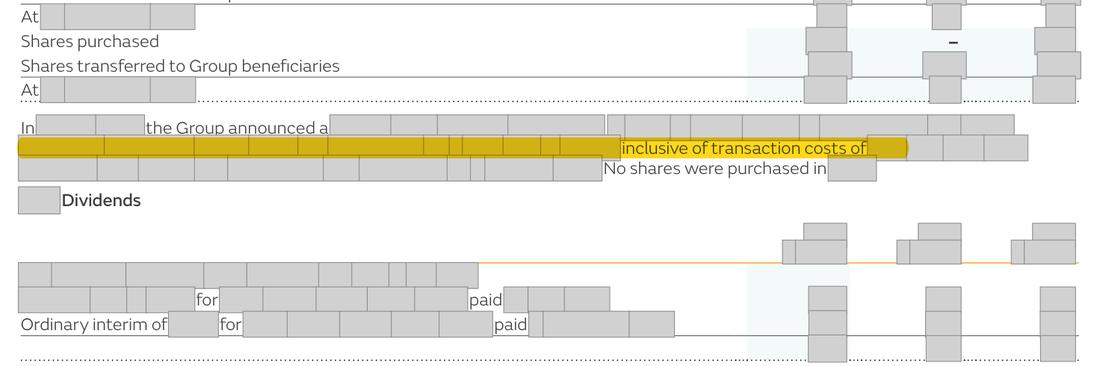
Further pages withheld to protect the company’s identity (one): Annual Report 2025, page 196. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows [n] [wording masked] [amount] [wording masked] [amount]'. | What the rule requires An average price consistent with the shares and the consideration stated (about [amount] a share), or a note of the basis on which [amount] is calculated. |
The rule
SI 2008/410 Schedule 7 Part 2 paragraph 9(a)
Version relied on: Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410), in force from April 2008, as amended (the directors’ remuneration report Schedule 8 as substituted from October 2013); revised text, legislation.gov.uk
the number and nominal value of the shares so purchased, the aggregate amount of the consideration paid by the company for such shares and the reasons for their purchase
Why it applies here: the average price printed does not agree with the report's own number of shares and consideration, or with the company's announcement; the price is a voluntary figure, but the consideration it sits beside is required, and a reader multiplying the two will not reach the stated total.
Why it matters
The stated average price overstates what the company paid per share by about 1%, so the figures in the buyback paragraph do not agree with each other or with the company's announcement.
Exposure
Accuracy of a voluntary figure in the Directors' Report; no regulatory consequence expected.
Our workings
the Directors' Report states the number of shares bought ([n]), the volume weighted average price ([amount] and the total consideration ([amount]). Note 19 states a total cost of [amount] including [amount] of transaction costs for the same [n] shares. The company's announcement of [date] states that it had purchased [n] shares at a cost of [amount].
[n] x [n] = [amount], which is [amount] more than the stated consideration; [amount] / [n] = [amount] a share; [amount] / [n] = [amount] a share including costs.
| Item | Computation | Result |
|---|---|---|
| Consideration implied by the printed average price | [n] x [n] | [amount] ([n]) |
| Average price from the final buyback announcement | [n] / [n] | [amount] |
| Average price from the stated consideration | [n] / [n] | [amount] |
| Average price on the note's total cost including [amount] costs | [n] / [n] | [amount] |
| Difference per share | [n] - [n] | [amount] |
| Difference in consideration | [n] - [n] | [amount] |
| Difference as % of the consideration | [n] / [n] | 1% |
| Difference as % of 2025 profit before tax | [n] / [n] | 1% |
Management’s best defence, and our reply
The company could say that the volume weighted average price was computed from the sterling prices of the daily purchases and translated at a single exchange rate, or from market volume-weighted prices rather than the prices paid, so it need not equal consideration divided by shares. It could add that the figure is voluntary and the required consideration is correctly stated. However, the report does not say so, the phrase 'for a total consideration' links the two figures directly, and on the company's own announcement the price actually paid averaged [amount], so the basis needs to be stated or the figure corrected.
The fix
- Correct the sentence: '[n] [wording masked] [amount] [wording masked] [amount]', or state the basis of the [amount] figure.
Question for the company
Please explain how the volume weighted average price of [amount] was calculated, given that the [n] shares bought cost [amount] according to the announcement of [date], an average of [amount], and confirm which figure is correct.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Directors' Report: [n] shares, average price [amount], consideration [amount] | Document | Annual Report 2025, page 196 |
| 2 | Note 19: total cost [amount] including [amount] transaction costs | Document | Annual Report 2025, page 261 |
| 3 | Final buyback announcement: cost [amount] for [n] shares | Document |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.