2.05 The Board's list of 2025 activities includes approving a [amount] bond issue that the notes show took place in 2024
UK Company A · a UK-listed medical technology group · Presentation point
In brief
Under '2025 activities and outcomes' the Board lists approving the [amount] general corporate purposes bond issue [wording masked] revolving credit facility (RCF). The borrowings note says the two bonds of [amounts] were issued during 2024, and that the [amount] of private placements were repaid in 2024. In 2025 the financing table shows no bond proceeds and private placement notes stayed at [amount]. The bullet is the 2024 text carried forward unchanged from the prior-year report.
The evidence, as filed
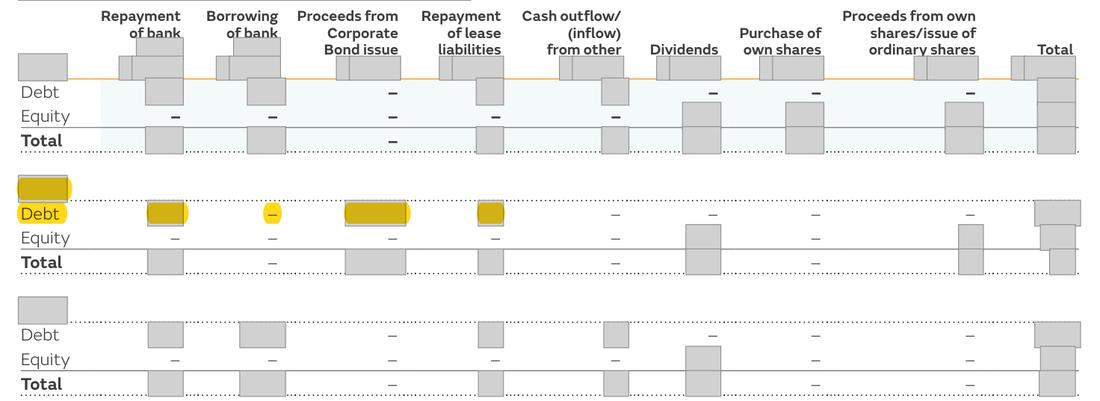
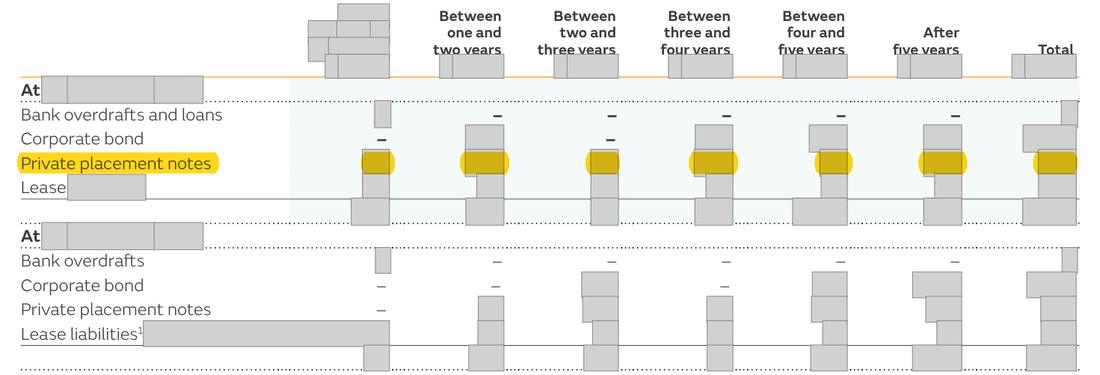
Further pages withheld to protect the company’s identity (three): Annual Report 2025, page 113; Annual Report 2024, page 115; Annual Report 2025, page 240. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows p.113, '2025 activities and outcomes': 'Approving the [amount] [wording masked]'. Notes: bonds of [amounts] issued during 2024; [amount] private placements repaid in 2024; 2025 bond proceeds nil. | What the rule requires The 2025 list of Board activities should describe 2025 decisions only (for example the 2025 repurchase of part of the [n]% 2030 bond), or the 2024 bond approval should be removed. |
What we checked: Board priorities page against note [n] borrowings, the net debt financing table and the prior-year report's Board priorities page (p.115 of the 2024 report).
The rule
UK Corporate Governance Code 2024, Principle C
Version relied on: UK Corporate Governance Code, FRC, January 2024; applies to financial years beginning in or after January 2025 (Provision 29 from January 2026)
Governance reporting should focus on board decisions and their outcomes in the context of the company’s strategy and objectives.
Why it applies here: the bullet was rolled forward from the 2024 governance report without being updated, so the 2025 report attributes a 2024 Board decision to 2025.
Why it matters
A reader of the governance report is told the Board approved and executed a [amount] financing in 2025 that did not happen in 2025; the account of the Board's year is less reliable and the 2025 bond repurchase it did approve is not mentioned here.
Exposure
Narrative inconsistency in the governance report; no figure in the accounts is affected.
Our workings
the governance report lists, under '2025 activities and outcomes' for capital allocation, the approval of a [amount] general corporate purposes bond issue that '[wording masked]'.
note [n] states that during 2024 [wording masked] [amounts] and that in 2024 the Group repaid [amount] of private placement debt; the cash flows arising from financing activities show proceeds from corporate bond issue of nil for 2025 and ([n]) for 2024; private placement notes outstanding were [n] at both year ends.
the prior-year report printed the identical bullet under '2024 activities and outcomes'.
[n] + [n] = [n], which is the 2024 issue.
It does not affect any figure in the accounts, but it is a statement about what the Board did in the year that the audited notes contradict.
| Item ($ million) | 2025 | 2024 | Source |
|---|---|---|---|
| Proceeds from corporate bond issue | - | ([n]) | Financing activities table, p.263 |
| Bonds issued in 2024: [n] + [n] = [n] | - | [n] | Note 15.2, p.240 |
| Private placement notes outstanding | [n] | [n] | Maturity table, p.239 |
Management’s best defence, and our reply
Management could say the bullet summarises the Board's standing oversight of the funding structure, the bonds remained the Group's main financing in 2025, and the list is illustrative rather than a minute of decisions. It could add that the 2025 financing decisions (bond repurchase, RCF extension) are fully disclosed in note [n]. However, the bullet sits under the heading '2025 activities and outcomes', uses the past tense ('was used to repay') and repeats the prior year's text word for word, while note [n] dates both the issue and the repayment to 2024; an illustrative list still has to be accurate for the year it describes.
The fix
- Delete the bullet or replace it with the 2025 decision, e.g. (if these were Board decisions) 'Approving the repurchase of [amount] of the [n]% 2030 corporate bond and the extension of the [amount] RCF to 2030'.
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | The Board lists the [amount] bond approval under its 2025 activities and outcomes for capital allocation | Document | Annual Report 2025, page 113 |
| 2 | The notes date the [amount] of bond issues to 2024 | Document | Annual Report 2025, page 240 |
| 3 | The private placement repayment funded by the bonds also took place in 2024 | Document | Annual Report 2025, page 240 |
| 4 | Financing cash flows: proceeds from corporate bond issue of [n] in 2024 and nil in the 2025 row | Document | Annual Report 2025, page 263 |
| 5 | Private placement notes of [n] still outstanding at [date] ([n] also at [date]): none repaid in 2025 | Document | Annual Report 2025, page 239 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.