1.16 Interest rate profile: the swapped euro bond is fixed rate in the 2024 report and the 2024 comparative but floating in 2025, and currency swaps change basis between the columns
UK Company A · a UK-listed medical technology group · Regulator-style question
In brief
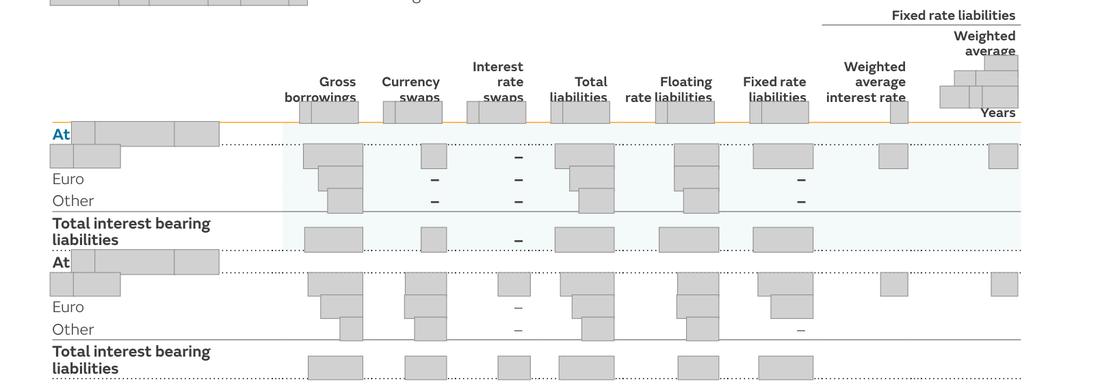
The interest rate profile treats two items differently in its two columns. The euro borrowings are all floating at [date] ([amount]) but [amount] fixed at [date], although the fixed-to-floating swap on the [amount] bond was in place at both dates. The 2024 report's own Group profile already showed the [amount] as fixed rate while saying on the same page that the [amount] debt had been swapped to floating, so the 2025 comparative carries forward an inconsistency first printed in 2024. Currency swaps appear at gross amounts in 2024 ([amount] in liabilities, [amount] in assets) but at fair value in 2025 ([amount] each), although the company note shows [amount] of swaps outstanding. No footnote explains either change and the 2024 column was not re-presented on the 2025 basis.
The evidence, as filed
Further pages withheld to protect the company’s identity (four): Annual Report 2024, page 225; Annual Report 2025, page 247; Annual Report 2024, page 226; Annual Report 2025, page 269. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows 2025: euro row gross ([n]), floating ([n]), fixed nil; currency swaps (2) in liabilities and 2 in assets; total interest-bearing liabilities ([n]), fixed ([n]). 2024: euro row fixed ([n]); currency swaps ([n]) in liabilities and [n] in assets; total ([n]), fixed ([n]). The note says swaps convert [amounts] of debt to floating; the company note gives currency swap notionals of [amount]. 2024 report, same note: 'Other' borrowings fixed ([n]) beside the statement that interest on [amount] debt was swapped from fixed to floating. | What the rule requires Both columns on the same basis: either the 2024 euro bond shown as floating and currency swaps shown on the 2025 basis, or a footnote explaining each change of basis and why the comparative was not re-presented. |
The rule
IAS 1 Presentation of Financial Statements, paragraph 41
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
When presentation or classification changes, the comparatives must be reclassified (unless impracticable), with disclosure of what was reclassified, how much and why.
IFRS 7 Financial Instruments: Disclosures, paragraph 34(a)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
For each type of financial risk, the accounts must give summary numbers on the exposure at the year end, based on what is reported internally to key management.
Why it applies here: the year-on-year movements in the profile mix changes of basis with real changes in exposure; the [currency] swap started in [date], so its treatment does not differ between the columns.
Why it matters
A reader comparing the columns sees total interest-bearing liabilities fall from [n] to [n] and the fixed share fall from [n]% to 65%; much of both movements is a change in presentation rather than a change in the group's exposure.
Exposure
Disclosure comparability only; no recognised amount is affected.
Our workings
the 2025 profile shows all [amount] of euro borrowings as floating rate; the 2024 comparative shows [amount] of euro borrowings as fixed rate. The hedge table in the same note shows the [amount] interest rate swap on the euro bond with a carrying amount of [n] at [date], and the 2024 report said that swap was entered into in 2022. The 2024 columns also include currency swaps of ([n]) in liabilities and [n] in assets, which match the gross notionals in the 2024 company note, while the 2025 columns show only 2, the swaps' fair value, although the company note shows notionals of [amount] at [date].
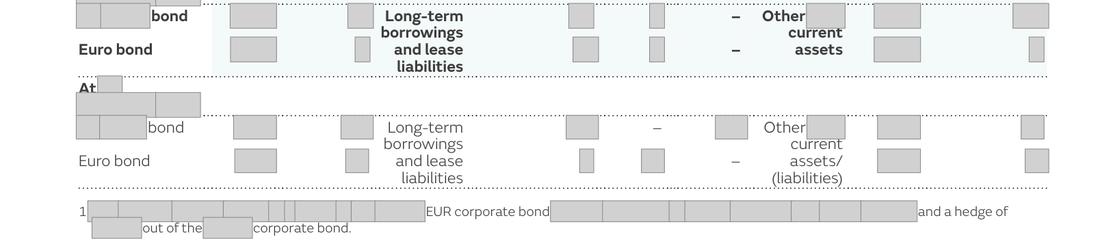
the 2024 report's own profile showed the non-[currency] borrowings, mainly the euro bond, as fixed rate ([n]) and stated on the same page that interest on the [amount] debt had been swapped from fixed to floating, the swap having been in place since 2022.
on the 2025 basis the 2024 fixed-rate total would be [n] - [n] = [n], or [n]% of interest-bearing liabilities rather than [n]%; of the [n] fall in total interest-bearing liabilities, [n] is the change in how currency swaps are shown.
| Measure | 2024 as printed | 2025 as printed / computed |
|---|---|---|
| Euro fixed-rate liabilities | [n] | 0 (all [n] floating) |
| Currency swaps in the liabilities profile | [n] | 2 |
| Currency swaps in the assets profile | [n] | 2 |
| Fall in total interest-bearing liabilities | [n] | [n] - [n] = [n] |
| of which currency swap presentation | [n] - 2 = [n] | |
| Fixed share as printed | [n] / [n] = [n]% | [n] / [n] = 65% |
| 2024 fixed total on the 2025 euro basis | [n] - [n] = [n] | [n] / [n] = [n]% |
Management’s best defence, and our reply
The company can argue that this profile is the summary data reported internally to key management personnel, so its basis may legitimately change as internal reporting changes, and that the 2024 column simply reproduces the figures published last year. The swaps are fully disclosed elsewhere in the note and no recognised amount moves. However, comparatives in the same table should be on the same basis, re-presentation was plainly practicable from figures already in the note, and without it the year-on-year movements are overstated; because the internal-reporting argument is reasonable, the point is put as a question.
The fix
- Re-present the 2024 columns on the 2025 basis (euro bond floating; currency swaps at fair value), or add a footnote: 'The 2024 comparative is presented before the effect of the [amount] interest rate swap and includes currency swaps at their gross amounts.'
Question for the company
Was the euro bond shown as fixed rate in the 2024 report's profile, and in the 2024 comparative of the 2025 report, before the effect of the [amount] fixed-to-floating swap, and were currency swaps shown at gross amounts in 2024 but at fair value in 2025; if so, why was the comparative not re-presented or the change of basis explained?
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | 2025: all euro borrowings shown as floating rate, none fixed | Document | Annual Report 2025, page 246 |
| 2 | 2024 comparative: [amount] of euro borrowings shown as fixed rate | Document | Annual Report 2025, page 246 |
| 3 | 2024 totals: interest-bearing liabilities [n], fixed [n] | Document | Annual Report 2025, page 246 |
| 4 | 2024 total row: currency swaps of ([n]) included at their gross amount | Document | Annual Report 2025, page 246 |
| 5 | 2025 totals: currency swaps (2), interest-bearing liabilities [n], fixed [n] | Document | Annual Report 2025, page 246 |
| 6 | 2025 assets profile: currency swaps 2 | Document | Annual Report 2025, page 247 |
| 7 | 2024 assets profile: currency swaps [n] | Document | Annual Report 2025, page 247 |
| 8 | the [amount] fixed-to-floating swap on the euro bond was in place at [date] (swap asset [n], nominal [n]) | Document | Annual Report 2025, page 245 |
| 9 | the note says the swaps convert the euro bond to floating rate | Document | Annual Report 2025, page 247 |
| 10 | company note: currency swaps with notionals of [amount] outstanding at [date] (2024: [amount] receivable, [amount] payable) | Document | Annual Report 2025, page 269 |
| 11 | the 2024 report: the euro swap dates from 2022; the [currency] swap was forward-starting in [date] | Document | Annual Report 2024, page 225 |
| 12 | At [date] the non-[currency] borrowings of [amount], which include the EUR corporate bond, are shown with [amount] as fixed rate liabilities | Document | Annual Report 2024, page 226 |
| 13 | The 2023 column treats the same bond the same way: [amount] fixed rate | Document | Annual Report 2024, page 226 |
| 14 | The sentence under the same table says the [amount] debt pays floating rate after the swap | Document | Annual Report 2024, page 226 |
| 15 | Identifies the [amount] debt as the EUR corporate bond, about [amount] | Document | Annual Report 2024, page 226 |
| 16 | 2024 profile: the non-[currency] borrowings, mainly the euro bond, shown as fixed rate ([n]) | Document | Annual Report 2024, page 226 |
| 17 | The same page says the euro bond's interest was swapped to floating | Document | Annual Report 2024, page 226 |
| 18 | The swap had been in place since 2022, so it applied at both dates in the 2024 report | Document | Annual Report 2024, page 225 |
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.