1.01 The lease disclosures do not give the total cash outflow for leases
UK Company A · a UK-listed medical technology group · Compliance or disclosure gap
In brief
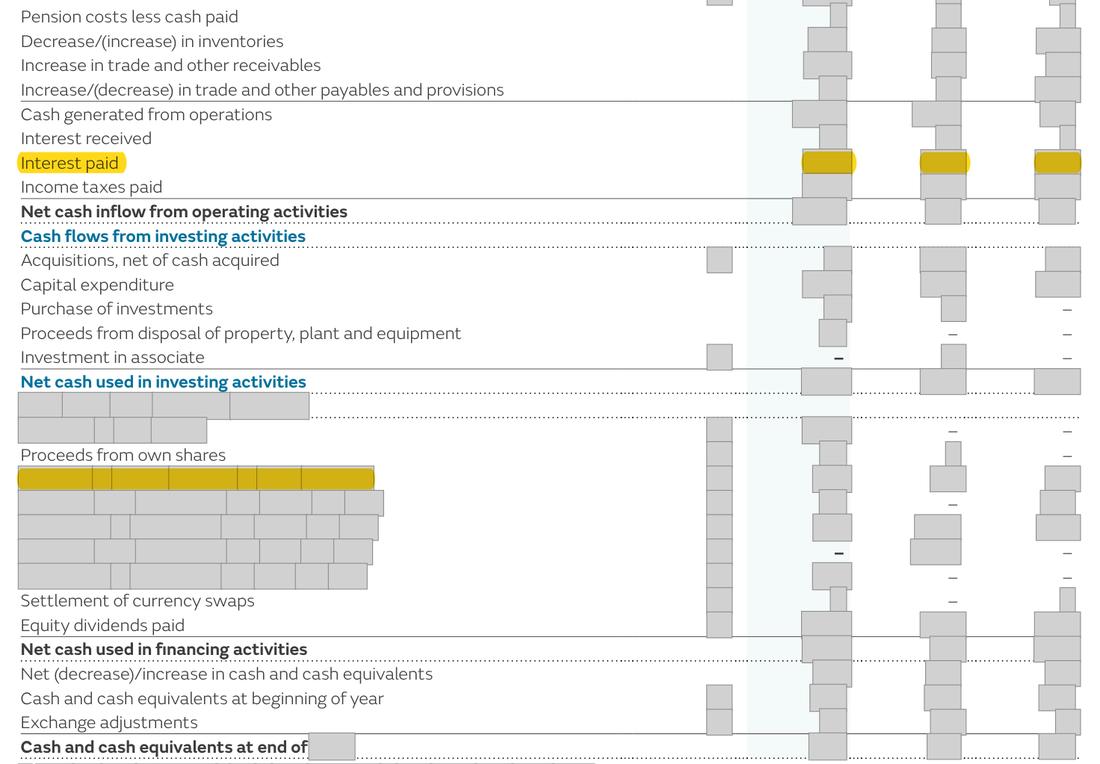
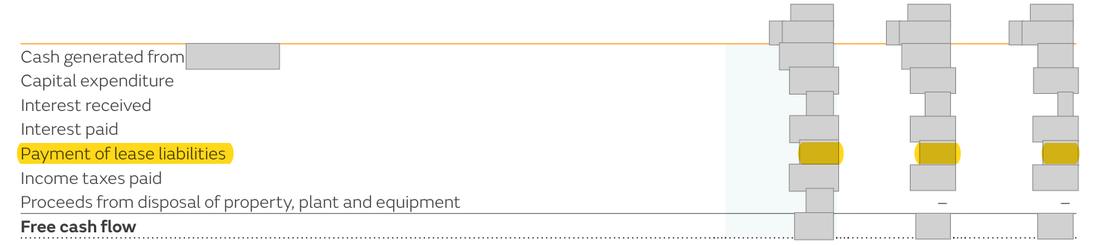
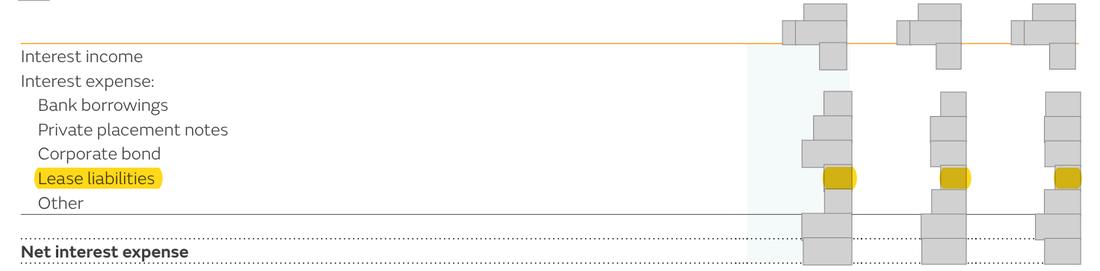
International Financial Reporting Standard (IFRS) [n] asks a lessee to disclose its total cash outflow for leases. The Group's lease information (right-of-use assets in Note 7, lease liabilities in Note 15, lease interest in Note 4) gives depreciation, additions, interest expense and maturities, but no total cash outflow in 2025 or 2024. The cash-flow statement shows only the capital element ([amount] in 2025, [amount] in 2024); lease interest paid sits inside total interest paid of [amount].
The evidence, as filed
Further pages withheld to protect the company’s identity (two): Annual Report 2024, page 211; Annual Report 2025, page 229. Their wording or layout could lead back to the company even with names and figures masked; the evidence list below records what each page shows.
Names, figures, dates, logos and any wording that could be searched back to the company are boxed out in grey; the point is highlighted in yellow.
What the report shows, and what the rule requires
| What the annual report shows | What the rule requires |
|---|---|
| What the annual report shows No figure for total cash outflow for leases in either year; capital element of lease payments [amount] (2024: [amount]) in financing cash flows; interest paid [amount] (2024: [amount]) not split; lease interest expense [amount] (2024: [amount]). | What the rule requires One figure for the total cash outflow for leases in each year (capital and interest payments, plus short-term, low-value and variable lease payments), placed with the other lease disclosures. |
The rule
IFRS 16 Leases, paragraph 53(g)
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
Among the lease amounts a lessee must give is the total cash paid out for leases in the period.
IFRS 16 Leases, paragraph 52
Version relied on: UK-adopted international accounting standards (UK Endorsement Board), as in force for financial years beginning in or after January 2025
A lessee may point to lease information already given elsewhere in the accounts instead of repeating it, as long as the lease note cross-refers to it.
Why it applies here: the paragraph 53(g) figure is not given and cannot be read from the statements, because lease interest paid is not separated from other interest paid.
Why it matters
- A reader cannot see the full cash cost of the Group's leases, which IFRS 16 requires as a single figure.
- The realistic outcome of an FRC question is an undertaking to add the figure; no amount changes.
A reader cannot see the full cash cost of the Group's leases, which IFRS 16 requires to be given as a single figure.
Exposure
A Financial Reporting Council enquiry letter and an undertaking to add the figure in the next report; revision of the accounts is not expected for a disclosure of this kind.
Our workings
Note 7 gives the right-of-use asset movements by class (depreciation and additions); Note 4.1 gives lease interest expense of [amount]; Note 15 gives lease liabilities and their maturity analysis; the cash-flow statement shows '[wording masked] [amount] (2024: [amount]) and total 'Interest paid' of [amount] (2024: [amount]). The terms 'total cash outflow', 'cash outflow for leases' and 'payments for leases' do not appear anywhere in the report, and the 2024 report did not give the figure either.
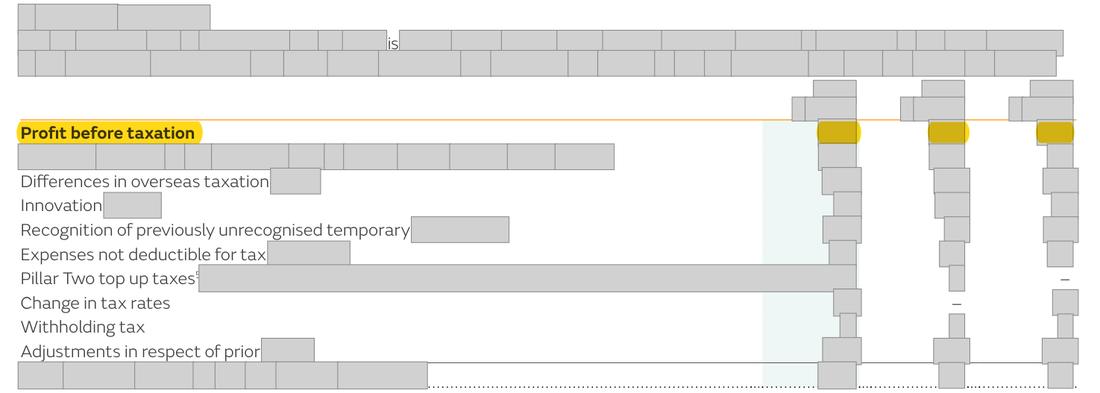
the capital element alone is [amount], [n]% of 2025 profit before taxation of [amount]; the total would be higher by lease interest paid and any short-term or variable payments.
| Item | 2025 ([currency]m) | Arithmetic / source |
|---|---|---|
| Capital element of lease payments (financing cash flows) | [n] | Group cash flow statement |
| Lease interest expense (not the cash paid) | 8 | Note 4.1 |
| Capital element as a share of profit before taxation | [n]% | [n] / [n] = [n]% |
Management’s best defence, and our reply
Management may say the information is effectively there: the capital element is on the face of the cash-flow statement, lease interest of [amount] is in Note 4.1 and the policy states that short-term and low-value leases are not material, so a reader can add the parts; IFRS 16 paragraph 52 allows information presented elsewhere not to be duplicated. They may add that lease cash flows are small beside the Group's operating cash flow, so the figure is not material information. However, paragraph 52 needs a cross-reference from the lease note, and there is none; lease interest paid is not presented anywhere (Note 4.1 gives the expense, and the cash-flow statement gives only total interest paid); and the capital element alone is [amount], [n]% of profit before taxation, so materiality does not remove a figure the standard names specifically.
The fix
- Add to Note 7: 'The total cash outflow for leases in 2025 was $Xm (2024: $Ym), comprising capital repayments of [amount] (2024: [amount]), interest of $Zm and short-term, low-value and variable lease payments of $Wm.'
Evidence relied on
| # | What it shows | Type | Where |
|---|---|---|---|
| 1 | Cash-flow statement gives only the capital element of lease payments | Document | Annual Report 2025, page 213 |
| 2 | Interest paid is one total; lease interest paid is not separated | Document | Annual Report 2025, page 213 |
| 3 | Capital element of lease payments [n] (2025) and [n] (2024) | Document | Annual Report 2025, page 290 |
| 4 | Lease interest expense 8 in each year | Document | Annual Report 2025, page 223 |
| 5 | 2025 profit before taxation [n], the scale benchmark | Document | Annual Report 2025, page 226 |
Absence check
- Document
- Annual Report 2025
- Where it would appear
- [wording masked]:
- What is missing
- the total cash outflow for leases for 2025 and 2024
- Pages looked at
- p.213-214 (cash-flow statement), [n] (Note 4), 230-231 (Note 7), 241-242 (Note 15), 264-265 (Note 20 net debt)
- Result
- 'lease payments' hits only the measurement policy on p.228 (no amount); 'cash outflow' hits restructuring and legal cash outflows in the financial review, derivative outflows in the liquidity table and the financing-activities reconciliation heading, which shows repayment of lease liabilities (capital only); none gives the total cash outflow for leases
Prepared by Pramanex from the company’s published annual reports, without the company’s involvement, to show how an annual report review reads. The company is not named, and nothing on this page is a statement about any identifiable company. Observations are not an audit, review or other assurance engagement, and not legal advice. A regulator-style question is a question, not a conclusion.
Want this on your own annual report, before it is published?
Start with three free findings on your latest published annual report, or talk to us about a fixed-fee pre-publication review.
Your annual report will be in draft before the year-end audit.
Have it read before it is published.
Under NDA, with our reviewer on your insider list under UK MAR.